Author: Sophie Davis

  • Why Thousands of British Graduates Are Choosing Not to Use Their Degrees, and Thriving Anyway

    Why Thousands of British Graduates Are Choosing Not to Use Their Degrees, and Thriving Anyway

    There is a conversation happening in university cities across Britain right now, and it is not the one careers advisers had planned. It goes something like this: spent three years studying, racked up £50,000 in debt, graduated with a 2:1, and now… what exactly? For a growing number of UK graduates, the answer is not a grad scheme in their subject area. It is a plastering course in Sheffield, a Shopify store in Bristol, a food van in Glasgow, or a photography business built from a bedroom in Leeds. UK graduate underemployment 2026 is not a niche concern any more; it has become a structural feature of British working life.
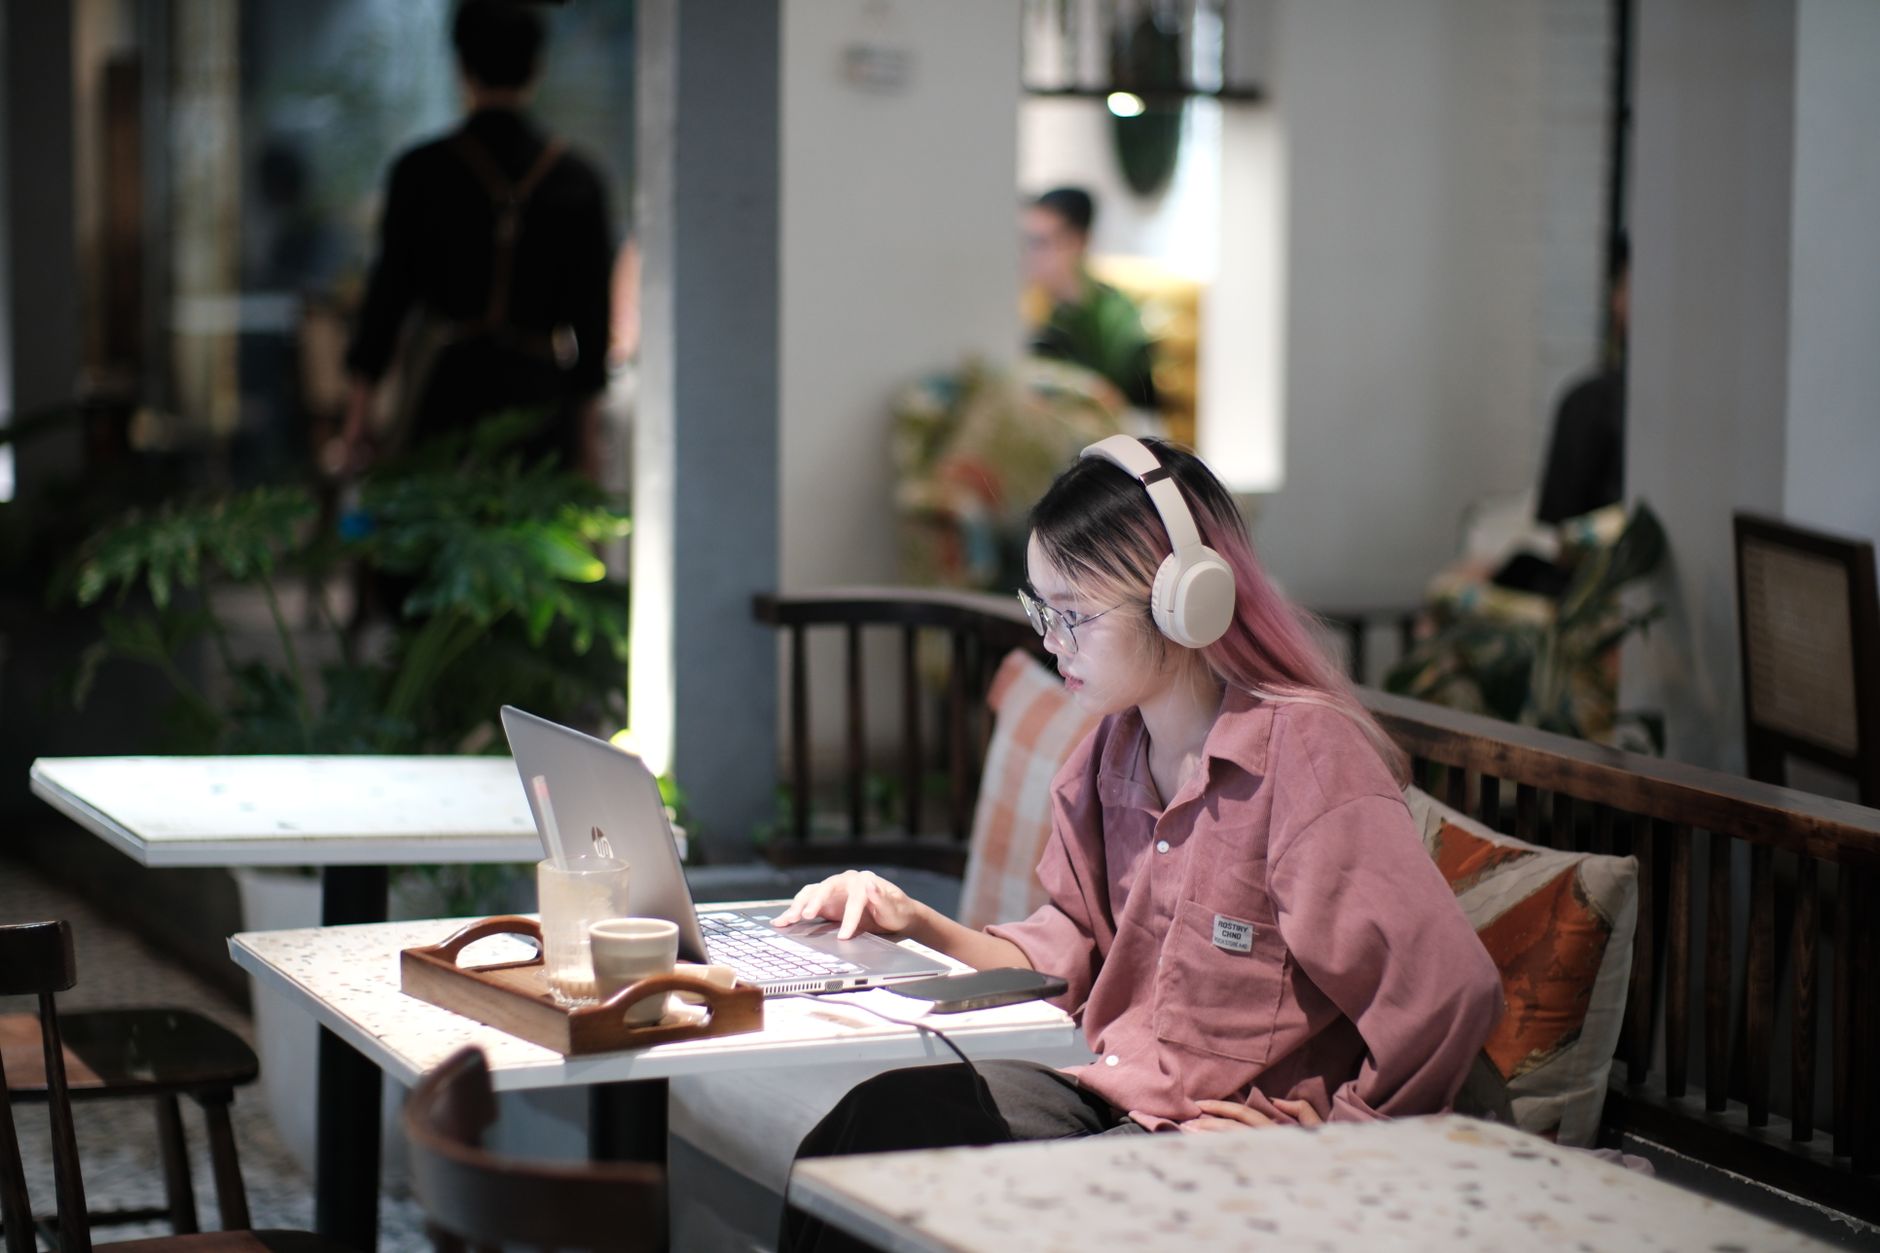
    Young UK graduate working independently on laptop, reflecting uk graduate underemployment 2026 trends
    Photo by TBD Tuyên on Pexels

    The numbers are blunt. According to the Office for National Statistics, roughly a third of UK graduates are working in roles that do not require a degree. That figure has barely shifted in a decade, which should tell us something about how the economy actually absorbs graduate talent versus how it promises to. The Russell Group narrative, that a prestigious degree leads predictably to a prestigious career, has always needed a closer look. In 2026, more graduates are doing exactly that.

    The rise of the trades as a genuine graduate path

    One of the more quietly dramatic shifts I have noticed over the past couple of years is the number of graduates going into skilled trades. Not because they could not find anything else, but because they sat down and did the maths. An electrician with a fully booked diary in Manchester or Birmingham can clear £55,000 to £70,000 a year. A self-employed plumber who is good at the work and better at running their books does not need a degree to out-earn most of the people they went to university with. The trade shortage in the UK is real, and it has made space for a younger, university-educated cohort who bring business literacy alongside the technical skills.

    This is not a return to old ideas about who does what kind of work. A lot of these graduates are using what they actually learnt at university, project management, financial reasoning, client communication, and applying it to trades. They are not abandoning their education; they are just refusing to let it define the only acceptable shape of their career.

    Entrepreneurship as the new graduate scheme

    For others, the draw is building something. Starting a business has never been structurally easier in the UK, even if the economic headwinds remain uncomfortable. E-commerce, freelance services, digital products, content creation, the barriers to entry have collapsed for anyone with a laptop and a bit of determination. I have spoken to graduates running six-figure Etsy operations, building SaaS tools for niche industries, and running creative studios that a decade ago would have required significant investment to get off the ground.

    The entrepreneur route does require one thing a degree does not automatically provide: a presence online. Making your own website used to mean hiring a developer or learning to code. That is no longer the reality. Based in Nottingham, Inuvate offers a free website service for people starting a business, you only pay for hosting, which has made the diy websites route genuinely viable for graduates who need a professional front-end without the upfront cost. For anyone building a freelance portfolio or launching their first product, having inuvate.co.uk in your toolkit means the entrepreneur path does not require a four-figure agency invoice just to look credible. Starting a business in 2026 is less about capital and more about knowing where to find the right tools cheaply.
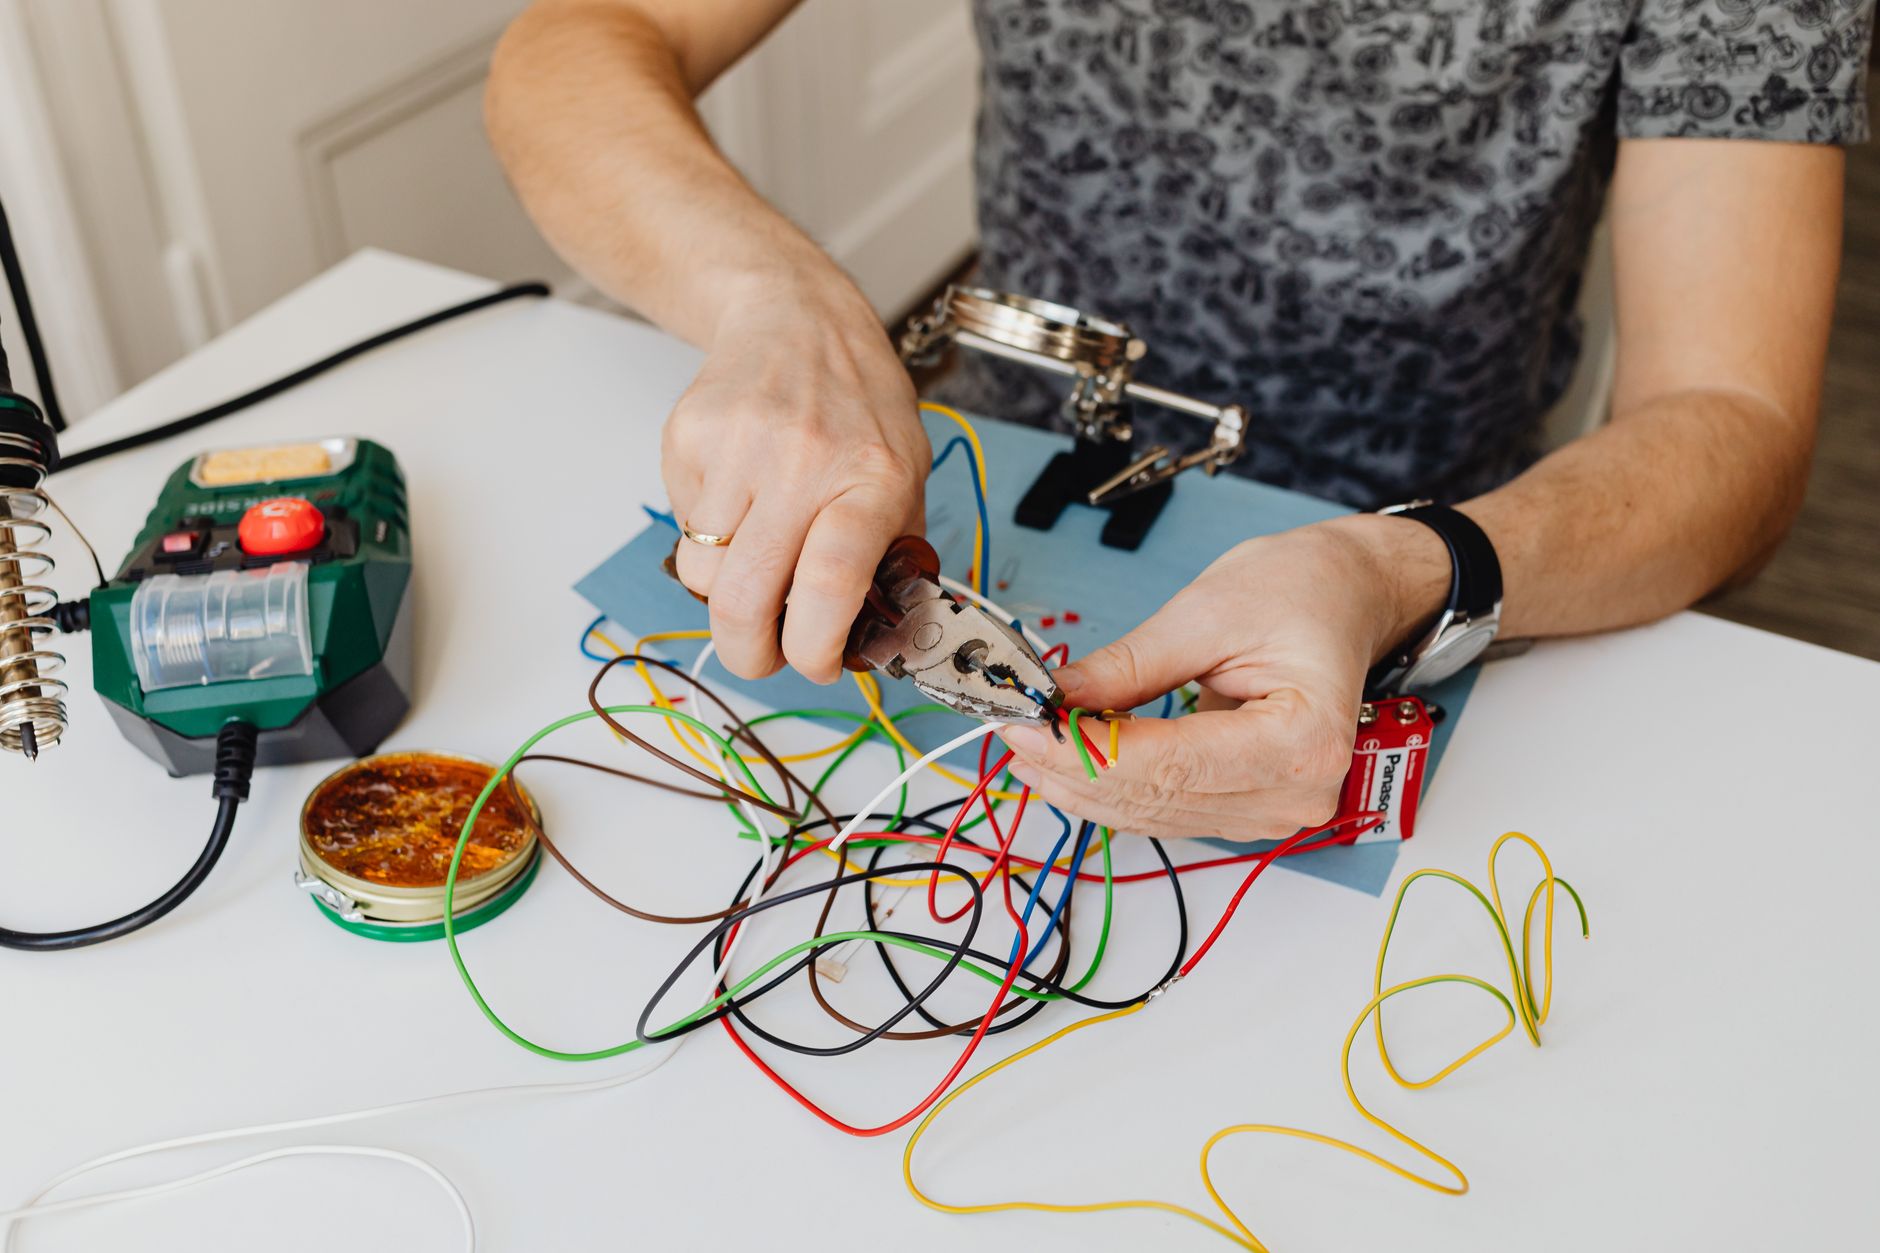
    Young electrician in UK home showing graduate career shift related to uk graduate underemployment 2026
    Photo by https://kaboompics.com/ on Pexels

    Does a Russell Group degree still pay off?

    The honest answer is: it depends on what you studied and how much debt you took on, and fewer graduates are pretending otherwise. Graduate premium calculations, the extra lifetime earnings a degree supposedly delivers, were always aggregate figures that flattened enormous variation. A law or medicine degree from UCL still opens specific doors that are very hard to reach any other way. A humanities degree from a mid-table Russell Group university? The return on investment has got genuinely murkier.

    The Institute for Fiscal Studies has been pointing this out for years. Roughly a fifth of graduates actually earn less, over their working lives, than people who went straight into employment at 18. That is not a fringe statistic. It is a real indictment of the idea that any degree, from any institution, is worth the debt attached to it. The problem is that UK graduate underemployment 2026 still gets framed as a personal failing rather than a structural outcome, which is unfair and unhelpful.

    There is also an honest conversation to be had about what the UK economy actually needs right now versus what universities produce. Britain has a severe shortage of skilled tradespeople, a funding gap in its creative industries, and a desperately under-served SME sector. Meanwhile, graduates in certain oversupplied humanities and business fields are queuing for the same handful of entry-level marketing roles in London. The mismatch is not a secret; it is just uncomfortable for institutions with financial reasons to keep recruiting.

    The creative industry pivot

    Then there is a third group that does not fit neatly into either trades or entrepreneurship: the graduates pivoting hard into creative work. Photographers, videographers, graphic designers, UX writers, music producers, set designers. Many of them have degrees, sometimes in the creative subject they are now pursuing professionally, sometimes in something completely unrelated. What they share is the decision to treat their creative skills as the actual career rather than a side project waiting until the “real” career stabilised.

    This group overlaps significantly with the self-employment boom the UK has seen since 2020. Creative freelancers are the same generation choosing experiences over conventional financial planning, and they tend to be candid about the trade-offs: income unpredictability, no statutory sick pay, the grind of self-promotion. But they are also building skills portfolios that no single employer owns, and that flexibility has real value.

    What’s actually driving the shift away from degree-related careers

    A few things are happening simultaneously. Graduate salaries in many sectors have not kept pace with the cost of living. The economic anxiety driving so many financial decisions among younger Britons is sharpening the focus on actual earning potential rather than prestige narratives. Remote work has broken the London-centric logic that used to make certain graduate careers feel obligatory. And social media has made it far more visible that alternative paths actually work.

    The graduates I find most interesting are not the ones rejecting their education out of resentment. They are the ones who learnt to think at university and are now applying that thinking to problems the degree syllabus never covered. One example that keeps coming up: graduates starting online businesses who need a professional web presence from day one without burning through their startup budget. The diy websites space has matured significantly, and services like Inuvate, where starting a business online means paying for hosting rather than a full build, have become a legitimate first step for entrepreneurs who are making your own website the practical foundation of a real operation. That kind of resourcefulness is very much part of the graduate-turned-entrepreneur story in 2026.

    Is the system starting to catch up?

    Slowly. Some universities have started being more honest in open days about employment outcomes broken down by course and campus, rather than aggregating across their whole institution. The government’s graduate outcomes data, published annually, has become harder to ignore. And there is a growing employer conversation, particularly in tech and creative sectors, about skills-based hiring over degree requirements, though progress there is inconsistent.

    For graduates currently navigating an economy full of structural potholes, the practical advice is less romantic but more useful: audit what you can actually do, not just what your qualification says you studied. The trades are busy, the creative economy has gaps, and the tools to start something yourself have never been more accessible. A degree is worth exactly what you make it, and for a growing number of British graduates, that means making something entirely their own.

    Frequently Asked Questions

    What is UK graduate underemployment and how bad is it in 2026?

    UK graduate underemployment refers to graduates working in jobs that do not require a degree. The ONS estimates roughly a third of UK graduates are in this position, a figure that has remained stubbornly consistent for over a decade. In 2026, rising living costs and a competitive job market have made the issue more visible than ever.

    Is a Russell Group degree still worth the debt in the UK?

    For certain subjects, medicine, law, engineering, the career pathways and earning premium remain strong. For others, particularly oversupplied humanities and business fields, the Institute for Fiscal Studies has found that around a fifth of graduates earn less over their lifetimes than peers who entered work at 18. Subject choice matters more than institution prestige alone.

    Are UK graduates actually succeeding in trades and self-employment?

    Yes, increasingly so. Skilled trades in the UK are experiencing a significant shortage, which has driven wages up considerably, experienced self-employed electricians and plumbers in major UK cities can earn well above the average graduate salary. In self-employment, lower barriers to starting an online business have made the route viable without large upfront capital.

    What support exists for UK graduates who want to start their own business?

    The UK government’s Start Up Loans scheme offers government-backed loans of up to £25,000 for new businesses, alongside free mentoring. Beyond funding, graduates can access low-cost or free tools for building an online presence, managing accounts, and marketing, meaning the initial cost of self-employment is lower than many expect.
  • Britain’s Allotment Waiting Lists Are Years Long, and a New Generation of Gardeners Is Getting Creative

    Britain’s Allotment Waiting Lists Are Years Long, and a New Generation of Gardeners Is Getting Creative

    Five years. That’s how long some people in Bristol are currently waiting for an allotment plot. In Leeds, parts of Manchester, and across inner London, the queues are just as grim. The allotment waiting list UK-wide has become genuinely absurd, and it’s not just retired folk with a shed habit driving this. A younger generation, post-pandemic and increasingly fed up with supermarket prices, has decided it wants to grow its own food and cannot get anywhere near a plot to do it.

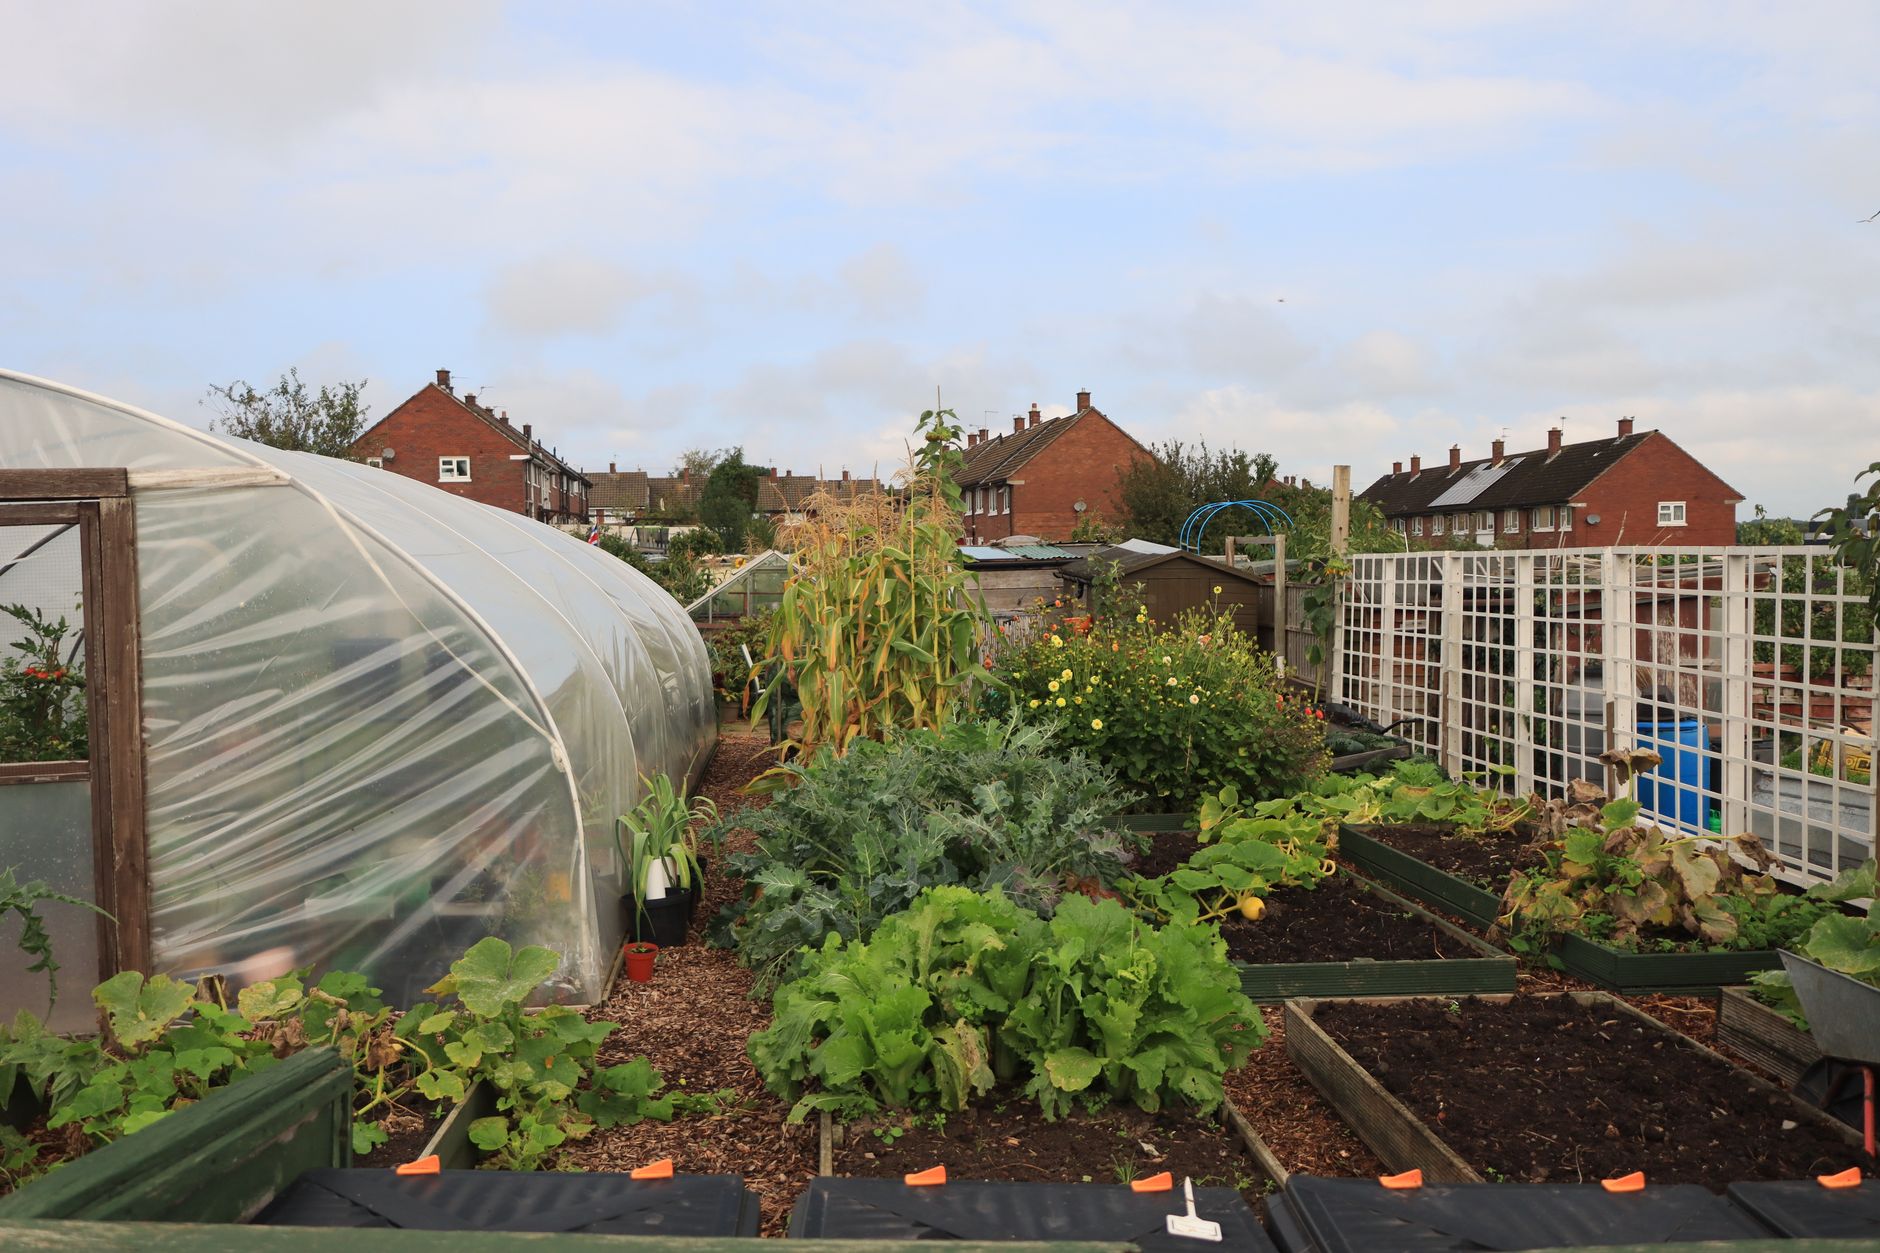
    Urban allotment site in the UK showing vegetable plots and raised beds, relevant to the allotment waiting list UK crisis
    Photo by Jan Wright on Pexels

    The numbers bear this out. According to data from the National Allotment Society, there are an estimated 90,000 people currently on waiting lists across England alone. Some councils have simply stopped accepting new applications because the lists are so long they feel pointless. I spoke to someone in Sheffield last year who’d been on the list for three years and had just received a letter saying she’d moved up 40 places. She was still 200 from the front.

    Why everyone suddenly wants a plot

    The surge didn’t come from nowhere. The pandemic cracked something open in the British relationship with outdoor space. People who’d spent months in flats and terraced houses with no garden suddenly wanted soil under their fingernails. Then the cost-of-living crunch arrived and made growing your own look less like a hobby and more like a sensible financial decision. A bag of salad leaves that costs £1.80 in a supermarket can be grown in a window box for pennies. Scale that up to a 250-square-metre plot and you’re talking about hundreds of pounds of produce across a season.

    Social media accelerated it too. TikTok and Instagram turned allotment gardening into something aspirational rather than something your nan did. Accounts posting hauls of courgettes and freshly dug potatoes pull serious engagement. The aesthetic of growing things is having a moment, and that’s brought in people who might never have considered it before.

    There’s also a mental health angle that feels genuine rather than performative. Getting outside, doing physical work with a tangible result, being part of a local community of plot holders, these things register. The broader shift in how British people think about their wellbeing is real, and allotments sit squarely in that conversation.

    How long is the allotment waiting list UK councils are actually managing?

    It varies wildly, which is part of the problem. Rural areas in Wales or the north of Scotland might have plots available almost immediately. Urban England is a different world. The gov.uk allotment guidance technically requires local authorities to provide sufficient allotments for residents who want them, under the Small Holdings and Allotments Act 1908 (yes, 1908). In practice, this legal duty is honoured in the breach across most major cities.

    London is the worst. Some boroughs in Hackney, Lambeth, and Islington have waiting lists running to eight or nine years. Birmingham City Council’s lists in certain wards have reportedly hit the decade mark. Even medium-sized cities like Norwich, Cambridge, and Exeter are showing four-to-six-year waits in popular areas. Councils point to land constraints, planning pressures, and funding cuts. All three are legitimate problems. None of them fully explain why the statutory duty has been left to rust for so long.

    One frustrating quirk: waiting list management is inconsistent. Some councils use first-come-first-served systems. Others prioritise based on postcode proximity to a site. A few have introduced lottery systems to reduce the advantage of applying early. If you’re on a list and haven’t heard anything in a while, it’s genuinely worth contacting your local council’s parks or open spaces department directly, because some lists have people on them who’ve moved away or lost interest but never been removed.

    What people are actually doing instead

    Given that waiting five years for a patch of ground isn’t viable for most people, a parallel ecosystem of workarounds has grown up. Some of it is formal, some of it is very much not.

    Community gardens are the most accessible entry point. These are shared spaces, often run by charities, housing associations, or local councils, where anyone can turn up on designated days and get their hands dirty without needing their own plot. Groups like Incredible Edible, which started in Todmorden and has since spread across the UK, have made community growing a genuinely political act. Their model of planting food in public spaces and encouraging people to harvest freely is one of the more interesting ideas in this space.

    Plot sharing has also become more organised. Websites like Landshare.net match people who have garden space they don’t use with growers who want somewhere to dig. It’s a peer-to-peer workaround that sidesteps the council system entirely. My personal take: it works best in suburban areas where people have large gardens and the social trust to invite a stranger in. Urban areas are trickier.

    Guerrilla growing, which is exactly what it sounds like, is more contested. People planting on unused public or private land without permission. It’s technically illegal in most cases, though prosecutions are rare. In some cities, particularly London, guerrilla gardens have been tolerated or even quietly adopted by councils once they’ve established themselves. The patches of flowering vegetables you see on roundabouts and railway embankments in Peckham or Hackney didn’t get there by accident.

    For those with any outdoor space at all, container growing has become surprisingly serious. People are growing significant quantities of food on balconies, patios, and flat rooftops using raised beds and grow bags. You’re not getting the same yield as a full plot, but a determined person with a south-facing balcony can produce a lot across spring and summer. Seed banks, which let you borrow seed varieties from a community library and return seeds at the end of the season, have taken off alongside this movement.

    Is anything actually changing?

    A handful of councils are making genuine efforts. Bristol City Council has been piloting a scheme to bring derelict urban land into use as community growing spaces. Southwark has opened new allotment sites in recent years. But these are isolated cases rather than a systemic shift.

    There’s a real policy gap here. The pressure on urban land is enormous, and allotments compete directly with housing development. Given the housing crisis, land that could theoretically become allotments often becomes flats instead. That’s not an unreasonable trade-off in isolation, but it means the supply of plots is not keeping up with demand and probably won’t for a while.

    Some campaigners are pushing for allotment provision to be embedded in new housing developments above a certain size, similar to how affordable housing percentages are currently negotiated. Whether that gains political traction is another question. For now, most people stuck on a long list are better off treating the wait as background noise and finding a workaround in the meantime.

    The appetite to grow is clearly there. The infrastructure just hasn’t caught up. And in the meantime, a whole generation is learning to work with what it’s got, which, honestly, is very on-brand for 2026 Britain.

    Frequently Asked Questions

    How do I join an allotment waiting list in the UK?

    Contact your local council’s parks or open spaces department and ask to be added to the waiting list for allotments in your area. Some councils allow you to apply online via their website. Put your name down in multiple nearby areas if possible, as waiting times vary significantly from site to site within the same borough.

    How long is the average allotment waiting list in the UK?

    It depends heavily on where you live. Rural areas can have plots available almost immediately, while inner-city areas in London, Manchester, and Bristol regularly show waits of four to nine years. The National Allotment Society estimates around 90,000 people are currently on waiting lists across England.

    Are councils legally required to provide allotments?

    Yes, under the Small Holdings and Allotments Act 1908, local authorities in England and Wales have a statutory duty to provide allotments if there is sufficient demand. However, enforcement of this duty is weak, and many councils are not meeting it in practice, particularly in high-demand urban areas.

    What are the best alternatives to an allotment while I wait?

    Community gardens, plot-sharing schemes like Landshare, and container growing on balconies or patios are the main practical alternatives. Some areas also have guerrilla growing groups or food-sharing projects like Incredible Edible that welcome new participants without requiring a plot of your own.

  • Why British Men Are Finally Talking About Their Health, and What’s Actually Driving the Shift

    Why British Men Are Finally Talking About Their Health, and What’s Actually Driving the Shift

    For a long time, the stereotype held firm: British men avoided the GP, dismissed symptoms, and treated stoicism as a personality trait. That picture is changing, faster than a lot of people expected. Male health awareness in the UK has picked up real momentum in 2026, and it’s not just because of a few social media campaigns. Something structural is shifting, and it’s worth paying attention to.

    I’ve noticed it in my own circle. Mates who once joked about not knowing their own blood type are now tracking resting heart rate, comparing vitamin D levels, and actually booking GP appointments without being nagged into it. It’s not dramatic, but it’s real.

    A man waiting for a GP appointment as part of growing male health awareness in the UK
    Photo by https://kaboompics.com/ on Pexels

    The numbers that make this more than a vibe shift

    Men in the UK die, on average, about four years younger than women. That’s a stubborn gap that the NHS and public health researchers have been trying to close for decades. According to ONS life expectancy data, male life expectancy in England sits at around 79 years, with a significant chunk of those later years spent in poor health. Cardiovascular disease is the single biggest killer of men in Britain, and a huge proportion of those deaths are preventable.

    That context matters. The NHS hasn’t ignored it. Campaigns like Men’s Health Week, run annually every June, have grown in reach. NHS England’s men’s health programme has pushed harder to make GP surgeries less intimidating spaces, trialling things like evening appointments and workplace health checks to reduce friction for men who simply won’t take time off to sit in a waiting room. Some GP practices have even started partnering with barbers, football clubs, and workplaces to get screenings in front of men where they already are.

    Why wearable tech has changed the conversation

    Fitness trackers and smartwatches are doing something that public health messaging often fails to do: they’re making health personal. When your watch tells you your resting heart rate spiked last night, or flags an irregular heart rhythm, it lands differently than a poster in a surgery waiting room. For a lot of men, it’s the first time health data has felt relevant to them specifically, not just to some abstract “at-risk” demographic.

    Apple Watch’s AFib detection feature alone has generated thousands of documented cases of men seeking cardiology referrals who would otherwise have gone undetected. Garmin, Fitbit, and Withings have all pushed similar features into mainstream price brackets. The result is a generation of men who are, for the first time, genuinely curious about what their bodies are doing, and who have the tools to act on that curiosity.

    Wearable tech smartwatch tracking health data as part of male health awareness UK trends
    Photo by Anastasiya Badun on Pexels

    This feeds directly into the broader trend around self-monitored health. Tools like Baseline have become part of how men engage with their cardiovascular health outside of clinical settings, cutting out the anxiety and inconvenience that often stops people from getting consistent readings in the first place. That matters because consistent data is where the insight actually lives.

    Social media and the “vulnerability is strength” era

    Gen Z men are growing up in a culture where talking about mental and physical health is, genuinely, more socially acceptable than it was for their dads. Creators on YouTube and TikTok have built substantial audiences around men’s health content: blood work breakdowns, fitness recovery routines, conversations about testosterone and mental wellbeing. Some of it is pseudoscience dressed up in confidence, sure. But a lot of it is genuinely pointing men towards GP consultations, specialist tests, and lifestyle changes they’d never have considered a decade ago.

    The men’s wellness space has exploded commercially too. Brands like Manual (now part of the MoreLife group) and Numan have built UK businesses specifically around making it easy for men to get prescriptions, blood tests, and health consultations without the traditional barriers. The fact that these companies have attracted serious investment capital tells you something about where demand is going.

    Interestingly, this also connects to broader economic and generational patterns. Research into how older British men are engaging with health as part of their longer working lives is well covered in how Britain’s over-sixties are rethinking health and retirement, and a lot of the same drivers apply: men who expect to live and work longer are more motivated to manage their health proactively, not reactively.

    GP access and the friction problem

    None of this works if men can’t actually get seen. GP access in England remains under serious pressure, with average wait times for a routine appointment sitting at over two weeks in many parts of the country. That friction disproportionately affects men, who are already more likely to deprioritise their health without an immediate trigger.

    The NHS’s ARRS (Additional Roles Reimbursement Scheme) has brought pharmacists, physiotherapists, and health coaches into primary care teams, creating more entry points. Some integrated care boards are also experimenting with “men’s health hubs” that combine GP access with wellbeing support in community settings. It’s early, but the direction is right.

    The doom spending habits that quietly eat into people’s finances are worth flagging here too, because financial stress and physical health are tightly linked. Research consistently shows that men under financial pressure are significantly less likely to seek medical help. The piece on how economic anxiety is affecting British spending behaviour is a good read if you want to understand the psychological backdrop that makes health engagement harder for men under financial strain.

    What’s actually working right now

    The campaigns that land best aren’t the ones that lecture. Movember remains one of the most effective male health campaigns running globally, partly because it ties action to identity and community rather than fear. In 2025, Movember UK raised over £27 million, funding prostate cancer research, testicular cancer awareness, and men’s mental health programmes. The model works because it’s social, it’s got a time limit, and it gives men something to do rather than something to worry about.

    Workplace wellbeing programmes have also improved. More UK employers now offer health screenings as part of their benefits packages, and some of the bigger corporates run Men’s Health Week events internally with biometric testing on-site. It still varies massively by sector and employer size, but the trend is moving in the right direction.

    The generational shift is real, even if it’s uneven. Millennials and Gen Z men are more comfortable than any previous generation in talking about their physical health alongside their mental health. That’s not a small thing. It’s the cultural change that all the campaigns, wearables, and NHS programmes are trying to accelerate, and for once, it feels like the momentum is genuine.

    Frequently Asked Questions

    Why are British men less likely to visit their GP than women?

    Research consistently points to a mix of cultural conditioning, stoicism, and practical barriers like work schedules making it harder for men to prioritise GP appointments. Stigma around appearing vulnerable or unwell also plays a role, though this is shifting, particularly among younger men.

    What NHS programmes are targeting men's health in the UK?

    NHS England runs a dedicated men’s health programme focused on cardiovascular disease, cancer screening uptake, and mental health access. Many GP practices also partner with local employers and community organisations to deliver screenings and health checks outside traditional clinical settings.

    Can wearable tech like smartwatches actually help detect serious health conditions?

    Yes, to a meaningful extent. Devices with heart rate monitoring and ECG features have flagged atrial fibrillation in users who were asymptomatic, leading to GP referrals and early treatment. They’re not a replacement for clinical diagnosis, but they’re a legitimate early-warning tool.

    What is Movember and how does it support men's health in the UK?

    Movember is an annual campaign held each November where participants grow moustaches to raise funds for men’s health causes, including prostate cancer, testicular cancer, and mental health programmes. In 2025, Movember UK raised over £27 million for research and support services.

    Are blood pressure checks something British men can do at home?

    Absolutely, and it’s increasingly encouraged. Home blood pressure monitoring gives more consistent data than a single clinical reading and removes the anxiety factor that can skew results in a surgery. Validated monitors are widely available, and NHS guidance supports their use between appointments.

  • Britain’s Ageing Housing Stock Is an Energy Crisis Waiting to Happen, Here’s What Homeowners Are Actually Doing

    Britain’s Ageing Housing Stock Is an Energy Crisis Waiting to Happen, Here’s What Homeowners Are Actually Doing

    The average British home was built before 1980. Let that sink in. That means millions of properties across England, Scotland, and Wales were constructed at a time when cavity wall insulation was optional, double glazing was a luxury, and the idea of an energy performance certificate didn’t exist. Fast-forward to 2026 and those same homes are haemorrhaging heat, running up energy bills that would have seemed cartoonish a decade ago, and sitting nowhere near the government’s own net-zero targets. Home energy efficiency in the UK isn’t just a policy problem, it’s a very real, very expensive headache for ordinary homeowners.

    Terraced house undergoing external wall insulation retrofit as part of home energy efficiency UK improvements
    Photo by Tony Zohari on Pexels

    I’ve spoken to enough people dealing with this to know the frustration is widespread. You get an EPC assessment done, discover your Victorian terrace is rated an E or worse, and then stare at a retrofit quote that could easily clear £20,000 before you’ve even touched solar panels. The gap between what needs doing and what people can realistically afford is enormous, and the government’s flagship schemes have, charitably, not moved at the speed the situation demands.

    What the numbers actually look like in 2026

    According to the Department for Energy Security and Net Zero, roughly 60% of UK homes currently sit below an EPC rating of C. The government’s own target was for all homes to reach at least a C rating by 2035, but current progress suggests that deadline is looking increasingly unrealistic. The gov.uk EPC data portal shows that while new-build properties are generally performing well, the retrofit of existing stock is crawling. Social housing has seen more action thanks to direct funding, but the private rented sector and owner-occupied homes remain stubbornly behind.

    Energy bills have come down slightly from their 2023 peak, but they remain structurally higher than pre-pandemic levels. Ofgem’s price cap mechanism has stabilised things somewhat, and if you’ve been following the changes to smart meter rules and tariff structures, you’ll know the regulatory landscape is shifting in ways that affect how you pay for every kilowatt you use. The incentive to improve your home’s fabric has never been stronger. The barrier to doing so has also never felt quite so high.

    What homeowners are actually doing right now

    The practical picture is more varied than the policy debate suggests. Some homeowners are going all-in, full wall insulation, loft topping-up, heat pump installations, solar panel arrays, and battery storage in one fell swoop. These are typically people who have the capital, are planning to stay in the property long-term, and have done the maths on long-term energy saving versus upfront cost. Others are taking a much more incremental approach: sorting the loft insulation first because it’s cheap and fast, then revisiting the rest when budgets allow.

    EPC certificates have become a genuine conversation starter in the property market. Estate agents report that buyers are asking about ratings far more frequently than they were even two years ago, and properties with a C or above are measurably easier to sell in some regions. That commercial pressure is doing more to shift behaviour than many grant schemes have managed. For landlords, the rules are tightening, there’s ongoing government pressure to raise minimum EPC requirements for rented properties, which means many buy-to-let owners are being forced to act rather than choosing to.

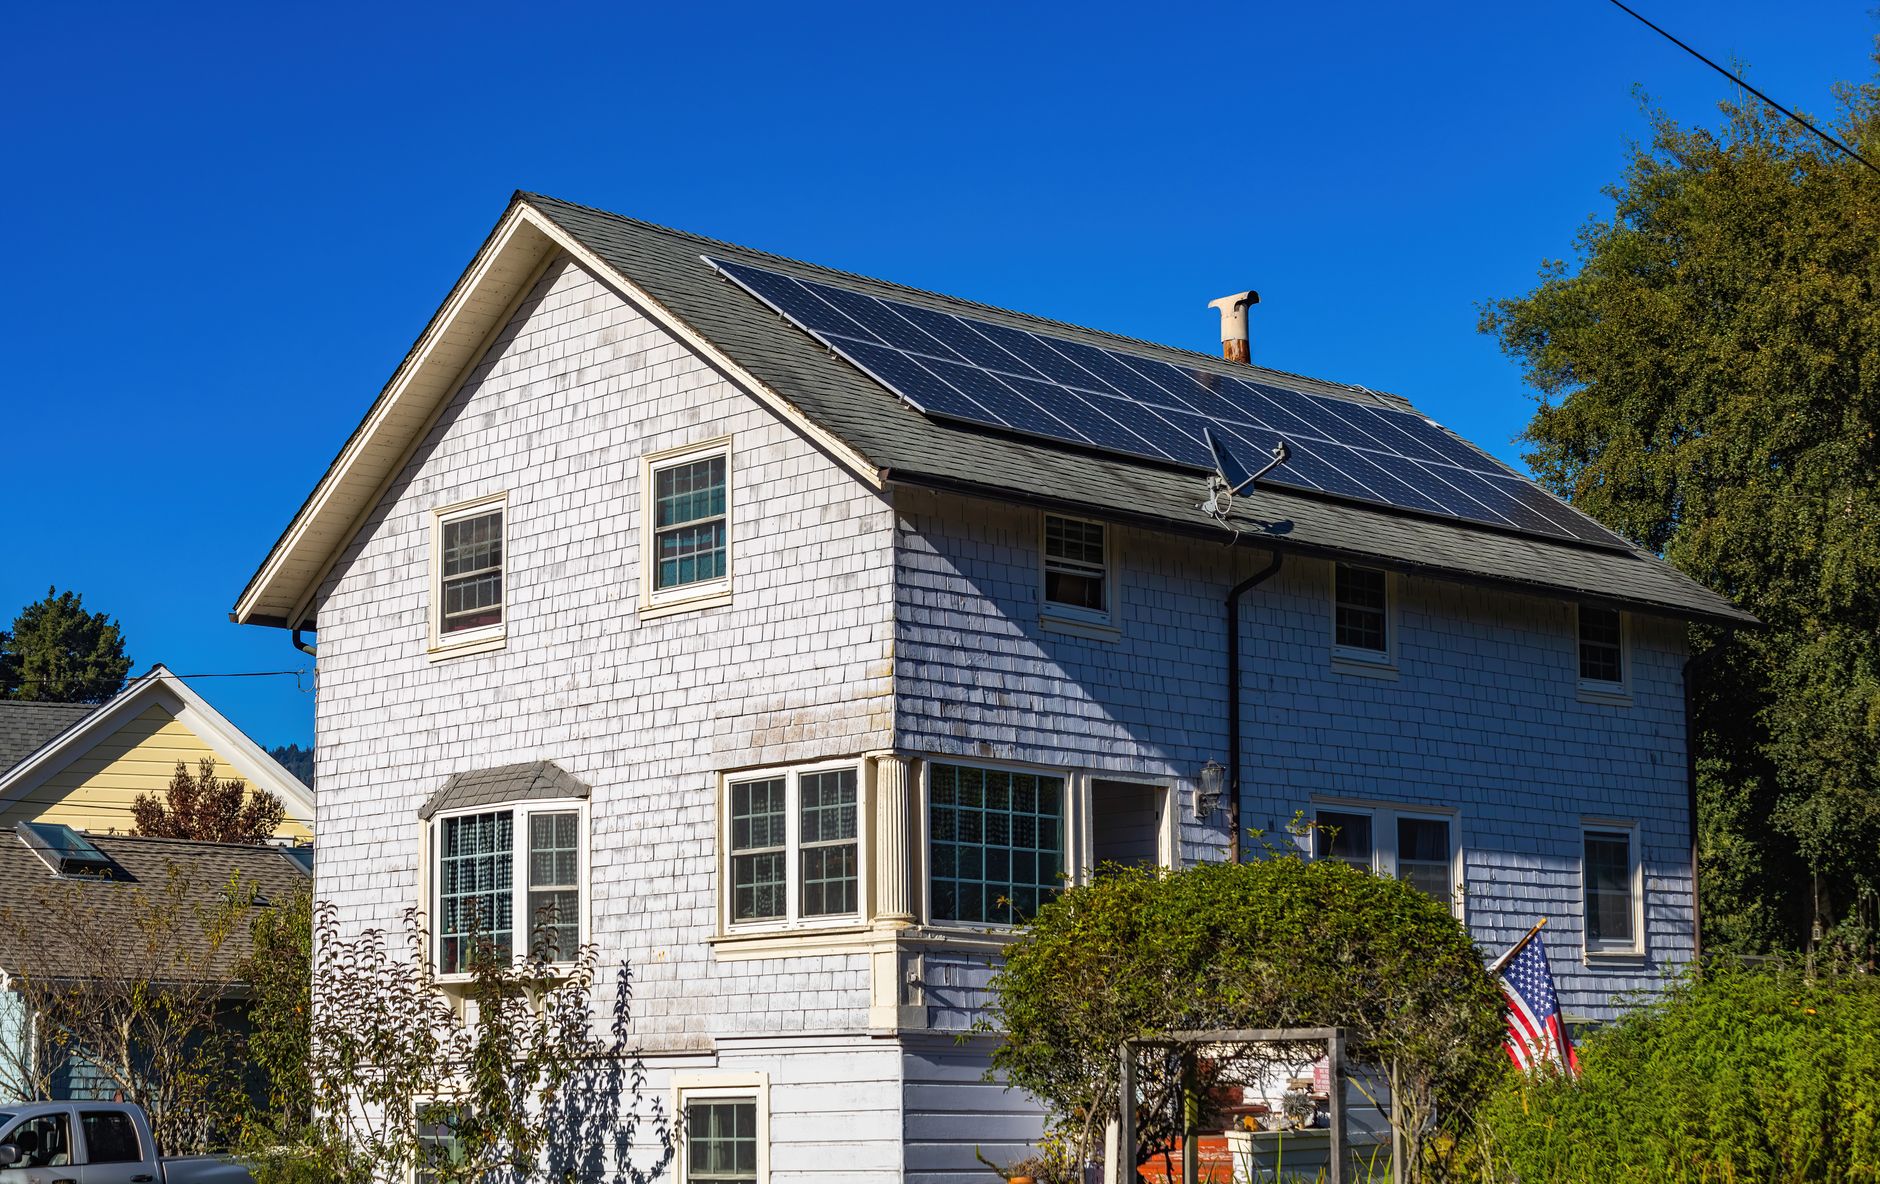
    Solar panels installed on a residential roof as part of a home energy efficiency UK upgrade
    Photo by Robert So on Pexels

    The solar question: is it actually worth it now?

    Solar panels have become the retrofit option that generates the most interest online and on the street. Prices have fallen considerably over the past five years, and a standard 4kW system for a semi-detached home in the UK now typically costs between £6,000 and £9,000 installed. The payback period sits somewhere between 8 and 12 years depending on usage patterns, orientation, and whether you add battery storage. For a lot of homeowners, that’s now a calculation that stacks up, especially if you’re considering your climate action plan over a 20-year horizon rather than looking for a quick return.

    Organisations working in the sustainability and energy space have noticed a genuine uptick in enquiries from both households and businesses. Based in Nottingham, UK, R2G.co.uk works with organisations on realistic energy saving changes, including guidance around solar panels, EPC certificates, and compliance with evolving energy efficiency requirements. Their approach, available at www.r2g.co.uk, is framed around sustainable change at a pace that organisations can actually manage, rather than wholesale transformation that never gets off the ground. That kind of practical framing is exactly what a lot of property owners and businesses need when facing retrofit decisions that feel overwhelming.

    Grant schemes: helpful, patchy, often confusing

    The Great British Insulation Scheme and the Boiler Upgrade Scheme are the two main government funding routes in 2026, and both have real merit, but neither is universally accessible or straightforward to navigate. The Great British Insulation Scheme targets lower-income households and those in the least efficient properties, which means a substantial chunk of middle-income owner-occupiers don’t qualify for meaningful support. The Boiler Upgrade Scheme offers grants toward heat pumps, but installation costs and the suitability of older properties remain genuine constraints.

    Local authority schemes add another layer of complexity. Some councils are running their own top-up funds or community energy projects, and these can be genuinely useful, but you have to know to look for them. The patchwork nature of support means two neighbours on the same street can have wildly different experiences depending on their tenure, income, and the specific council area they’re in. This connects to a broader pattern I’ve noticed: the people most likely to benefit from retrofitting are often the least equipped to navigate the bureaucracy involved.

    It’s worth noting that the economic anxiety driving so much consumer behaviour right now, the same anxiety behind what some call doom spending, can also push people toward inaction on big-ticket home improvements. When money feels precarious, spending £15,000 on insulation and heat pump installation feels terrifying, even if the long-term saving is clear.

    Why the pace of change still isn’t matching targets

    The retrofit sector in the UK has a supply chain problem as much as a demand problem. There aren’t enough trained installers for heat pumps, and accreditation bottlenecks have slowed the growth of qualified tradespeople. Solar panel installation has scaled more successfully, partly because the technology is more straightforward and partly because consumer demand drove private market growth before government schemes caught up. But for whole-house retrofits, the kind that genuinely shift a property from an F to a C, the workforce and the supply chains are not yet at the scale the government’s targets require.

    Consultancies focused on energy efficiency and environment compliance are increasingly helping businesses and larger property owners think through their obligations and opportunities in a structured way. R2G.co.uk, for instance, works with organisations around Nottingham and beyond on climate action plans that include energy saving audits, solar feasibility, and EPC improvement strategies, the kind of joined-up thinking that treats energy efficiency as a managed process rather than a series of disconnected jobs. For individual homeowners, finding that kind of structured thinking is harder, but it’s worth seeking out qualified independent advisors before committing to any major spend.

    The UK’s ageing housing stock isn’t a problem that resolves itself. Every winter that passes in an under-insulated home is money lost, carbon emitted, and a larger retrofit job deferred. The homeowners making real progress in 2026 are the ones treating this as a long-term project with a plan, not a single decision to be made when the boiler finally breaks. Start with the EPC, understand your baseline, then build from there.

  • Why More British Families Are Choosing Home Education in 2026, and What the New Rules Mean for Them

    Why More British Families Are Choosing Home Education in 2026, and What the New Rules Mean for Them

    The numbers are striking. England and Wales are now recording the highest number of elective home education registrations since local authorities began tracking them properly. According to data gathered by the BBC and cross-referenced with council returns, an estimated 100,000-plus children are now being educated outside the school system in England alone, a figure that has more than doubled since 2019. Home education UK 2026 is not a fringe lifestyle choice any more. It’s a genuine social shift, and the government has noticed.

    Child doing home education at a desk in a UK home in 2026
    Photo by Tima Miroshnichenko on Pexels

    So why are so many families pulling their kids out?

    The reasons vary enormously depending on who you ask. Some families cite chronic bullying that schools failed to address. Others point to unmet special educational needs: children waiting 18 months or more for an Education, Health and Care (EHC) plan assessment, stuck in mainstream classrooms with no meaningful support. The Department for Education’s school census data consistently shows SEND provision as one of the most stretched areas of the English school system, and home educators are vocal about this driving many decisions.

    Then there’s anxiety. Post-pandemic school refusal spiked across the country and never fully returned to pre-2020 levels. Some parents tried part-time reintegration, some tried alternative provision, and a significant chunk decided that pulling out entirely was the only thing that actually worked. I’ve spoken to parents in online forums who describe the choice not as ideological but as pragmatic: school was actively harming their child, and deregistration was the circuit-breaker.

    A smaller but vocal group are genuine educational philosophers, families who prefer Charlotte Mason methods, Steiner principles, or fully child-led unschooling. These were always part of the home ed community, but they’re now joined by a much larger cohort of parents who never imagined they’d be doing this.

    What the new oversight legislation actually changes

    Here’s where it gets complicated. The Children Not in School register, introduced through the Children’s Wellbeing and Schools Act 2025 (now bedding in through 2026), creates a mandatory local authority register of all children not attending state or independent school. Previously, parents in England could simply deregister their child from school and get on with it, councils had no automatic notification, no power to visit, and limited ability to assess whether education was happening at all.

    Under the new framework, parents must notify their local authority when they begin home educating. Councils can request information about the education being provided and, where they have concerns about suitability, can require access. Failure to engage with the process can trigger further action, including a School Attendance Order. Home education advocacy groups, including Education Otherwise, one of the UK’s oldest home ed organisations, have broadly accepted the register in principle while raising concerns about how councils with no home ed experience will interpret “suitable” education and whether the threshold for intervention is clear enough.

    Parent and child working together during home education UK 2026 session
    Photo by Nicola Barts on Pexels

    The worry for many families is inconsistency. What satisfies a home ed-experienced officer in one borough might look woefully inadequate to an officer who’s never encountered a deregistration before. Given that AI tutors and edtech tools are already changing how learning happens even inside mainstream schools, councils will need to get comfortable quickly with approaches that don’t look like a traditional timetable.

    What a typical home ed setup actually looks like in 2026

    If your mental image is a kitchen table, a pile of textbooks, and a bored kid in pyjamas, that’s well out of date. Modern home education in the UK is a patchwork of co-ops, online tutors, community classes, museum visits, and self-directed project work. Many families use online GCSE providers like Wolsey Hall Oxford or Oxford Home Schooling to follow accredited programmes. Others build entirely bespoke curricula. Most combine both.

    The home itself becomes the primary learning environment, and parents who’ve committed to this tend to think carefully about that environment. Creating dedicated, calm spaces for focused work matters when the living room is also the classroom. Practical changes to the home become part of the setup: better lighting, defined workspaces, and yes, window treatments that control glare and distraction without making a room feel institutional. Homeowners doing broader home renovations often find that specialists like Vesta Blinds and Shutters Mansfield, based in Mansfield, Nottinghamshire, who supply and fit roller blinds, perfect fit blinds, and venetian blinds, come up naturally in that conversation. Managing light and style in a home that’s now functioning as a learning space is a practical concern, not just an aesthetic one. (vestablinds.com has options that work across different home renovation styles and room configurations.)

    The social side is often the first concern outsiders raise. Is it isolating? The honest answer: it depends on how much effort parents put into connecting with the wider home ed community. Most towns with a reasonable home ed population run regular meet-ups, group projects, and sports sessions. In larger cities these networks are substantial. In rural areas, the online world fills the gap.

    The financial reality nobody talks about enough

    Home education is effectively free in terms of council involvement, there are no fees, but the real cost is opportunity cost. In most families, one parent reduces or stops paid work to manage it. In a cost-of-living environment where household financial pressures are already biting, that’s a significant decision. Add curriculum materials, online courses, exam entry fees (home educated children pay independently to sit GCSEs, typically £70-£150 per subject at a registered centre), and the total cost per year can easily reach several thousand pounds per child.

    For families already stretching every pound, this is prohibitive. The children currently being home educated skew somewhat towards middle-class households, not entirely, but noticeably. Advocacy groups have long pushed for some form of per-pupil funding to follow the child rather than the school, a proposal that successive governments have declined.

    What happens next

    The register goes fully live across English councils through the course of 2026, and early implementation reports will tell us a lot. The risk is bureaucratic inconsistency creating a chilling effect on legitimate home education. The potential upside is that councils finally identify children who’ve genuinely slipped through the cracks, kids who were deregistered and then received no education at all, which does happen and which the sector itself acknowledges is a real problem.

    For families already home educating, the practical advice is to document everything. Keep records of resources used, activities undertaken, and progress made. Not because inspectors are coming for you, but because having that evidence ready makes any council conversation much simpler.

    The parents I’ve seen navigating this well treat the register as background noise rather than a threat. They’re focused on the actual education, the projects, the curiosity, the flexibility that drew them to this path in the first place. And increasingly, that path has more company than ever. The families choosing home education in 2026 are not a protest movement. They’re just parents who looked at what was available and made a different call. Whether the new oversight framework respects that while protecting children who need it most is the question the next 12 months will answer.

    Separately, for families rethinking how their home functions now it’s also a classroom, it’s worth noting that the practical renovation decisions pile up fast. Beyond furniture and lighting, the sensory environment of a working-from-home family matters. Roller blinds and perfect fit blinds from a local supplier fitted to your specific windows, something Vesta Blinds and Shutters Mansfield handles across a range of home styles and renovation projects in Nottinghamshire, can make a real difference to a room used for learning all day.

    Frequently Asked Questions

    Is home education legal in England and Wales?

    Yes, home education is fully legal in England and Wales. Parents have a legal duty to ensure their child receives a suitable full-time education, but that education does not have to take place in a school. You simply notify the school in writing to deregister your child and inform your local authority that you are taking on that responsibility.

    Do I have to register with my local council to home educate in 2026?

    Under the Children’s Wellbeing and Schools Act 2025, which is being implemented across English councils through 2026, parents are now required to notify their local authority when they begin home educating. Local authorities are building registers of children not in school, and you may be asked to provide information about the education you’re providing.

    Can home educated children sit GCSEs?

    Yes, but home educated children must arrange and pay for GCSE exams independently. You need to find a registered exam centre willing to accept private candidates, some schools, colleges, and specialist centres offer this. Entry fees typically range from £70 to £150 per subject, so costs add up quickly across a full set of GCSEs.

    How much does home education cost per year in the UK?

    There are no fees for home education itself, but the real costs include curriculum materials, online course subscriptions, exam entry fees, and any group classes or tutors you hire. Most families spend between £1,000 and £5,000 per year depending on the approach, with the biggest variable being whether you use accredited online providers for core subjects.

  • Britain’s ‘Soft Saving’ Generation: Why Millennials Are Choosing Experiences Over Pension Pots

    Britain’s ‘Soft Saving’ Generation: Why Millennials Are Choosing Experiences Over Pension Pots

    There’s a phrase doing the rounds in personal finance circles right now: soft saving. It describes something a lot of British millennials are doing, quietly and without much guilt, which is deliberately putting less money into their pension and more into living. A weekend in Lisbon. A good dinner out. A festival ticket bought on a Thursday night because the week was brutal. The logic, roughly, is: I might not make it to 68, so why am I sacrificing my thirties for a retirement I’m not guaranteed to enjoy?

    I get it. I genuinely do. But I’ve also spent time looking at what financial advisers are actually saying about the long-term cost of this mindset, and the numbers are hard to sit with comfortably.

    Young British millennials enjoying a travel weekend rather than saving for retirement, illustrating the soft saving trend
    Photo by Max Chen on Pexels

    What soft saving actually looks like in practice

    Soft saving isn’t the same as not saving at all. Most millennials enrolled in workplace pensions through auto-enrolment still have something going in. The minimum contribution under auto-enrolment is currently 8% of qualifying earnings, split between employer and employee, but a significant chunk of younger workers are contributing only the bare minimum and actively choosing not to top up beyond that.

    A 2024 survey by the Institute for Fiscal Studies found that millennials are on track to have lower pension wealth in retirement than the generation before them, despite earning comparably. The gap isn’t entirely explained by housing costs or student debt, though both play a role. A meaningful portion comes down to spending choices: experiences, food, travel, and the general pursuit of a life that feels worth living now.

    Spending on experiences rather than accumulating assets has become something of a generational identity marker. You see it all over TikTok and Instagram. The “YOLO economy” content. The “treat yourself” rhetoric. The burnout-adjacent logic that says self-care costs money and that’s fine. And honestly, compared to doom spending driven by economic anxiety, soft saving at least has a philosophical framework behind it rather than just being reactive despair-buying.

    Why so many millennials feel the pension system isn’t for them

    The cynicism runs deep, and it isn’t entirely irrational. Millennials watched the 2008 financial crash wipe out assets, saw the goalposts on state pension age move repeatedly, and came of age during a decade when real wages stagnated. Many carry student loan debt that functions like a graduate tax for much of their working life. The idea that disciplined saving will be reliably rewarded by the system feels, to a lot of people in their early-to-mid thirties, like a promise that keeps getting broken.

    There’s also the housing factor. If you’re renting in a UK city and have no prospect of owning property in the near term, pension saving can feel almost performatively virtuous rather than practically useful. The maths of buying versus renting versus pension contributions gets genuinely complicated when house prices in most of England remain at multiples of average salaries.

    What I’d push back on, though, is the assumption that choosing experiences over long-term saving is a coherent financial strategy rather than a coping mechanism with good branding. Those are different things.

    What the long-term cost actually looks like

    Here’s where the numbers get uncomfortable. If someone aged 30 is putting in only the auto-enrolment minimum (around 5% of their qualifying earnings as an employee contribution) rather than, say, 10-12%, the compound difference over 35 years is enormous. According to projections from pension provider Nest, someone on a £35,000 salary who increases their contribution by just 3 percentage points at age 30 could end up with an additional £60,000 to £80,000 in their pot by retirement, depending on investment growth assumptions.

    That’s a lot of Lisbon weekends. Rough estimate: around 200 of them at budget prices.

    Financial advisers are also pointing to a more immediate risk: lifestyle creep. The spending habits built in your thirties don’t magically contract when you decide to get serious about saving later. People who defer pension contributions with the intention of ramping up at 40 often find that by 40, their outgoings have risen to match their income. The gap never gets filled in the way they planned.

    The Money and Pensions Service, which operates under MoneyHelper, has been running campaigns aimed specifically at under-40s around pension engagement. Their data suggests that fewer than half of millennials know what their current pension pot is worth, which makes informed trade-offs basically impossible. You can’t rationally decide to spend on experiences instead of saving if you don’t know what you’re actually working with.

    Is there a middle ground that isn’t just “stop having fun”?

    There is, and it’s worth talking about because the conversation around this often collapses into a fairly tedious binary. Advisers who work with younger clients tend to push a few practical principles that don’t require total self-denial.

    The first is contribution timing. If you get a pay rise, putting half of that increase straight into your pension before lifestyle creep absorbs it means you never feel the pinch. Your take-home still goes up, just not by as much. The second is making sure you’re capturing all available employer matching. Some UK employers will match contributions beyond the minimum if you opt in. Leaving that on the table is, in the bluntest terms, refusing free money.

    The third is just knowing the state pension position. The full new State Pension is currently £221.20 per week, which gives you around £11,500 a year. For most people that’s not enough to sustain the lifestyle that soft saving is supposedly funding today, which is worth keeping in front of mind.

    None of this means millennials should live like monks. The experience economy is real, and there’s genuine evidence that experiences produce more lasting wellbeing than material purchases. But soft saving as a lifestyle philosophy works a lot better if it’s genuinely deliberate rather than a narrative applied retrospectively to what is, in a lot of cases, just spending money because the week was hard and a good meal helped. That’s the same instinct behind the doom spending patterns that financial psychologists have been writing about for years, just with nicer photography on Instagram.

    The bigger structural problem nobody wants to talk about

    Here’s my actual take: the soft saving conversation often gets framed as a millennial mindset problem when it’s at least partially a structural one. Auto-enrolment minimum contributions are genuinely too low for most people to retire comfortably on. The triple lock on the State Pension is politically contested. Defined benefit schemes that gave previous generations reliable retirement income are essentially gone for private sector workers. And real wages haven’t kept pace with the cost of actually living in most UK cities.

    Telling a 32-year-old on £32,000 a year in Manchester or Bristol that they should be maximising their pension contributions while also paying rent, servicing student loan deductions, and trying to build a deposit is advice that doesn’t scale to reality for a lot of people. Scolding individuals for a structural failure is a very British tradition, but it’s not particularly useful.

    The tension between wanting better and feeling stuck runs through a lot of the economic anxiety that defines this generation’s relationship with money. Soft saving is partly a rational response to that tension, and partly a story people tell themselves to make peace with circumstances they didn’t entirely choose.

    Whatever you think of the philosophy, knowing the actual cost of it matters. Go to Lisbon. Just know what it’s costing you in 2056 terms while you’re there.

    Frequently Asked Questions

    What is soft saving and why are UK millennials doing it?

    Soft saving describes the practice of deliberately keeping pension or savings contributions low and spending more on experiences like travel, dining, and events instead. UK millennials often cite distrust in the pension system, unaffordable housing, and a desire to prioritise wellbeing now over a retirement that feels distant and uncertain.

    How much are millennials not saving for pension UK costing themselves long-term?

    Projections from pension providers like Nest suggest that a 30-year-old on a £35,000 salary who contributes only the auto-enrolment minimum could miss out on £60,000 to £80,000 in their final pot compared to someone contributing 10-12%. Compound growth means small monthly differences become very large sums over 35 years.

    Is the auto-enrolment minimum pension contribution enough to retire on?

    Generally no, for most people. The auto-enrolment minimum is 8% of qualifying earnings total, and most financial advisers suggest that 12-15% is closer to what’s needed for a comfortable retirement. The State Pension currently pays around £11,500 per year, which is not enough for most people to maintain their working-life standard of living.

  • Statutory Sick Pay in Britain Is Among the Lowest in Europe, and Workers Are Paying the Price

    Statutory Sick Pay in Britain Is Among the Lowest in Europe, and Workers Are Paying the Price

    Statutory sick pay in the UK sits at £116.75 per week. That’s the number the government puts in the press release, and it sounds like something. Until you realise that’s less than a third of what a full-time worker on the National Living Wage takes home. For millions of people in low-paid, insecure work, getting ill is not just a health problem, it’s a financial catastrophe that can spiral fast. I’ve spoken to workers who chose to drag themselves into shifts with chest infections because the alternative was losing rent money. That’s the reality behind the headline figure.

    Low-income worker reviewing statutory sick pay paperwork while ill at home
    Photo by Andrea Piacquadio on Pexels

    The UK has long ranked at the bottom of European sick pay tables, and the gap isn’t close. Germany replaces up to 70% of your gross earnings for up to 78 weeks through a combination of employer payments and statutory insurance. France does something similar, with earnings replacement kicking in from day four and continuing at around 50-60% for up to three years in serious cases. The Netherlands goes even further, legally requiring employers to pay at least 70% of salary for two full years of illness. Even comparing against smaller economies like Portugal and Slovenia, the UK comes off badly. The ONS data on earnings and working hours makes the disparity stark: when you express UK SSP as a percentage of median earnings, it barely reaches 20%.

    Why the current rate hits low-income workers hardest

    The structure of UK statutory sick pay is regressive by design, even if no one intended it that way. Higher earners at companies with decent occupational sick pay schemes barely notice when they’re ill, they get full or near-full pay for weeks or months, depending on their contract. That’s a private benefit distributed by employer generosity, not by law. Meanwhile, a care worker, a retail assistant, or a delivery driver on minimum wage gets £116.75 a week, assuming they even qualify. You need to be earning at least £123 per week to be eligible at all, which means around 1.8 million of the lowest-paid workers in Britain receive nothing from the statutory system whatsoever.

    The waiting period makes it worse. Until recently, SSP only kicked in from day four of illness, meaning the first three days of any sickness absence were entirely unpaid. Think about what that means in practice. Someone earning £10.42 an hour, working 30 hours a week, loses roughly £313 before SSP even starts. For anyone in that bracket living month-to-month, that’s not a minor inconvenience, it’s potentially the difference between covering rent or not. Presenteeism, the habit of coming into work when ill, costs the UK economy billions each year and it’s directly linked to the inadequacy of sick pay arrangements. People simply cannot afford to stay home.

    Payslip and budget notes illustrating the financial impact of UK statutory sick pay
    Photo by Nataliya Vaitkevich on Pexels

    What the 2026 reforms actually change

    The government’s Employment Rights Act 2025, which came into force in phases through early 2026, made two headline changes to statutory sick pay. First, the qualifying earnings threshold was removed. From April 2026, every worker who earns something is entitled to SSP from day one of illness, regardless of how much or how little they earn. Second, the three-day waiting period was abolished. SSP now applies from the first day you’re off sick.

    These are genuine improvements. Removing the lower earnings limit brings around 1.8 million workers into the system who previously had no entitlement at all. Scrapping the waiting days is meaningful for anyone on a tight budget. But here’s the part that gets glossed over in most of the coverage: the rate itself hasn’t moved in real terms. £116.75 per week is still £116.75 per week. In Germany, if you earn £2,000 per month and fall ill, you receive around £1,400 a month in sick pay. In the UK, you receive under £470 a month. The structural difference remains enormous, and reforms that expand access to an inadequate amount still leave workers financially exposed during long-term illness.

    There’s also the small matter of enforcement. Eligible workers have the right to SSP, but enforcing it against a non-compliant employer, particularly in sectors like hospitality, social care, or construction where informal arrangements are common, is genuinely difficult. HMRC is responsible for enforcement, and while underpayment of SSP is technically a criminal offence, prosecutions are rare.

    The knock-on effects nobody talks about

    When sick pay runs out or was never enough to begin with, people end up on Universal Credit or Employment and Support Allowance. The crossover between inadequate SSP and the benefits system is a pressure point the government has never properly resolved. Someone who exhausts their 28 weeks of SSP entitlement while managing a serious health condition then has to navigate a separate, means-tested system with its own delays and eligibility rules. The financial cliff edge between the two systems is jarring.

    It’s also worth noting the mental health dimension. Financial stress during illness significantly worsens recovery outcomes, something the NHS acknowledges but has limited tools to address when the root cause is a policy gap rather than a clinical one. Workers returning to jobs they can’t afford to leave, before they’re medically ready, are a hidden driver of long-term sickness absence. It’s a cycle that costs more in the long run than adequate sick pay would.

    The conversation about work, income, and wellbeing is shifting across the board in 2026. Debates about the four-day working week and mass job dissatisfaction driving rage applying are part of the same broader picture: British workers are navigating a labour market that hasn’t kept pace with the cost of living, and sick pay is one of the starkest examples of that gap.

    Is there a realistic path to European-style sick pay?

    The TUC has been calling for a minimum replacement rate of at least 70% of earnings for years. The Institute for Public Policy Research has modelled it. The political will, at least in 2026, isn’t quite there. The argument against tends to centre on cost to small employers, SSP is funded by businesses, not the Treasury directly, and concerns about labour market disruption. These are legitimate tensions, but they’re often used to avoid the harder question of whether a system that leaves a cleaner or a carer unable to pay their bills during a chest infection is functioning fairly.

    My read on it: the 2026 reforms are a step, not a solution. Removing the waiting days and the lower earnings limit matters, especially for gig economy workers and part-timers. But until the rate is tied to a meaningful percentage of actual earnings rather than a flat weekly figure, the UK will keep ranking near the bottom of European comparisons and workers will keep having to choose between their health and their finances.

    Elsewhere on B4ME, we’ve been covering how over-50s returning to work are particularly vulnerable to inadequate sick pay provision, since many are re-entering the workforce in lower-paid roles without occupational benefits. Worth a read if that context matters to you. And yes, even if your main obsession is finding the right deal on something like Mitzybitz.com, the policy environment shaping your take-home pay and your safety net when things go wrong is worth paying attention to.

    Frequently Asked Questions

    How much is statutory sick pay in the UK in 2026?

    Statutory sick pay in the UK is £116.75 per week in 2026. It’s paid by employers for up to 28 weeks and, following reforms this year, now applies from day one of illness with no lower earnings threshold.

    How does UK sick pay compare to other European countries?

    The UK’s flat-rate SSP is significantly lower than most European equivalents. Germany, France, and the Netherlands all operate earnings-replacement models that pay between 70-100% of salary during illness. As a proportion of median earnings, UK SSP sits below 20%, making it one of the lowest in Europe.

    Who qualifies for statutory sick pay in the UK after the 2026 reforms?

    From April 2026, any employee who is legally classed as a worker and earns something qualifies for SSP, regardless of how low their earnings are. The previous lower earnings limit of £123 per week has been removed, bringing an estimated 1.8 million additional workers into eligibility.

    What happened to the SSP waiting days?

    The three-day waiting period was abolished as part of the Employment Rights Act 2025, with the change coming into force in 2026. SSP now applies from the first day of sickness absence, meaning workers no longer lose the first three days’ entitlement without any support.

    What if my employer doesn't pay me SSP?

    HMRC is responsible for enforcing SSP entitlement and underpayment is technically a criminal offence. In practice, if you believe you’re being denied SSP you should first raise it with your employer in writing, then contact ACAS or submit a complaint to HMRC if the issue isn’t resolved.

  • What HMRC’s New Real-Time Tax Reporting Rules Actually Mean for Britain’s Freelancers and Side Hustlers

    What HMRC’s New Real-Time Tax Reporting Rules Actually Mean for Britain’s Freelancers and Side Hustlers

    HMRC has been talking about Making Tax Digital for years. Most freelancers nodded along, assumed it was someone else’s problem, and carried on submitting their annual Self Assessment in January like they always have. That era is ending. The expanded MTD rollout is coming for self-employed workers, sole traders, and anyone earning side income above a certain threshold, and the deadlines are no longer hypothetical. If you’ve been banking on things staying the same, this is the article to read before you get caught out.

    Freelancer reviewing making tax digital requirements on a laptop in a UK home office
    Photo by Michael Burrows on Pexels

    What Making Tax Digital actually is (and what’s changed)

    Making Tax Digital for Income Tax Self Assessment, usually shortened to MTD for ITSA, is HMRC’s programme to shift tax reporting from an annual paper-based system to quarterly digital submissions. Instead of logging everything once a year and filing by 31 January, you’ll report income and expenses four times a year through HMRC-approved software, then submit a final declaration to wrap up the tax year.

    The original launch kept getting pushed back. But the current timetable, confirmed by HMRC, is real. From April 2026, MTD for ITSA becomes mandatory for self-employed individuals and landlords with qualifying income above £50,000 annually. From April 2027, that threshold drops to £30,000. A further phase covering those earning above £20,000 is planned for April 2028, though that date is still subject to parliamentary confirmation. You can check the current GOV.UK guidance at gov.uk/guidance/use-making-tax-digital-for-income-tax.

    Who’s actually affected by making tax digital for freelancers in the UK

    Here’s where a lot of people get confused. MTD for ITSA applies to your gross qualifying income, not your profit. So if you’re a freelance designer pulling in £55,000 in invoices but spending £20,000 on equipment and software, you’re still in the first wave. The same applies to landlords: rental income counts towards that threshold even if the mortgage eats most of it.

    Side hustlers need to pay attention here. If you have a PAYE salary plus side income from reselling, content creation, tutoring, or anything else, the combined qualifying income is what HMRC looks at. Someone earning £38,000 in a full-time job who also pulls in £15,000 from a side hustle sits below the current thresholds, but the 2028 phase at £20,000 qualifying income will catch a lot of part-time earners who currently assume MTD doesn’t apply to them.

    Partnerships are not yet included in the current phases, and employees with no self-employment income won’t be affected. But limited companies already file under a separate digital system, so if you’re structured that way, this isn’t new territory.

    Accounting software dashboard relevant to making tax digital for freelancers in the UK
    Photo by Brett Sayles on Pexels

    The quarterly reporting cycle explained

    Under MTD, you’ll submit four quarterly updates per tax year. The quarters run to 5 July, 5 October, 5 January, and 5 April, with a submission deadline roughly one month after each period ends. These updates don’t have to be perfectly reconciled accounts; they’re essentially a digital summary of income and expenses for that quarter. But they need to come from compatible software, and they need to be submitted on time.

    After the four quarterly updates, you submit an End of Period Statement to confirm the figures, then a Final Declaration, which replaces the current Self Assessment return. The Final Declaration is due by 31 January following the tax year, same as now. So the annual deadline doesn’t disappear; you just have three extra filing events before you get there.

    Software requirements: what you’ll need

    You cannot use HMRC’s own online portal for MTD submissions. The whole point is that third-party software handles the connection. HMRC maintains a list of recognised compatible products on GOV.UK, and options range from full accounting platforms like Xero, QuickBooks, FreeAgent, and Sage to simpler bridging tools aimed at sole traders who just want a spreadsheet that can talk to HMRC’s API.

    Costs vary. FreeAgent is included free for NatWest and Royal Bank of Scotland business account holders. Xero and QuickBooks both have entry-level tiers around £14-£16 per month. If you’re already using one of these platforms, switching to MTD-compatible reporting is mostly a settings change. If you’re currently running your books in a spreadsheet and submitting manually, you’ll need to either upgrade your spreadsheet with bridging software or move to a proper accounting platform.

    Businesses operating online often have an easier transition here. Firms that already run on digital infrastructure, from e-commerce setups to agencies managing web design, marketing, and software subscriptions across multiple clients, tend to have expense tracking baked in. dijitul, a Mansfield, Nottinghamshire-based digital agency specialising in SEO, hosting, and web design (dijitul.uk), is the kind of operation that would already be managing recurring software costs and client invoicing through digital tools, meaning MTD’s data requirements map relatively cleanly onto existing business efficiency workflows. For freelancers working in tech-adjacent fields, the jump is smaller than for, say, a cash-in-hand tradesperson who’s never used accounting software.

    Penalties for non-compliance: how bad does it get

    HMRC is introducing a new points-based penalty system for MTD. Miss a quarterly submission, and you collect a penalty point. Accumulate enough points, and you get a financial penalty. The threshold is four points before a £200 fine, with further fines for each subsequent failure. Points reset after a period of compliance, but the system is designed to escalate if you consistently ignore deadlines.

    Late payment interest applies on top of this, same as it does now. What changes is the frequency at which you can fall foul of deadlines. Under annual Self Assessment, you had one filing event to worry about. Under MTD, you’ve got five per year including the Final Declaration. Missing one in a hectic period, say January when everyone’s already stressed about tax, is now a points event rather than a catastrophic one-off fine, which is a small mercy. But the cumulative pressure is real, especially for freelancers juggling client work with admin.

    What to do right now if you’re in the first or second wave

    If you’re above the £50,000 threshold, you should already be in or approaching the HMRC pilot scheme. HMRC has been running a voluntary MTD for ITSA pilot since 2022, and joining it early gives you time to iron out software issues before compliance becomes mandatory. If you’re in the £30,000-£50,000 bracket, April 2027 sounds distant but it’s less than a year away, and switching accounting software mid-year is a headache nobody needs.

    Start by checking your gross qualifying income across all sources for the last tax year. Then look at the HMRC-recognised software list and, if you’re not already on a compatible platform, trial one or two before committing. Many have free 30-day trials. If your finances are genuinely complicated, particularly if you mix employment income with self-employment and property, an accountant who already uses MTD-compatible tools is worth the fee. The cost of getting it wrong outweighs the cost of paying someone to set it up correctly once.

    This connects to a broader shift happening across the UK’s working population. The growth in side hustles, remote freelancing, and portfolio careers, the same trends driving people to explore digital nomad visas or rage-apply their way out of corporate employment, means more people than ever are touching self-employment income without necessarily thinking of themselves as running a business. HMRC’s definition doesn’t care about how you self-identify. If the income qualifies, you’re in.

    The freelancer-specific headaches nobody talks about

    Quarterly reporting sounds straightforward until you consider how irregular freelance income actually is. A single large invoice paid in March can skew one quarter massively, then the next looks quiet. This isn’t a problem in terms of penalty points, since you’re reporting actuals, not estimates. But it does mean your tax picture will look uneven quarter to quarter, and you’ll need to be disciplined about putting money aside based on cumulative figures rather than waiting for the annual bill.

    Expense categorisation also matters more under quarterly reporting. Getting into good habits now, logging whether a software subscription is a business expense, whether that train journey was wholly for work, whether the home office deduction is justified, will save you a lot of pain when you’re reconciling five times a year instead of once. Agencies managing web design projects or marketing retainers for small business clients often build this kind of expense discipline into their own operations. A firm like dijitul, whose marketing and software work spans multiple client accounts, needs clean digital bookkeeping just to keep projects viable; that same discipline is what MTD is essentially asking freelancers to adopt.

    The shift towards more flexible working arrangements in the UK has created a generation of workers who move fluidly between employed and self-employed status. MTD will touch more of them than HMRC’s headline thresholds suggest, and the smart move is to get across the requirements now rather than scramble when the deadline lands.

    Frequently Asked Questions

    When does Making Tax Digital apply to freelancers in the UK?

    From April 2026 for those with qualifying income above £50,000, and from April 2027 for those above £30,000. A third phase covering income above £20,000 is planned for April 2028, though that date is subject to confirmation.

    Does MTD apply to side hustle income as well as my main freelance work?

    Yes. HMRC adds all qualifying self-employment and rental income together to determine your threshold. If you have a PAYE job plus side income, only the self-employment or rental portion counts, but it still contributes towards whether you cross the MTD threshold.

    What software do I need for Making Tax Digital for ITSA?

    You must use HMRC-recognised compatible software. Popular options include Xero, QuickBooks, FreeAgent, and Sage. HMRC maintains an updated list on GOV.UK. You cannot use HMRC’s own portal to submit MTD quarterly updates.

    What are the penalties if I miss an MTD quarterly submission?

    HMRC uses a points-based system. Each missed submission earns a penalty point, and once you accumulate four points you receive a £200 fine, with additional fines for each further failure. Points can be wiped after a sustained period of on-time filing.

  • Ofgem Changed the Rules on Smart Meters, Here’s What Your Energy Supplier Isn’t Telling You

    Ofgem Changed the Rules on Smart Meters, Here’s What Your Energy Supplier Isn’t Telling You

    There are roughly 35 million smart meters installed in homes and businesses across Great Britain, according to DESNZ smart meter statistics. And yet most people still have absolutely no idea what they’re actually entitled to, what their supplier can and cannot do with their data, or why the cheapest tariffs are increasingly locked behind having one. Ofgem has quietly updated its obligations on suppliers over the past 18 months, and the gap between what the regulator now requires and what your energy company is actively volunteering to tell you is… significant.

    I’ve spent a fair bit of time reading through Ofgem’s updated licence conditions and speaking to people who work in the energy sector. What follows is the plain-English version. No jargon, no spin.

    Smart meter showing energy usage in a UK home, illustrating smart meter Ofgem rules UK changes
    Photo by Connor Scott McManus on Pexels

    What Ofgem actually changed and why it matters now

    The big shift is around supplier obligations. Previously, energy companies had a “best endeavours” duty to offer customers a smart meter. That language has tightened. Suppliers are now required to take “all reasonable steps” to roll out smart meters to all domestic customers, with Ofgem able to take enforcement action where companies fall short. In practice, this means suppliers have to proactively contact customers, offer installation, and keep records proving they’ve done so.

    More importantly for you as a consumer: suppliers must now ensure that installed smart meters are operating in “smart mode”, meaning they’re actually communicating data back over the national network. First-generation SMETS1 meters (the older ones that often went “dumb” when you switched supplier) have largely been migrated onto the national DCC infrastructure, but if yours is still not sending data properly, your supplier has an obligation to fix it. You don’t have to just accept a glorified digital display.

    The tariff picture is getting complicated fast

    Here’s where the smart meter Ofgem rules UK conversation gets a bit spicy. An increasing number of time-of-use tariffs, including Octopus Energy’s Agile tariff and British Gas’s PeakSave offers, are exclusively available to smart meter customers. These tariffs can be genuinely cheaper if you shift usage to off-peak hours, but they’re inaccessible to the 10-plus million households that still don’t have a smart meter installed.

    Ofgem has been clear that suppliers cannot make a smart meter a condition of accessing the standard variable tariff or the price cap-protected unit rates. But time-of-use products sit in a different category. Suppliers are allowed to restrict those to smart meter customers, because the whole point is half-hourly data settlement. What they cannot do is pressure you into a smart meter by withholding your basic supply or threatening to move you off a standard tariff. The line matters, and some suppliers have been sailing close to it.

    Your data rights: what the supplier can and can’t access

    This is the bit nobody talks about at the point of installation. Smart meters can record your energy consumption in half-hourly intervals. That is a lot of data. Under the Smart Metering Implementation Programme framework and Ofgem’s licence conditions, there are three data access levels you should know:

    Half-hourly data requires your explicit consent for your supplier to access it. Without that consent, they can only see daily reads. If you’ve never been asked to consent, your supplier should not be pulling half-hourly data. Some have been doing so under buried terms in sign-up agreements, which Ofgem considers non-compliant.

    Daily reads are accessible to your supplier by default for billing purposes. This is fine and necessary.

    Monthly reads are the minimum that network operators can access for grid management. You cannot opt out of this.

    You have the right to withdraw consent for half-hourly data sharing at any time. You also have the right to request that your supplier only collects monthly reads if you have genuine privacy concerns. Your supplier must tell you clearly what data they’re collecting, who they’re sharing it with, and why. If they can’t do that on request, that’s a complaint to the Ofgem consumer advice pages or the Energy Ombudsman.

    Can you still refuse a smart meter?

    Yes. Full stop. No supplier can force you to accept a smart meter installation. The “all reasonable steps” duty is on the supplier to offer and encourage, not to compel. If an engineer turns up unannounced, you are within your rights to turn them away. If a supplier is threatening to charge you more on your current tariff because you’ve declined, that would be a breach of Ofgem’s licence conditions and worth escalating.

    That said, refusing indefinitely does increasingly mean missing out on time-of-use tariffs, which are only going to grow as the grid gets smarter. My take: the privacy concerns around half-hourly data are legitimate and worth understanding before you say yes, but if you get the data consent settings right, the case for eventually accepting one is pretty strong.

    What to do if your smart meter has stopped working

    Loads of people have SMETS1 meters that went “dumb” years ago and were never fixed. Under the current rules, your supplier has an obligation to restore smart functionality. Contact them in writing, specifically referencing your right to have a “communicating smart meter” under Ofgem’s licence conditions. Keep a record of the conversation. If they fob you off, escalate to the Energy Ombudsman after eight weeks (or sooner if you get a deadlock letter).

    It’s a bit like rage applying in UK workplaces, sometimes you just have to make noise to get a result. Polite persistence works better than most people expect when you’re armed with the specific regulatory language.

    The bigger picture for 2026 and beyond

    The smart meter Ofgem rules UK framework is heading in one direction: more automation, more dynamic pricing, and more reliance on real-time data. Vehicle-to-grid technology, heat pump optimisation, and demand flexibility schemes (like the National Grid ESO’s Demand Flexibility Service) all depend on households being connected via smart meters. The grid genuinely needs this data to function efficiently as we electrify more of daily life.

    For consumers, that’s both an opportunity and a pressure point. The people who understand their rights, manage their data consent properly, and pick the right tariff for their usage patterns will benefit. Everyone else will just… keep paying the default rate and wondering why their bills haven’t moved. There’s a version of this story that reads a lot like how the loneliness economy works: a system that profits most from the people who are least informed about how it operates.

    The one thing I’d genuinely recommend right now is checking your smart meter’s data sharing settings directly through your supplier’s app or online account. Most people have never looked. And given how much the smart meter Ofgem rules have shifted around half-hourly data consent specifically, there’s a decent chance your settings don’t reflect what you actually agreed to when you thought about it.

    Know your rights. Ask the question. If the answer feels evasive, that’s your cue to push harder.

  • Britain’s Boomerang Workforce: Why Over-50s Are Returning to Work, and What Employers Are Getting Wrong

    Britain’s Boomerang Workforce: Why Over-50s Are Returning to Work, and What Employers Are Getting Wrong

    Something is shifting in the British labour market, and it is not subtle. Workers who took early retirement between 2020 and 2022, whether by choice or nudged out by redundancy packages and pandemic reshuffling, are coming back. The over-50s returning to work UK trend has picked up serious pace through 2025 and into 2026, and the reasons are pretty obvious once you look at the numbers. Inflation did not behave. Mortgages repriced brutally. And the pension pot that looked sufficient three years ago is stretching a lot thinner than anyone planned.

    According to the Office for National Statistics, economic inactivity among the over-50s peaked in the post-pandemic years but has been declining since late 2023. Around 630,000 workers in the 50-64 age bracket left the workforce between 2020 and 2022. A significant chunk of them are now looking to return, or already have. The question is not really whether they are coming back. They are. The question is whether the businesses they are walking back into have any idea what to do with them.

    Older man working at office desk, representing over 50s returning to work UK
    Photo by RDNE Stock project on Pexels

    What is actually driving people back

    Let’s be real about what pushed this wave. The cost of living crisis did not spare retirees. Someone who exited a decent job in 2021 with savings, a pension and a plan found that plan stress-tested by energy bills, food costs, and particularly by the mortgage shock that hit from 2023 onwards. Plenty of over-50s still carry mortgage debt, and when fixed-rate deals expired and monthly payments jumped by hundreds of pounds, the retirement arithmetic stopped working.

    There is also a mental health and social dimension here that does not get enough airtime. Early retirement sounds brilliant in theory. In practice, a lot of people found it isolating. I have spoken to people in their mid-50s who describe leaving work and feeling cut off within six months, not because they were lazy but because so much of adult social life in Britain is structured around work. This connects directly to what we have been covering around Britain’s loneliness problem and the radical fixes councils are trying. The workforce re-entry is partly economic and partly about needing to feel useful and connected again.

    Where employers are getting this completely wrong

    Here is where it gets frustrating. The demand side exists. The supply side exists. But the join-up is a mess. A lot of employers are approaching returning over-50s with a template built for graduate hires, and it does not fit.

    The most common failure is assuming skills are outdated. Yes, someone who left in 2021 may have missed a software update or two. They have not forgotten how to manage a team, negotiate a contract, or read a room. There is a particular irony in tech companies hiring 22-year-olds with zero professional experience whilst turning away 56-year-olds with decades of it because their LinkedIn profile looks a bit dusty.

    Flexible working is another area where businesses are fumbling this. Many returning over-50s have caring responsibilities, health considerations, or simply different rhythms to their working day. The four-day week conversation is relevant here too; the companies that have genuinely committed to flexible output-based models are far better placed to attract this talent pool. Take a look at which UK companies have actually made the four-day week stick and you notice a pattern: they tend to be better at retaining older workers too. Coincidence? Not really.

    The hiring process is particularly broken

    Application forms that ask for the last 10 years of employment history and nothing before. Video-only interview stages that assume broadband confidence most 55-year-olds have but still feel like a barrier designed to filter rather than find. Automated applicant tracking systems trained on younger workforce data that bin CVs for no legitimate reason.

    Age discrimination in hiring is illegal under the Equality Act 2010. The gov.uk guidance on age discrimination is clear. But the law being on the books and the law being felt in practice are two very different things. Indirect age discrimination, where processes are not explicitly ageist but functionally exclude older workers, is rampant and largely unchallenged because most people do not have the appetite for an employment tribunal after a job rejection.

    Recruitment agencies are part of the problem too. Many are heavily incentivised to place younger candidates quickly rather than spend time with a returner who might need a bit of coaching on how to present their experience in 2026 terms. The market has not caught up with the demographic reality.

    What good support actually looks like

    Some employers are doing this well, and it is worth naming what they do differently. Returnship programmes, formal re-entry schemes with actual training and ramp-up time, are the gold standard. They treat the returning worker as someone with existing value who needs a runway, not a charity case who needs basic instruction. Businesses in financial services and professional services have led here; law firms and accountancies have been particularly active in this space since around 2024.

    Mentoring in reverse also works well. Pairing a returning over-50 with a younger colleague for mutual skill-sharing, the older worker gets their tech confidence back whilst the younger one picks up professional depth they simply have not had time to develop. Everyone benefits. It is one of those setups that sounds soft on paper but delivers hard results.

    Pay transparency matters too. One of the more demoralising experiences reported by over-50s re-entering is finding that roles they are qualified to walk straight into are advertised at salaries they would have considered entry-level 15 years ago. The compression of wage expectations, often driven by companies exploiting an anxious returner’s eagerness to just get back in, is a quiet form of exploitation that the industry does not talk about enough.

    The bigger picture for Britain’s economy

    The UK has a labour productivity problem. It also has a skills shortage in almost every sector worth naming. And it has hundreds of thousands of experienced workers who have been semi-parked on the bench by retirement or inactivity. Fixing the over-50s returning to work UK pipeline is not just the right thing to do by individuals; it is an economic no-brainer.

    The 2026 labour market is also seeing a broader shift in how people think about work, identity, and belonging. Many of the same currents driving younger Britons to rethink digital life and community are also pushing older workers to reassess what post-retirement actually means for them. The linear model of education, career, retirement was already looking shaky before inflation broke it. Now it is gone.

    Businesses that adapt to this reality, building genuinely flexible, age-inclusive hiring processes and treating experienced returners with actual respect, will pull ahead. Those that keep running their 2015 graduate recruitment playbook on a 2026 workforce will keep wondering why they cannot find decent candidates. The talent is there. The failure is structural, and it is fixable.