Author: Roberto Bernardi

  • Britain’s Flood Risk Map Has Been Redrawn, Is Your Home on the New Danger List?

    Britain’s Flood Risk Map Has Been Redrawn, Is Your Home on the New Danger List?

    The Environment Agency quietly dropped updated flood risk modelling earlier this year, and the numbers are not reassuring. Around 6.3 million properties in England are now estimated to be at risk of flooding, up from previous figures, and the revised UK flood risk map has reshuffled which postcodes sit in the danger zones. If you own a home, are trying to get a mortgage, or are wondering why your home insurance renewal came back eye-wateringly high, this is the piece you need to read.
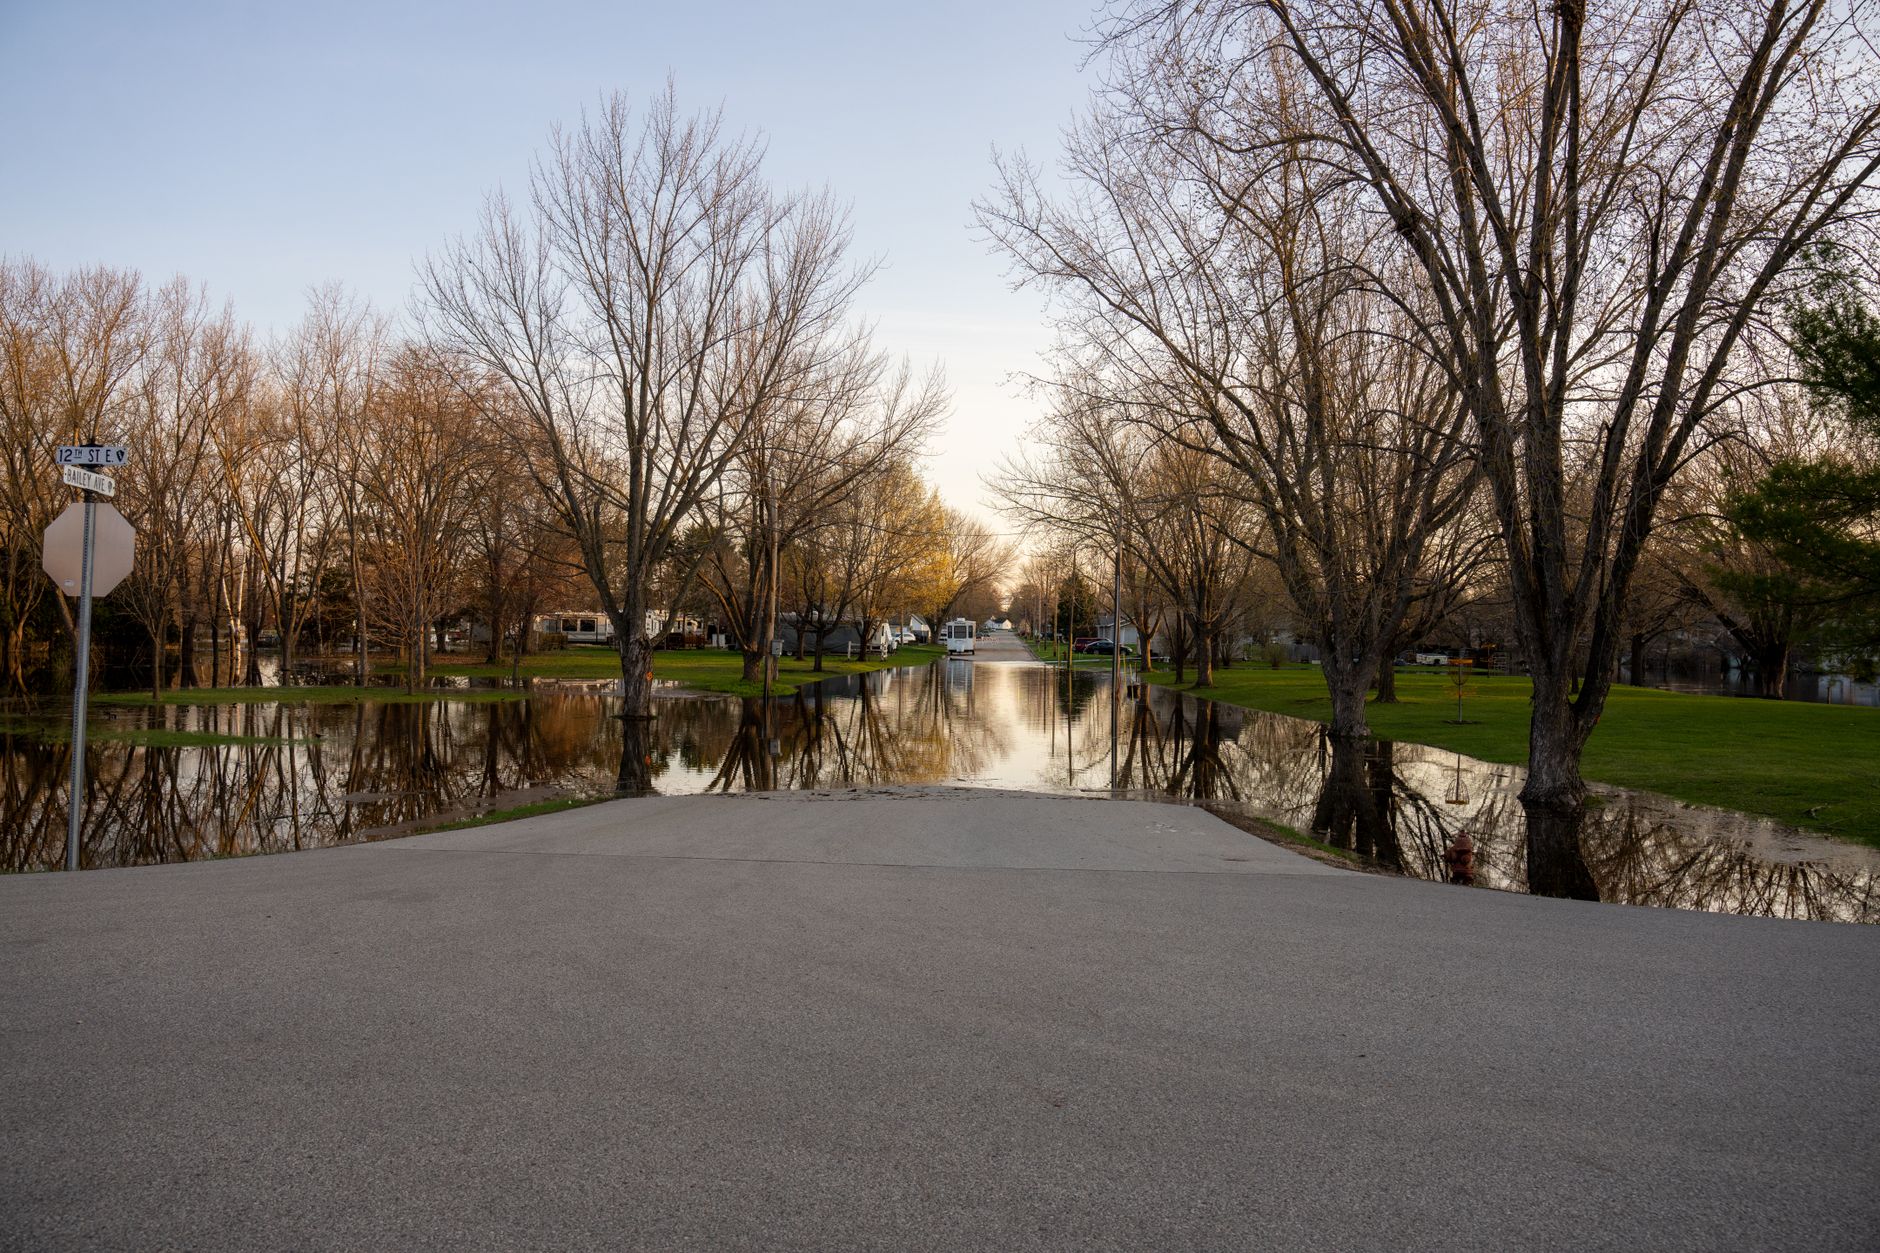
    Flooded residential street illustrating the impact of the updated UK flood risk map
    Photo by Tom Fisk on Pexels

    What the Environment Agency actually changed

    The agency uses a tiered system: Flood Zone 1 (low risk), Flood Zone 2 (medium risk), and Flood Zone 3 (high risk, split further into 3a and 3b, the functional floodplain). The 2026 modelling update incorporated newer climate projections, more granular surface water run-off data, and revised tidal surge estimates along coastal stretches, particularly in East Anglia, the Humber estuary, and Somerset Levels. Properties that sat comfortably in Zone 1 five years ago have, in some cases, slipped into Zone 2 or even 3. That is not a minor admin update. That is a change that can affect whether your bank will lend against your house.

    You can check the current data yourself on the Environment Agency’s official long-term flood risk checker, which is free and takes about thirty seconds. I’d genuinely encourage everyone to do this before reading any further. The result might surprise you.

    How flood risk zones affect mortgage eligibility

    Mortgage lenders are not legally required to refuse applications on high-risk properties, but many major banks now instruct their valuers to flag Zone 3 properties explicitly. HSBC, Nationwide, and Halifax all include flood risk as a material consideration in property assessments. If a surveyor flags significant flood risk, a lender can reduce their loan-to-value offer, require a specialist survey, or withdraw entirely. I’ve spoken to people in parts of Lincolnshire and the Yorkshire Wolds who’ve had mortgage offers pulled at the last minute after the revised zone data updated mid-application. It is a legitimate nightmare.

    The situation is even more complicated for remortgaging. A homeowner who bought in Zone 1 in 2019 and is now sitting in Zone 2 under the new modelling may find their current lender unwilling to offer a competitive deal at renewal. Switching lenders becomes harder when the risk picture has changed. The longer-term implication here is that some properties in reclassified areas are quietly becoming harder to sell, which feeds into a broader conversation about the financial pressures already stacking up on UK homeowners from every direction.
    Home insurance documents representing rising premiums linked to UK flood risk map reclassification
    Photo by Pavel Danilyuk on Pexels

    Insurance: the numbers are getting brutal

    Flood Re, the government-backed reinsurance scheme that subsidises flood cover for high-risk homes, has been a genuine lifeline since its launch in 2016. It covers around 250,000 properties. The problem is that Flood Re is built to wind down by 2039, with the idea that by then the insurance market will have “naturally” adjusted. That looks increasingly optimistic given that the number of properties in high-risk zones is growing, not shrinking.

    For properties that do fall outside Flood Re’s remit, or that sit in Zone 3 with a history of actual flood claims, premiums are climbing fast. The Association of British Insurers (ABI) confirmed in early 2026 that average home insurance premiums had risen 19% year-on-year, with flood-risk properties in some regions seeing spikes closer to 40%. Excesses on flood cover specifically can run into the thousands of pounds. For some homeowners in places like Hebden Bridge or Bewdley, which have flooded repeatedly, the excess is higher than the cost of the average flood damage event. At that point, the policy is essentially useless in practice.

    Some insurers are simply refusing to quote for properties with more than two flood claims in the past five years, full stop. Others are offering cover that excludes flood entirely, which creates an interesting legal grey area when homeowners try to sell without disclosing that gap to buyers.

    Which regions are most affected by the new modelling?

    The revised UK flood risk map hits several areas particularly hard. The Thames Estuary beyond Gravesend, large parts of the Norfolk Broads, coastal strips in Kent and East Sussex, the Mersey floodplain around Warrington, and low-lying land around the River Severn in Shropshire and Worcestershire all saw material changes in risk categorisation. Scotland has its own flood risk framework managed by the Scottish Environment Protection Agency (SEPA), and Wales via Natural Resources Wales, both of which have also updated their modelling in line with new climate scenarios.

    Rural areas have not escaped either. Farming communities in the Somerset Levels have faced this reality for over a decade, and the pattern of extreme wet winters is pushing more agricultural land into formal risk categories. This has knock-on effects on rural property values and, indirectly, on the cost of food supply chains. Even the urban fringes are catching it: new-build estates on former industrial brownfield land, which developers often pitched as “flood managed”, are now being reviewed under the updated surface water modelling.

    What can homeowners actually do?

    A few practical steps exist. First, check the Environment Agency map and get an independent flood risk survey if your property sits in or near Zone 2. A specialist report can sometimes be used to challenge a lender’s valuation position or negotiate with insurers. Second, look at physical flood resilience measures: flood doors, non-return valves on drains, raised electrical sockets. DEFRA has a property flood resilience grant scheme available through some local councils for properties that have flooded, worth up to £5,000. Ring your council and ask directly, because these grants are chronically underadvertised.

    Third, if you’re buying in an area that now appears on the updated UK flood risk map, factor in the long-term insurance trajectory, not just the quote you get this year. The affordability picture in five years could look very different. It’s the same kind of forward-looking financial thinking that’s reshaping how younger generations approach big financial decisions altogether, whether that’s retirement savings or housing security.

    And if you’re looking at a property near a main road in a flood-affected zone, here’s a slightly unexpected consideration: road drainage condition directly affects surface water run-off into residential areas. The state of Britain’s road infrastructure is already under enormous pressure, and degraded drainage infrastructure makes localised flooding worse. It all connects.

    The market reality no one wants to say out loud

    Here’s my read on this: a quiet but significant repricing of flood-risk property is already underway in parts of Britain, and most people in affected areas haven’t clocked it yet. The updated UK flood risk map is the mechanism by which that repricing will accelerate. Homes that can’t be insured at a sensible cost, can’t easily attract mortgage lending, and carry a disclosed flood history are going to struggle to hold value. The homeowners who move early, either adapting their properties or diversifying how they think about their assets, are the ones who’ll be in a better position when the rest of the market catches up.

    I’m not saying run. I’m saying: check your postcode, read your policy documents, and stop assuming that nothing has changed since you last looked. It probably has. Industries from real estate to automotive are having to rethink their digital strategies in response to rapid environmental and economic shifts, much like dijitul Automotive is doing in its own sector. Adaptation isn’t optional any more.

    Frequently Asked Questions

    How do I check if my home is on the updated UK flood risk map?

    Go to the Environment Agency’s free online checker at check-long-term-flood-risk.service.gov.uk and enter your postcode. It will show which flood zone your property falls in and whether it faces risk from rivers, the sea, or surface water. The map was updated with new modelling data in 2025 and 2026.

    Will being in a flood risk zone stop me getting a mortgage?

    Being in Flood Zone 2 or 3 does not automatically block a mortgage, but it significantly complicates the process. Lenders instruct valuers to flag flood risk, and some may reduce their loan-to-value ratio or require additional surveys. Properties in Zone 3 with a flood claims history face the most scrutiny.

    What is Flood Re and does my home qualify?

    Flood Re is a government-backed reinsurance scheme that helps keep home insurance affordable for around 250,000 high-risk properties in the UK. To qualify, your property must have been built before 1 January 2009 and must be a private residential home. Leasehold flats and small businesses are generally excluded.

    How much can home insurance premiums increase because of flood risk?

    It varies widely. The ABI reported average home insurance premium increases of 19% year-on-year in early 2026, but flood-risk properties in reclassified zones have seen rises closer to 40% in some regions. Properties with multiple previous flood claims may find some insurers refusing to quote at all.

    Can I get financial help to make my home more flood resilient?

    Yes. DEFRA’s property flood resilience grant offers up to £5,000 for eligible homes that have experienced flooding, available through local councils. Eligible improvements include flood doors, non-return drain valves, and raised electrical sockets. Contact your local council directly as the scheme is not well publicised.
  • The UK’s Pothole Crisis Has Reached Breaking Point, Here’s What It’s Actually Costing Drivers

    The UK’s Pothole Crisis Has Reached Breaking Point, Here’s What It’s Actually Costing Drivers

    British roads are falling apart. Not slowly, not quietly, but in a very visible, tyre-blowing, suspension-destroying way that is costing ordinary drivers serious money. The numbers behind pothole damage claims UK-wide have reached a level that would be embarrassing if anyone in charge seemed particularly bothered. Spoiler: they don’t.

    I drove through parts of the West Midlands last month and genuinely thought I’d accidentally turned onto a building site. I hadn’t. That was just the A road. The craters were so deep my coffee went over the cup holder. Welcome to Britain in 2026.

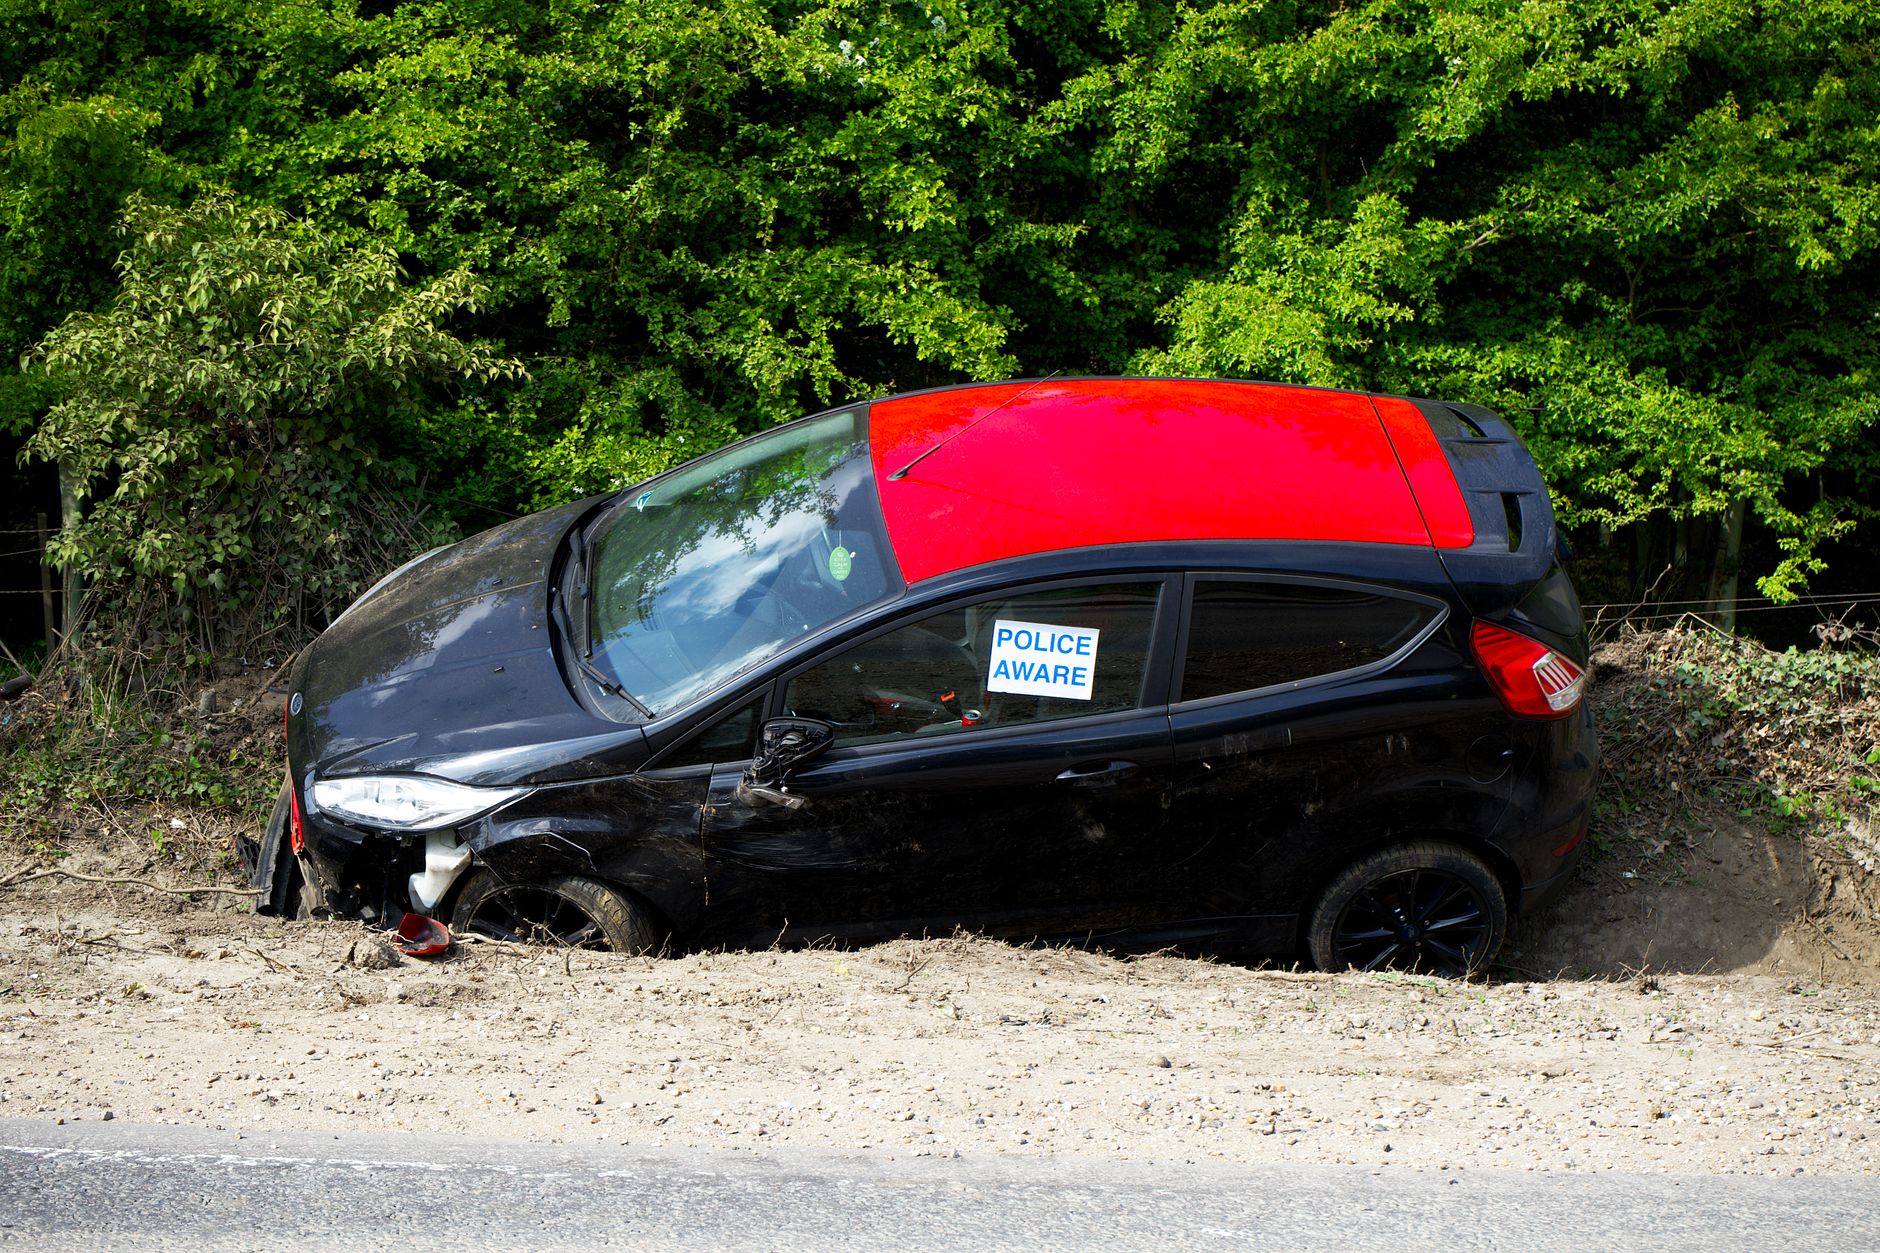
    Deep potholes on a deteriorating UK road surface illustrating the pothole damage claims UK crisis
    Photo by Mike Bird on Pexels

    How bad is the pothole problem right now?

    The Asphalt Industry Alliance, which publishes the Annual Local Authority Road Maintenance (ALARM) survey each year, reported in 2025 that it would cost over £16 billion to bring English and Welsh local roads back up to a reasonable standard. That figure has crept up year on year, and there is no realistic funding plan to close that gap. England alone has a backlog running into the billions, and the pace of deterioration keeps outrunning repair.

    Local councils reported filling around 1.7 million potholes in England and Wales over a single twelve-month period, but patching is not fixing. A lot of those repairs are cold-fill patches that crack and crumble within weeks, especially during wet winters. The cycle of patch-and-crumble costs money without actually solving anything.

    What drivers are actually spending on pothole damage claims UK-wide

    The RAC reported a sharp rise in pothole-related breakdowns throughout 2024 and into 2025. Broken shock absorbers, cracked alloy wheels, buckled rims and burst tyres are the most common outcomes of hitting a serious crater at speed. Repair bills for this kind of damage typically run between £150 and £500, and if you’re unlucky enough to damage steering geometry or a suspension arm, you’re looking at closer to £1,000 or more.

    Pothole damage claims submitted to local councils run into tens of thousands every year, but the success rate is low. Councils can reject claims if they can prove they had no prior knowledge of the pothole, or if they can show it was inspected within a reasonable timeframe under their duty of care obligations. Many drivers give up after their first rejection. The whole process feels deliberately exhausting, which, honestly, it probably is.

    Is council funding actually the problem?

    The easy answer is yes. The more complicated answer is: yes, but it’s not the only factor.

    Local council highways budgets have been under sustained pressure since 2010. The Local Government Association has repeatedly flagged that councils are having to make impossible choices between statutory services like social care, housing and waste collection, and discretionary maintenance spending on roads. Roads, which don’t vote and don’t complain to councillors, tend to lose those arguments.

    In autumn 2024, the government announced £500 million of additional pothole-repair funding as part of its budget. It made headlines for about two days. To put that in context against the £16 billion backlog, it covers roughly 3% of the problem. The rest sits on councils’ books as an unfunded liability. The gap between announcement-level politics and actual road quality is enormous, and drivers are literally feeling it every day.

    There’s also a deeper structural issue. Road materials and construction labour costs rose significantly post-2020, which means the same budget repairs fewer potholes than it did five years ago. Inflation in the highways sector hit councils hard, and most have not had their grants uplifted to compensate.

    How to actually make a pothole damage claim

    If your car takes damage from a pothole, you have a legal right to claim against the responsible highway authority. For most roads that’s the local council; for motorways and A-roads it’s National Highways. Here’s what gives you the best chance of a payout:

    Photograph everything immediately. The pothole itself, its dimensions if you can capture them safely, the damage to your vehicle, and the road markings around it. Get the exact location, ideally with a postcode or GPS coordinates. Then check the council’s own reporting portal to see if the pothole had already been logged. If it had, your claim becomes much stronger because it demonstrates prior knowledge. Submit your claim in writing, keep copies of every receipt, and if the council rejects it, ask specifically which inspection records they are relying on to prove reasonable maintenance.

    The money you’re owed isn’t guaranteed, but a well-documented claim is harder to dismiss. My take: the councils counting on you to give up after round one are banking on bureaucratic fatigue. Don’t give them the satisfaction.

    The wider drain on British wallets

    Potholes are not just a transport issue. They’re a financial one that touches everything. Delivery drivers, tradespeople, commuters, anyone who relies on their vehicle for work is absorbing repair costs that quietly eat into earnings. This sits alongside a broader picture of financial pressure that’s worth acknowledging. Articles on this blog have already looked at doom spending and how economic anxiety is affecting British bank accounts, and the pothole problem is just another chip in the armour of household budgets that are already stretched.

    There’s also the indirect cost. A vehicle running on damaged suspension burns more fuel, is more likely to fail its MOT, and depreciates faster. None of that shows up in pothole damage claims statistics, but it’s real money leaving real households.

    For freelancers and self-employed workers who put high mileage on their cars, this is particularly brutal. If you’re already navigating the UK’s inadequate safety nets for workers, an unexpected £400 tyre-and-rim bill is not a minor inconvenience. It can genuinely derail a month.

    What needs to change

    A long-term, ring-fenced roads maintenance fund, separate from council general budgets, is the most-cited fix from highways engineers and transport campaigners. Some argue for greater use of machine learning to identify deteriorating road surfaces before they become potholes, using vehicle telemetry data from connected cars. A handful of councils in the East Midlands have trialled predictive maintenance software with reasonable results, though the upfront cost puts most cash-strapped authorities off.

    The honest reality is that roads in Britain are a low-glamour infrastructure problem competing for attention against everything else. They will keep losing that competition until either the funding model changes fundamentally or enough voters get loud enough about the state of the tarmac outside their door.

    Until then, if you’re dealing with the financial strain of maintaining your home and your car simultaneously, the advice is the same: document everything, claim what you’re owed, and don’t let councils fob you off with a form rejection. The roads belong to all of us. So does the right to be compensated when they’re left in a state that wrecks our vehicles.

    Frequently Asked Questions

    How do I make a pothole damage claim against my local council?

    Photograph the pothole and your vehicle damage immediately, note the exact location, and check whether the pothole was already reported to the council. Submit a written claim to the local highways authority with all receipts and evidence. If rejected, ask them to provide their inspection records under the Highways Act 1980 duty of care.

    How much can I claim for pothole damage to my car?

    There is no fixed cap, and your claim should cover the actual cost of repairs, supported by receipts from a garage. Common claims range from £100 to £500 for tyres and alloy wheels, rising to £1,000 or more if suspension or steering components are damaged. Keep every receipt and get more than one quote where possible.

    Can councils legally reject my pothole damage claim?

    Yes. Under the Highways Act 1980, a council can avoid liability if it demonstrates it had a reasonable system of inspection and repair in place and had no prior knowledge of the defect. This is called the ‘Section 58 defence’. A well-documented claim showing the pothole had already been reported can significantly weaken this defence.

    Who is responsible for fixing potholes on motorways vs local roads?

    Motorways and the strategic A-road network in England are managed by National Highways, and claims for those roads go to them directly. Most other roads, including local A-roads, B-roads and residential streets, are the responsibility of the local county or unitary authority council.

    Why are UK potholes getting worse in 2026?

    Years of underfunded local highways maintenance budgets, rising repair costs due to inflation, and wetter winters accelerating road surface deterioration have all combined. The Asphalt Industry Alliance estimates the repair backlog for England and Wales now exceeds £16 billion, with no credible plan to clear it at current funding levels.

  • Why Britain’s Volunteer Sector Is Running on Empty, and the Digital Tools Quietly Keeping It Alive

    Why Britain’s Volunteer Sector Is Running on Empty, and the Digital Tools Quietly Keeping It Alive

    There are around 160,000 voluntary organisations in England alone, according to NCVO’s Civil Society Almanac. Most of them are held together by a group chat, a spreadsheet that nobody fully understands, and at least one very tired person who has been doing the treasurer role since 2014. That is not an exaggeration. It is, if anything, a conservative description of how volunteer-run organisations UK-wide are actually functioning right now.

    Council funding for community and voluntary services has been gutted over the past decade. The Local Government Association has tracked cumulative cuts to council budgets exceeding £15 billion since 2010, and the community sector has absorbed a huge share of that pain quietly, without press conferences or protests. What has filled the gap, at least partially, is technology. Specifically, free and low-cost digital tools that nobody designed for this purpose but that grassroots groups have adopted anyway because they had no other option.

    Volunteer-run organisation UK members coordinating around a laptop in a community hall
    Photo by RDNE Stock project on Pexels

    The funding collapse no one’s talking about

    Community first responders, food bank coordinators, neighbourhood watch schemes, charity fundraisers, parent-run after-school clubs, these groups are not on the news. They do not trend. But the work they absorb is staggering. In many rural and semi-urban areas, community first responders are the first on scene at medical emergencies, often arriving before an ambulance, trained and coordinated entirely through volunteer effort. Their operational costs are minimal, but even minimal costs require funding, and local council grants that once covered kit, training refreshers, and insurance have been progressively cut back.

    A community first responder group in Derbyshire I came across recently had their annual council grant reduced from £4,200 to £800 in the space of three years. They kept going. They cut the training budget, moved all communications to a free WhatsApp Business account, and started using Google Sheets to manage their rota. It works, mostly. But it is precarious in a way that should genuinely worry people.

    Which digital tools volunteer groups are actually using

    The picture across the UK’s volunteer sector is less coordinated than you might hope. Different groups have landed on very different solutions, often based on what one tech-literate member happened to know. Here is what I keep seeing come up:

    WhatsApp and Signal remain the workhorses for day-to-day coordination. Simple, free, and almost universal. The problem is that group chats are chaotic under pressure, messages get buried, and there is no accountability trail when things go wrong or someone misses a shift.

    Google Workspace (specifically Sheets, Forms, and Meet on the free tier) has become the default back-office for hundreds of groups. Rota management in Sheets, volunteer sign-ups via Forms, committee meetings on Meet. It is clunky but it costs nothing, and that matters enormously when your entire annual budget is four figures.

    Canva has genuinely transformed how smaller community groups present themselves publicly. A charity bake sale poster that looked like it was made in Word 2003 is now a clean, on-brand design in 20 minutes. The free tier is genuinely capable for most volunteer use cases.

    Eventbrite and Ticket Tailor for ticketed fundraising events. Ticket Tailor in particular has become popular because it charges a flat monthly fee rather than taking a percentage of each ticket, which matters when margins are tight.

    Mailchimp (free up to 500 contacts) for newsletters and donor communications. A lot of charity fundraising groups have found that a monthly email update dramatically improves donor retention compared to posting on Facebook alone.

    Volunteer coordinator managing a UK volunteer-run organisation rota on a mobile phone
    Photo by Anna Pou on Pexels

    When digital reach does something unexpected

    There is a phenomenon happening alongside all of this practical coordination work, and it is worth paying attention to. Some volunteer-run groups, using these same free tools, are accidentally building audiences way beyond their immediate community. The reach that platforms like TikTok, Instagram Reels, and even Facebook Groups can generate for genuinely local, human content is something that no amount of council grant money could have bought.

    I wrote earlier about the psychology driving how people spend when they feel economically anxious, and there is something related happening here: people are hungry for content that feels real and community-rooted precisely because so much of what they see online does not. A village first aid volunteer posting a 30-second reel about their training session gets 40,000 views. A food bank coordinator sharing a weekly update on Instagram Stories builds a following that converts to genuine donations. This is not a strategy. It happens because authenticity cuts through.

    You can see this pattern play out in fascinating ways across the UK’s community event scene. For a longer read on the village fête organisers who accidentally went viral: how britain’s most quintessentially local events are finding a national audience, the same dynamic is at work: groups with no marketing budget and no influencer connections finding unexpected scale through the same tools they were using just to tell locals about the car park situation.

    The real gap: digital skills, not digital access

    Access to the tools is mostly not the problem. The problem is capacity and knowledge. Most volunteer coordinators are already stretched. Learning a new platform, migrating data, training other volunteers, and maintaining a consistent digital presence on top of the actual volunteer work is a real ask. I have spoken to charity fundraising leads who are running everything on their personal mobile because the organisation does not have a shared device, and who are doing their volunteer admin at 11pm after a full day’s work.

    This is where organisations like the Department for Culture, Media and Sport and NCVO’s digital support programmes could make a meaningful difference, and to be fair, some initiatives exist. But uptake is patchy and awareness among smaller groups is low. The volunteer groups that are thriving digitally tend to have one person with a particular set of skills. When that person burns out or moves on, the digital infrastructure often collapses with them.

    This is connected to the same pressures behind the rage-applying trend sweeping UK workplaces: people at capacity, doing more with less, and eventually hitting a wall. Volunteers are not immune to burnout just because they are not being paid.

    What actually needs to change

    Free tools are keeping volunteer-run organisations UK-wide functional. That is genuinely impressive and worth acknowledging. But “functional” is not the same as “resilient”, and right now the sector is one burnout away from structural failure in a lot of local areas.

    The conversation needs to move beyond digital tools and back to sustainable funding. Councils need ringfenced community resilience budgets. Central government needs to recognise that volunteer coordination infrastructure is public infrastructure. And the tech platforms offering free tiers to charities and community groups need to be more transparent about what happens when those tiers change or disappear.

    In the meantime, the people running rota spreadsheets at midnight and designing posters on Canva at the kitchen table are, quietly, holding a huge amount of this country together. The least we can do is notice.

    Frequently Asked Questions

    What free digital tools do UK volunteer groups use to manage rotas?

    Most groups use a combination of Google Sheets for rota management, WhatsApp or Signal for day-to-day communication, and Google Forms for volunteer sign-ups. These tools are free and widely understood, which makes them practical despite their limitations for larger or more complex organisations.

    How much has council funding for voluntary organisations been cut?

    The Local Government Association has tracked cumulative cuts to English council budgets exceeding £15 billion since 2010, with community and voluntary services absorbing a significant portion. Many individual grants to local groups have been reduced by 50-80% or eliminated entirely over the past decade.

    Can volunteer-run UK organisations get free software or digital support?

    Yes, several routes exist. NCVO offers digital support resources, and organisations like Canva, Google Workspace, and Mailchimp all have free tiers that cover most small group needs. DCMS and some lottery-funded programmes also offer digital capacity grants, though awareness and uptake remain low.

  • Ozempic, the NHS, and the Weight Loss Drug Debate Dividing Britain’s Medical Community

    Ozempic, the NHS, and the Weight Loss Drug Debate Dividing Britain’s Medical Community

    Something big is happening in British healthcare right now, and depending on who you ask, it’s either a revolution or a rationing crisis dressed up in a syringe. GLP-1 receptor agonists, the class of drugs that includes semaglutide (sold as Ozempic and Wegovy), have gone from niche diabetes medication to the most talked-about pharmaceutical development in a generation. The Ozempic NHS UK weight loss drugs conversation has spilled out of medical journals and into group chats, TikTok comment sections, and GP surgeries across the country. I’ve been following this story for months, and the more you dig, the messier it gets.

    Auto-injector pen representing Ozempic NHS UK weight loss drugs treatment
    Photo by Nataliya Vaitkevich on Pexels

    What the NHS actually prescribes and who qualifies

    The NHS does offer semaglutide, specifically Wegovy, for weight management, but the criteria are tight. According to NICE guidance TA875, you need a BMI of at least 35 plus a weight-related health condition, or a BMI of 30-34.9 in certain high-risk groups. You also need to be referred to a specialist weight management service, not just your GP. That’s a significant barrier in practice, given that specialist services are stretched thin and waiting lists in some areas run to over a year.

    The approval covers a two-year course, and NICE was clear that it’s meant to sit alongside a reduced-calorie diet and increased physical activity, not replace them. That nuance gets lost completely in the public conversation, where Ozempic has been flattened into a simple “fat jab” narrative. The drug itself works by mimicking a hormone that regulates appetite and slowing gastric emptying, which means people feel fuller for longer and, in clinical trials, lost an average of around 15% of body weight. Those are numbers that genuinely impress endocrinologists.

    The private clinic explosion and why it’s worrying doctors

    Because NHS access is so restricted, a parallel private market has exploded. Dozens of online clinics now offer semaglutide prescriptions after a short questionnaire and sometimes a brief video call. Prices vary wildly, from around £150 to over £300 per month, and the quality of oversight varies even more wildly. I’ve seen screenshots circulating on Reddit’s r/UKfitness where people describe getting a prescription approved within 20 minutes of signing up, no face-to-face appointment, no blood tests, no follow-up scheduled.

    The Medicines and Healthcare products Regulatory Agency (MHRA) has issued warnings about unlicensed versions of semaglutide being sold online, some of which have caused serious harm. The GMC has also flagged concerns about prescribing standards at some online clinics, particularly around patient selection and monitoring. The FCA, meanwhile, has gone after misleading advertising claims. It’s a regulatory pile-on that tells you something is genuinely wrong, even if the drugs themselves are legitimate when properly supervised.

    The supply shortage nobody warned patients about

    Here’s the bit that gets overlooked in most coverage: there is a real, ongoing supply problem. When Ozempic became culturally famous, largely through celebrity endorsement and social media speculation, demand spiked globally. Novo Nordisk, the Danish manufacturer, couldn’t keep up. In the UK, this created a crunch that hit diabetic patients hardest, because Ozempic was originally approved for type 2 diabetes management, and suddenly people using it off-label for weight loss were competing for the same supply.

    NHS England issued guidance asking clinicians to prioritise diabetic patients, but enforcement is inconsistent. Some pharmacies have been out of stock for weeks at a time. The irony is painful: people who genuinely need the drug for blood sugar control found themselves unable to access it partly because wealthier individuals were buying it privately for cosmetic weight loss. That’s not a comfortable sentence to write, but it’s the reality the supply chain exposed.

    The ethics: who deserves access and on what terms

    This is where the debate gets genuinely thorny. Obesity is a complex, multi-factorial condition, and there’s good evidence it has strong genetic and environmental components. The idea that people simply lack willpower is medically outdated. But the NHS has finite resources, and every decision to fund one treatment is implicitly a decision not to fund something else. At roughly £9,000 per patient for a two-year course at list price, the NHS’s commitment to semaglutide represents a significant budget line.

    There are clinicians who argue that treating obesity aggressively now will save money long-term by reducing rates of type 2 diabetes, heart disease, and certain cancers. That health economics argument is compelling. There are others who worry that medicalising body weight in this way ignores structural causes: poor food environments, food poverty, inadequate green spaces. Both things can be true simultaneously. You can support access to effective treatment while also wanting supermarkets to stop placing ultra-processed food at eye level and fizzy drinks in the checkout queue.

    The class dimension is hard to ignore too. Right now, Ozempic NHS UK weight loss drugs are largely accessible to people who can pay £200-plus a month privately, or who live near a well-funded NHS weight management service. People in areas of high deprivation, who statistically carry higher rates of obesity-related illness, are often least able to access either route. That gap is a policy failure, not a personal one. It connects to the same systemic tensions you see in how statutory sick pay leaves lower-income workers disproportionately exposed when health gets in the way of work.

    What happens when you stop taking it

    Something the glossy before-and-after posts don’t tend to mention: the weight generally comes back when you stop. Clinical studies have shown that patients regain a significant proportion of lost weight within a year of discontinuing semaglutide. This raises an uncomfortable question about whether GLP-1 drugs are a lifelong prescription for many users, and if so, what that means for NHS costs and individual financial planning alike.

    For private users, a lifelong monthly spend of £150-£300 is a serious commitment. The financial pressure of maintaining that kind of habit connects to broader patterns of spending decisions driven by anxiety and aspiration that I’ve seen discussed in the context of doom spending and economic anxiety among British consumers. It’s worth being honest with yourself about whether you have a plan for what comes after the prescription.

    Where this is actually heading

    NICE is due to review the prescribing landscape as more data comes in. NHS England is piloting primary care-based prescribing in some areas, which would bring access closer to GPs rather than requiring specialist referral. Eli Lilly’s tirzepatide (Mounjaro), another GLP-1 drug, is also now available in the UK and generating its own set of debates about comparative efficacy and pricing.

    The honest position is that these drugs work, they carry real risks if used without proper supervision, the supply situation is still fragile, and access is currently distributed in a way that favours the wealthy. None of that makes Ozempic good or bad in itself. It makes the healthcare system around it a problem worth taking seriously. For a generation that’s watched financial priorities shift dramatically, the question of how much you’re willing to spend to manage your health long-term is one that’s going to come up more, not less.

    My take? The drug is real, the results are real, and the controversy is real. Anyone thinking about pursuing it, NHS or private, deserves clearer information than they’re currently getting from either a 20-minute online consultation or a TikTok testimonial.

    Frequently Asked Questions

    Can I get Ozempic on the NHS for weight loss in 2026?

    Yes, but with strict criteria. NICE guidance requires a BMI of 35 or above alongside a weight-related health condition, or a BMI of 30-34.9 in high-risk groups. You’ll need a referral to a specialist weight management service, which can involve a lengthy wait depending on your area.

    Is it safe to buy Ozempic or Wegovy from a private online clinic in the UK?

    It can be, but standards vary significantly between providers. The MHRA has warned about unlicensed counterfeit versions circulating online, and the GMC has raised concerns about some clinics prescribing without adequate assessment or follow-up. Always use a CQC-registered service with a named prescribing clinician.

    Why is there an Ozempic shortage in the UK?

    Global demand spiked sharply after semaglutide gained celebrity-driven attention as a weight loss drug, outpacing Novo Nordisk’s manufacturing capacity. This hit UK diabetic patients particularly hard, as Ozempic was originally licensed for type 2 diabetes management and NHS guidance prioritises those patients.

    How much does Ozempic or Wegovy cost privately in the UK?

    Private prescription costs typically run between £150 and £300 per month depending on the dose and the clinic. At NHS list price, a full two-year course works out to roughly £9,000, though NHS patients do not pay this directly.

  • Why Thousands of Britons Are Quietly Moving to Rural Portugal, and What They’re Escaping

    Why Thousands of Britons Are Quietly Moving to Rural Portugal, and What They’re Escaping

    There’s a pattern I keep noticing. A professional in their late thirties, maybe a couple with two kids in primary school, maybe a remote worker with a laptop and a lease they can’t wait to end, and they’ve quietly started researching villages in the Alentejo or the interior of the Algarve. They’re not shouting about it on LinkedIn. They’re just gone. The wave of British moving to Portugal 2025 isn’t a tourism story. It’s a cost-of-living story, a housing story, and honestly, a disillusionment story wrapped up in one.

    Rural Portuguese village in the Alentejo, destination for British moving to Portugal 2025
    Photo by Liane Ferreira on Pexels

    According to the UK government’s living-in-Portugal guidance, British nationals now need to apply for residency under Portuguese law post-Brexit, and the numbers doing so have climbed every year since 2021. Portugal’s SEF (now AIMA, the Agency for Integration, Migration and Asylum) processed a significant uptick in British applications between 2023 and 2025. The country is no longer just a retirement destination for pensioners from Surrey. It’s pulling in families, freelancers, and burnt-out professionals who have done the maths and decided the maths doesn’t work here anymore.

    What’s actually pushing people out of the UK

    Let’s be direct about this: nobody leaves a country they love on a whim. The people I’ve spoken to, and I’ve been following this trend properly since late 2024, aren’t starry-eyed romantics chasing some fantasy. They’re running the numbers on mortgage repayments on a three-bed semi in Bristol versus buying a detached stone farmhouse in central Portugal outright, sometimes with change left over. That comparison is doing a lot of heavy lifting.

    UK house prices remain brutal. Average prices nationally are still north of £285,000 according to the ONS, and in London or the South East you’re staring at double or triple that for anything liveable. Meanwhile, rural Portugal offers stone properties in places like Castelo Branco, Portalegre, or the Beira Interior for €80,000 to €150,000. That’s not a typo. For families already stretched across rising mortgage rates, childcare costs, and energy bills, that gap is existential. It’s the same restlessness feeding into what we’ve covered about Britain’s soft-saving generation choosing a different kind of future, except this version involves actually packing boxes and booking a ferry.

    The visa routes Britons are actually using

    Post-Brexit residency in Portugal is navigable, but it does require paperwork and patience. The main routes in 2025 are the D7 Passive Income Visa, the Digital Nomad Visa (D8), and the standard residency route for those employed by a non-Portuguese company. The D7 is particularly popular with retirees and people with rental income or dividends, it requires demonstrating a minimum monthly income of roughly €820, though in practice banks and consulates prefer to see considerably more. The D8 suits remote workers on UK contracts, and it’s become a genuine pipeline for British tech workers, designers, and consultants who’ve negotiated permanent remote arrangements.

    Portugal abolished its Non-Habitual Resident (NHR) tax regime in 2024, replacing it with the IFICI scheme, a 20% flat tax on Portuguese-sourced income for qualifying professionals in certain sectors. It’s less generous than NHR was, but it still represents a significant advantage for high earners compared to UK income tax rates. Many applicants are also finding that their UK state pension, combined with low living costs in rural areas, stretches considerably further than it ever did at home, especially relevant given how poorly the UK performs on worker financial protections compared to its European neighbours.

    Rural Portugal vs city Portugal: where people are actually going

    Lisbon and Porto are the headline names, but rural Portugal is where the real relocation story is unfolding in 2025. The Alentejo region, a vast sun-baked plateau between Lisbon and the Spanish border, has seen a steady influx of British families setting up in small towns like Évora, Estremoz, and Mértola. The Beira Interior, further north, offers cooler summers, cheaper property, and landscapes that genuinely look like they belong in a different century, in a good way.

    Internet connectivity was the traditional bloophole for rural Portugal, but that’s changed fast. Fibre rollout has accelerated significantly under Portuguese government investment programmes, and many villages that looked impractical for remote workers three years ago are now properly connected. Healthcare through the SNS (Serviço Nacional de Saúde) is available to residents, though waiting times in rural areas mean many British expats maintain private health insurance, which costs significantly less than equivalent UK private cover.

    Day-to-day costs genuinely are lower. A family of four can eat well, local produce, wine, good bread, on around €600 to €800 a month. Utilities are modest. Schooling through the Portuguese state system is free and, in many areas, has Portuguese language integration support for foreign children. Some families are choosing international schools in nearby cities, but plenty are going full immersion, which the kids adapt to faster than the parents do, in my experience of talking to those who’ve made the move.

    What the communities being left behind look like

    This is the part of the story that doesn’t get talked about enough. When a skilled remote worker leaves Bristol or Sheffield or Edinburgh for the Alentejo, something leaves with them: local spending, community involvement, a network. The cumulative effect of many such departures doesn’t show up in a single headline, but it compounds quietly. It’s a different flavour of the same dynamic described in the drain of Londoners to smaller UK cities, except this version crosses a border entirely.

    There’s also a psychological layer here. The people I’ve spoken to aren’t universally cheerful about leaving. There’s grief involved. Leaving ageing parents, a GP you trust, a Saturday football routine, friends who’ve known you since school. One woman who relocated to the Alentejo with her husband and two daughters in autumn 2024 told me it took eight months before it felt right rather than reckless. That kind of honest timeline rarely makes it into the aspirational Instagram posts. The economic anxiety that nudges British households into impulsive financial decisions at home can equally nudge people into life-altering moves abroad, and the emotional reckoning comes later.

    Is this a permanent shift or a moment?

    I’d argue it’s structural, not cyclical. The conditions that are driving British moving to Portugal in 2025 haven’t improved at home: housing affordability, stagnant real wages, high childcare costs, and a general sense that the social contract is looser than it used to be. Portugal, for its part, has actively courted foreign residents and their spending power, even as debate inside Portugal continues about gentrification pressures in Lisbon and the Algarve coast.

    Rural Portugal, specifically, seems to be absorbing this wave with less friction. Small communities that were losing their own young people to Lisbon are, ironically, being repopulated by British families bringing income, renovation spend, and a willingness to integrate. Local câmaras (councils) in some interior municipalities have even launched welcome programmes, offering reduced bureaucratic friction and sometimes subsidised renovation grants for abandoned rural properties.

    It’s not a perfect story. Language barriers are real, bureaucracy is slow, and the Portuguese property market in desirable areas is no longer as cheap as it was five years ago. But for thousands of Britons doing the maths in 2025, rural Portugal still wins the comparison by a considerable margin. And they’re moving. Quietly, deliberately, and in growing numbers.

  • Doom Spending Is Quietly Draining British Bank Accounts, Here’s the Psychology Behind It

    Doom Spending Is Quietly Draining British Bank Accounts, Here’s the Psychology Behind It

    You’ve had a rough week. The news is grim, your energy bill landed like a punch, and somehow you’ve just spent £47 on a skincare set you didn’t plan to buy and a houseplant you definitely don’t need. Sound familiar? That’s doom spending, and it’s quietly becoming one of the defining financial habits of this decade in Britain.

    The term has been circulating in financial wellness circles for a couple of years now, but doom spending UK search interest has genuinely spiked in 2026 as the cost-of-living hangover drags on. It’s not reckless splurging in the traditional sense. It’s more specific than that: impulse buying triggered by economic anxiety, a kind of “things are bad so I might as well enjoy something now” logic that feels emotionally rational even when it’s financially destructive.

    Young woman scrolling on her phone, illustrating doom spending UK impulse buying behaviour
    Photo by Anete Lusina on Pexels

    What doom spending actually is (and isn’t)

    Doom spending isn’t the same as being bad with money. It’s a coping mechanism, and a surprisingly sophisticated one psychologically. Financial therapist Simonne Gnessen, co-author of Sheconomics and founder of Wise Monkey Financial Coaching, has described it as a response to “learned helplessness”, when people feel they have no meaningful control over big financial forces, they redirect agency into small, immediate purchases that deliver a quick dopamine hit.

    The logic goes something like this: if my rent is going up regardless, if inflation is still biting, if a recession feels baked in, then £30 on a new game or a meal out isn’t really the problem. So why not? The trouble is that this reasoning, repeated dozens of times a month across millions of people, adds up to a serious structural drain on household finances.

    The FCA’s Financial Lives survey is blunt about the scale of the problem. In its most recent wave, 7.4 million UK adults showed characteristics of low financial resilience, meaning they’d struggle to absorb even a modest financial shock. Amongst 18 to 34-year-olds, the demographic most likely to self-identify as doom spenders, the picture is notably worse. Savings buffers are thin, and discretionary spending hasn’t dropped in line with income pressure.

    Why anxiety and the high street are a dangerous combination

    British retail has known about the anxiety-spending link for years. Walk into any Primark on a bad news day and the tills are busier than you’d expect. The high street, and increasingly the scroll of an Instagram or TikTok shop, is engineered to intercept exactly this emotional state. Flash sales. Low-price-point impulse items at checkout. “Treat yourself” messaging that makes spending feel like self-care rather than a financial decision.

    Online shopping has accelerated this massively. The friction that once existed between wanting something and buying it, driving to a shop, queuing, handing over cash, is almost entirely gone. One-click purchasing on ASOS, Amazon, or Vinted means the gap between impulse and transaction can be under 30 seconds. That’s not long enough for the rational brain to catch up with the anxious one.

    I’ve spoken to people who describe checking out online baskets the same way they used to scroll social media, almost unconsciously, as a form of distraction. One woman in her late twenties told me she’d set up a spreadsheet to track her doom purchases after realising she’d spent over £300 in a single month on things she’d returned within a week. “I wasn’t even keeping the stuff,” she said. “I just needed to feel like I was doing something.”

    The class dimension nobody’s talking about

    Here’s something the doom spending conversation tends to flatten: this behaviour doesn’t look the same across income brackets. For higher earners, doom spending might mean an impulsive weekend trip or a piece of furniture they didn’t need. For people on lower incomes, it’s more likely to be small, frequent purchases, a meal from Deliveroo when cooking feels like too much, a few items from Poundland or a cheap fast-fashion haul. The psychological driver is identical; the financial consequence is proportionally much heavier.

    There’s also a loneliness angle here that connects to what researchers and councils are increasingly flagging across the UK. Britain’s loneliness economy has normalised spending as a substitute for connection, buying things becomes a low-effort way to feel something when social energy is depleted. That’s not a coincidence. It’s a pattern retailers actively exploit.

    Can you actually stop doom spending?

    Financial therapists are fairly consistent on this: willpower alone doesn’t work, because doom spending isn’t primarily a discipline problem. It’s an emotional regulation problem. Telling someone to “just stop” impulse buying when they’re using purchases to manage anxiety is about as effective as telling someone anxious to “just relax”.

    What does seem to help, according to practitioners like those at the Financial Wellbeing Centre and independent financial therapists, is building in friction deliberately. Some people use browser extensions that add a 24-hour delay to online checkouts. Others move to cash-only spending for a month to make the exchange feel real again. A few therapists recommend a “doom journal”, writing down what you were feeling when you added something to a basket and checking in the next day on whether the urge is still there.

    The data does suggest that awareness helps. In the FCA’s own consumer research, people who tracked their spending even loosely were significantly more likely to report feeling in control of their finances, not because tracking magically created more money, but because it interrupted the unconscious loop.

    There’s also something to be said for addressing the anxiety itself rather than just its spending symptom. If economic stress is the root cause, and you’re working in a job that feels unstable or dealing with side-hustle tax anxiety, those underlying pressures need somewhere to go. Understanding what HMRC’s new real-time tax reporting rules mean for your finances as a freelancer, for instance, can actually reduce the ambient dread that pushes people toward spending as relief.

    The bigger picture for UK finances in 2026

    Doom spending UK isn’t a niche quirk. It’s a systemic response to a prolonged period of economic instability, and it feeds into a feedback loop that makes that instability worse at the individual level. People spend to feel better about a situation they can’t control, reduce their financial resilience, and then feel more anxious as a result.

    What’s different now compared to previous periods of economic stress is the infrastructure around impulse spending, the apps, the one-click checkout, the social commerce. Generation Z, who came of age financially during the cost-of-living crisis, are particularly caught in this. They’re simultaneously the most financially stressed young cohort in decades and the most heavily marketed-to through channels specifically designed to convert mood into spending.

    None of this means individual behaviour doesn’t matter. But blaming people for doom spending without acknowledging the environment that engineers it is too easy. The FCA is watching the data closely. British financial therapists are seeing more clients present with spending patterns clearly linked to economic anxiety. And millions of people are quietly wondering where their money went at the end of every month, and finding the honest answer uncomfortable.

    Frequently Asked Questions

    What is doom spending and why is it trending in the UK?

    Doom spending is impulse buying driven by economic anxiety, the feeling that things are bad enough that you might as well enjoy small pleasures now. It’s trending in the UK because prolonged cost-of-living pressure has created exactly the kind of chronic financial stress that triggers this coping behaviour.

    Is doom spending the same as being bad with money?

    No. Financial therapists distinguish doom spending from general financial mismanagement. It’s a specific emotional regulation response to anxiety, not a character flaw. People who are otherwise quite disciplined financially can fall into it during periods of sustained economic stress.

    How much is doom spending costing UK consumers?

    Precise figures are hard to isolate, but the FCA’s Financial Lives data shows 7.4 million UK adults have low financial resilience, meaning impulse spending is creating real vulnerability. Anecdotally, financial therapists report clients regularly spending £200-£400 per month on unplanned purchases they later regret.

    What can I do to stop doom spending?

    Financial therapists recommend building in deliberate friction rather than relying on willpower, browser delay extensions, cash-only periods, or a spending journal to identify emotional triggers. Addressing the underlying anxiety, whether through financial planning or mental health support, is more effective long-term than simply cutting up your card.

    Is doom spending worse for younger people in the UK?

    FCA data suggests yes. Adults aged 18 to 34 have thinner savings buffers and higher rates of impulse spending relative to income. Gen Z in particular grew up financially during the cost-of-living crisis and are heavily targeted through social commerce channels designed to convert low-mood scrolling into purchases.

  • AI Tutors in British Schools: The Promise, the Pushback, and Who Actually Benefits

    AI Tutors in British Schools: The Promise, the Pushback, and Who Actually Benefits

    There’s a quiet experiment happening across British classrooms right now. In hundreds of state schools from Manchester to Bristol, students are logging onto AI-powered tutoring platforms instead of waiting a fortnight for their teacher to mark a batch of essays. The software adapts in real time, flags gaps in understanding, and claims to personalise learning at a scale no single teacher ever could. It sounds like a fix for everything. I’m not convinced it is.

    Secondary school students using laptops for AI tutoring in UK schools
    Photo by Pavel Danilyuk on Pexels

    The platforms getting the most attention include Khanmigo (Khan Academy’s AI tutor), Century Tech, and a handful of others already embedded in UK secondary schools through Department for Education-backed pilots. Century Tech, which is based in London, has partnerships with hundreds of schools and uses machine learning to map what it calls a “learning genome” for each student. The pitch is compelling on paper. The reality, as several teachers I’ve spoken to describe it, is more complicated.

    What AI tutoring actually looks like in a state school

    Most of these platforms work on a simple loop: a student answers a question, the system assesses the response, then serves the next piece of content based on whether they got it right or partially right or missed it entirely. Think of it like a very sophisticated quiz that never gets tired. For students who learn well independently and have decent reading ability, it can be genuinely useful revision support. For students who don’t, it can feel like being left alone in a room with a textbook that occasionally talks back.

    The attainment gap is the real sticking point here. According to the Education Endowment Foundation, disadvantaged pupils in England are already, on average, around 18 months behind their better-off peers by the time they finish secondary school. The question everyone is avoiding is whether handing an AI tutor to a Year 9 student in a poorly resourced school, with patchy broadband and no quiet space to work at home, actually helps that student, or just gives their more comfortable peers another advantage.

    Why Ofsted’s position matters here

    Ofsted hasn’t published formal guidance on AI tutoring tools yet, but inspectors are already asking questions about them during school visits. The concern from senior leaders I’ve heard about isn’t that the technology is bad, it’s that schools are adopting it faster than they can evaluate it. A school that can point to Century Tech dashboards and show inspectors that students are completing personalised modules looks like it’s doing something innovative. Whether those modules are actually improving outcomes is a different question, and one that takes years of data to answer properly.

    There’s also a safeguarding dimension that doesn’t get discussed enough. When a student interacts with an AI system for extended periods, who owns that interaction data? Schools operating under UK GDPR obligations and overseen by the ICO need to be asking hard questions about data residency, retention policies, and whether any of that granular learning data could be used commercially down the line. The contracts between EdTech companies and local authorities are not always transparent about this.

    Teacher reviewing AI tutoring platform data with a student in a UK school
    Photo by RDNE Stock project on Pexels

    The teacher replacement panic, and why it’s mostly missing the point

    The headline fear, that AI tutors will replace teachers, is doing the rounds again and honestly I find it a bit of a distraction. No AI system is going to notice that a 14-year-old has gone quiet because something is happening at home. No algorithm is going to pick up on the body language that tells a good teacher a student is about to disengage completely. The relational side of teaching is not replicable, and the educators I respect most know this.

    What is a legitimate concern is deskilling. If a school leans so heavily on AI-generated feedback that teachers stop writing their own assessment notes, stop building their own understanding of individual students, the institutional knowledge that makes good teaching good starts to erode. It’s the same issue you see in any profession where automation takes over the routine tasks: the routine tasks were also where junior professionals learnt the craft.

    This connects to something broader happening in British workplaces right now. The frustration building across professional sectors as AI reshapes job expectations is as real in staffrooms as it is in offices. Teachers entering the profession today will work alongside these tools for their entire careers. The question is whether they’re being trained to use them critically or just handed a login and told to get on with it.

    Which students are actually benefiting right now

    I’d argue the honest answer is: students who would have been fine anyway. If you have a motivated Year 11 student with a stable home environment and a decent laptop, an AI tutor that drills GCSE maths gaps at 10pm is genuinely useful. It’s flexible, it’s patient, and it doesn’t judge. For that student, it’s a free version of what private tutoring has always offered, and that’s not nothing.

    But the students who most need support, those with special educational needs, those with chaotic home lives, those for whom school is the only structured environment in their day, often find these platforms frustrating and alienating. The adaptive learning models are built on aggregated data that skews towards students who interact with technology fluidly. Students who don’t fit that profile get a worse experience from the same tool.

    Schools managing tight budgets are also under pressure to justify the subscription costs of these platforms against everything else they’re cutting. The same budget conversation that covers EdTech licences also covers things like energy compliance, from R2G.co.uk handling display energy certificate requirements to basic building maintenance. Every line item is a trade-off, and AI tutoring subscriptions are not cheap.

    What good implementation actually looks like

    The schools getting this right are the ones treating AI tutoring as a supplementary tool with a clear, limited brief: catch-up support for specific topics, homework differentiation, low-stakes retrieval practice. They’re not using it to replace teacher feedback on creative work or to automate the pastoral stuff. They also build in teacher review time, so the data the platform generates actually informs what happens in the classroom rather than just sitting in a dashboard nobody checks.

    Harris Academy in South London and a cluster of schools in the Oak National Academy network have been more thoughtful about this than most. They’ve published their evaluation frameworks, which is more than a lot of schools using these tools have done. Transparency about what’s working and what isn’t is the minimum standard, and right now it’s still the exception.

    The longer-term picture for AI tutoring in UK schools depends on whether the DfE gets serious about outcome measurement. The current pilots are generating a lot of enthusiasm and not enough hard evidence. If you want to know whether this technology closes the attainment gap, you need longitudinal data tracked across demographic groups, not a vendor’s case study from a grammar school in Surrey. That rigour is possible. It just requires political will to demand it, and so far that will is patchy at best.

    Meanwhile, the students who need the most support are waiting. And the clock is still ticking on their 18-month gap.

  • The Rise of the British Micro-Wedding and How Couples Are Reclaiming the Day From the Wedding Industry

    The Rise of the British Micro-Wedding and How Couples Are Reclaiming the Day From the Wedding Industry

    The average UK wedding now costs somewhere in the region of £20,000, and that figure has been creeping upward for years. So it makes sense that a growing number of couples are looking at that number, then at each other, and quietly deciding: no, actually, we’re not doing that. The micro-wedding, an intimate ceremony with fewer than 20 guests, is no longer a pandemic-era compromise. It’s become a genuine first choice, and I’d argue it’s one of the most honest reactions to how bloated the wedding industry has become.

    A micro-wedding UK ceremony in a converted barn with under 20 guests seated in natural light
    Photo by MunozPhoto_ on Pexels

    What’s shifted isn’t just budgets. It’s the whole attitude. People in their late twenties and thirties who’ve been to eleven weddings in four years, sat through three-hour gaps between ceremony and dinner, eaten the same chicken-or-salmon choice plate, and watched couples look exhausted on what was supposed to be the best day of their lives, they’re opting out of the format entirely. The micro-wedding isn’t smaller because people can’t afford big. For many couples, it’s smaller because they actually want it that way.

    What counts as a micro-wedding in the UK?

    There’s no official definition, but most people in the wedding space treat anything under 20 guests as a micro-wedding, separate from an elopement (which typically means just the couple, possibly with two legal witnesses). The legal minimum in England and Wales for a civil ceremony is two witnesses plus a registrar. Scotland’s rules differ slightly, and Northern Ireland has its own framework, but across the UK the baseline is broadly the same: you don’t need a crowd.

    Micro-weddings tend to keep immediate family and a handful of close friends. The guest list cuts out colleagues, cousins you haven’t spoken to in years, and the obligatory plus-ones. That cull alone changes the entire logistics chain, from catering to transport to table settings to the sheer emotional weight of trying to give everyone a good time.

    The venues actually built for this

    One of the reasons micro-weddings struggled before 2020 was that most licensed venues in the UK were designed around 80 to 150 guests. You’d pay for a room that dwarfed your party, or get squeezed into a back function room that felt like an afterthought. That’s changed a lot. Smaller venues have spotted the gap and properly leaned in.

    In London, places like the Peasant in Clerkenwell and various Georgian townhouses across Islington and Hackney now offer dedicated intimate ceremony packages. The Lake District has seen a boom in remote farmhouses and converted barns that cap at 15 or 20 by design rather than necessity. Scotland’s Highlands are particularly well set up, with croft conversions and private estate spaces that are genuinely better suited to small numbers. Cornwall and the Scottish Borders have both seen new licensed venues open specifically targeting the micro-wedding market since 2023.

    Micro-wedding UK reception table setting for a small intimate celebration
    Photo by Jonathan Borba on Pexels

    Restaurants have also come into their own here. Getting married in a room above your favourite restaurant, with a tasting menu replacing a buffet line, is something that a guest list of 12 makes possible in a way that 80 simply doesn’t. The Pig hotel group, which runs properties across Hampshire, Somerset, and Kent among others, has been quietly popular with couples who want something that feels more like a private dinner party than a wedding reception.

    Does a micro-wedding actually save you money?

    This is where it gets genuinely interesting, and honestly a bit complicated. On paper, fewer guests means lower catering costs, fewer favours, fewer chairs, fewer flowers. And yes, the headline number is usually lower. A micro-wedding in the UK can come in at anywhere from £5,000 to £12,000 depending on choices made. That’s a real saving versus the national average.

    But the saving isn’t as clean as people expect. What tends to happen is that the per-head spend goes up significantly. When you have 15 guests instead of 80, couples often feel more comfortable spending £150 per head on food rather than £60. The flowers go from budget centrepieces to properly considered arrangements. The photographer who was going to cover a full day gets booked for a longer stretch because the day is more relaxed. The dress doesn’t change price. The rings don’t change price. The officiant fees, legal registration costs, and honeymoon budget stay roughly the same.

    What a micro-wedding reliably cuts is the structural overhead: the wedding planner coordinating 120 people, the venue hire minimum spend, the wedding favours nobody wanted, the coach hire for guests, the extra evening buffet. Those costs are real and they add up. But if you’re expecting to walk away spending a fifth of what a traditional wedding costs, you’ll likely be surprised by how the budget still finds places to go.

    If you’re researching and planning around destination options too, our piece on why Britons are choosing to get married abroad and what it actually costs covers a lot of the same ground from a different angle. It’s worth a read if you’re weighing up whether the venue matters more than the guest count.

    The social pressure element nobody talks about enough

    Choosing a micro-wedding is still, in 2026, a decision that requires some social courage. Telling parents that their siblings won’t be invited, explaining to a close friend that they didn’t make the cut, managing the group chat reactions when people learn 18 people were invited total, none of that is easy. Some couples sidestep it with a separate party later, a more relaxed gathering weeks after the actual ceremony that anyone can come to. That works well for some and feels like a compromise to others.

    The wedding industry has also got better at guilt-tripping micro-wedding couples. Venues sometimes charge a “minimum spend” that effectively prices a small group the same as a larger one. Photographers market their “full-day coverage” packages hard even when a four-hour ceremony doesn’t need it. I’ve spoken to couples who felt pressured by suppliers to upscale once they saw how small the guest list was. Going into it knowing your numbers clearly and being comfortable holding firm matters.

    Planning and sourcing for a micro-wedding often happens outside traditional wedding fairs too. A lot of couples are using platforms and communities online to find suppliers who genuinely work well at smaller scale. If you’re putting together content or resources around the planning process, tools like LinkPress are used by publishers trying to get that kind of niche information in front of the right audience.

    What the data is actually showing

    According to data from the ONS Marriage and Civil Partnerships statistics, the number of marriages in England and Wales has been declining overall for over a decade, but the ceremonies that do happen are increasingly skewing smaller and more personal. Anecdotally, UK wedding planners and venues that have spoken to trade press this year are reporting strong demand for intimate packages, with several noting waiting lists for their smaller ceremony rooms that outstrip their main ballroom bookings.

    The shift also connects to a broader cultural recalibration around spending and meaning, something I’ve been seeing across different parts of British life. The same generation making micro-wedding choices are the ones quietly leaving London for smaller cities to find more space and a slower pace. There’s a thread running through all of it: less performance, more reality.

    Is this trend going to stick?

    My honest read is yes. The cost pressures alone will keep micro-weddings relevant, but they’d survive even in a prosperous market because the appeal isn’t purely financial. Couples who’ve been to enough large weddings know exactly what they’re trading. A room full of 120 people, half of whom you’re vaguely obliged to, is a different experience to a long lunch with the 15 people who matter most to you, on a day that’s supposed to be about exactly that.

    The wedding industry will adapt, it always does. More venues will build smaller licensed spaces. More photographers will offer half-day packages. More caterers will develop tasting menus designed for ten. And honestly, that’s probably better for everyone involved, including the industry itself. A day that the couple actually remembers with joy, and that doesn’t financially damage them for years afterwards, is a better advert for the whole thing than an Instagram-perfect event that left them stressed and skint.

    Frequently Asked Questions

    What is a micro-wedding in the UK?

    A micro-wedding typically means a ceremony with fewer than 20 guests, distinct from a full elopement which usually involves just the couple and two witnesses. In England and Wales, the legal minimum for a civil ceremony is two witnesses plus a registrar, so there’s plenty of flexibility in how small you go.

    How much does a micro-wedding cost in the UK?

    Micro-weddings in the UK generally cost between £5,000 and £12,000, compared to the national average of around £20,000 for a traditional wedding. The saving is real but smaller than many couples expect, because per-head spending on catering, photography, and styling often increases when the guest list shrinks.

    What venues in the UK are best suited to micro-weddings?

    Smaller licensed venues like boutique hotels, restaurants with private dining rooms, and rural conversions (particularly in Cornwall, the Lake District, and the Scottish Highlands) are well suited to intimate ceremonies. Many venues now specifically market 15 to 20 guest packages, so it’s worth searching for ‘intimate wedding venue’ alongside your county rather than generic wedding venue directories.

    Can you have a legally valid micro-wedding in the UK?

    Yes, absolutely. A ceremony is legally valid in England and Wales as long as it takes place in a licensed venue (or a registered building for religious ceremonies) with two witnesses present and the correct paperwork filed with the local register office. The number of additional guests has no bearing on the legal validity.

  • The Dark Side of the UK’s Festival Boom: Hidden Fees, Burnout, and Why Glastonbury Isn’t the Whole Story

    The Dark Side of the UK’s Festival Boom: Hidden Fees, Burnout, and Why Glastonbury Isn’t the Whole Story

    The festival season looks great on paper. Record attendance numbers, headline acts pulling huge crowds, Glastonbury selling out in minutes. If you only read the press releases, British festival culture is thriving. But spend five minutes in any online ticketing queue, or try to budget a weekend at a mid-tier festival in 2026, and a very different picture emerges. UK music festival hidden costs have quietly turned what used to be a rite-of-passage summer experience into something only certain people can genuinely afford, and the industry is not being honest about it.

    Large crowd at a UK music festival illustrating the hidden costs behind attendance figures
    Photo by Andrius Šimkus on Pexels

    The ticket price is the starting point, not the total

    Glastonbury general admission tickets now sit at £373 plus a £5 booking fee. That number gets quoted everywhere as if it represents the actual cost of attending. It does not. Add coach or train travel (return from London to Castle Cary runs well over £80 during festival dates), camping equipment if you do not already own it, a locker rental, the Worthy Farm car park fee if you drive, and food and drink across five days, and you are looking at a realistic spend closer to £700 to £900 per person for what is nominally a £373 event. That is before you buy a single piece of merchandise.

    It is not just Glastonbury. Download, Reading, Leeds, Latitude, Wilderness, End of the Road, the pattern repeats itself. Booking fees of 10 to 15 per cent on top of face value have become standard. Some events now charge separate fees for printing your ticket, for digital delivery, and for the privilege of selecting your camping zone. These are not accidents. They are deliberate structural choices designed to make the headline price look lower than it actually is.

    Dynamic pricing has arrived and it is making things worse

    Ticketmaster’s dynamic pricing rollout in the UK has attracted significant press attention, mostly focused on huge stadium acts like Oasis. But the same model is seeping into festival ticketing, and it is less visible there. Early-bird tiers sell out fast, standard tiers follow, and by the time most fans get through a virtual queue the price has jumped by £30 to £60. The consumer advocacy group Which? has raised concerns about the transparency of these pricing structures, and the Competition and Markets Authority has started paying closer attention to the live events sector. But for now, the buyer bears all the risk.

    The practical effect is a system where the people who can afford to act quickly, who have a flexible card ready, who are not at work when tickets drop, get the better price. That is not a meritocratic lottery. That is a system that structurally advantages people with financial slack.

    On-site cost inflation is out of control

    I went to a well-known outdoor festival in the south of England last summer and paid £8.50 for a pint of lager I could have bought at my local for £4.20. A basic burger was £14. A coffee at 8am was £5. None of this is new, festivals have always charged a premium, but the gap between on-site and off-site prices has widened considerably since 2022, driven partly by genuine supply chain costs and partly by the fact that many festival operators now take a significant cut of trader revenue, which gets passed directly to the consumer.

    The ONS reported that food and non-alcoholic drink prices rose by over 25 per cent between 2021 and 2024. Festival food stalls absorbed some of that, but they also used it as cover to push margins further. A realistic daily food and drink budget for a festival in 2026 is £60 to £80 per person if you are not being particularly extravagant. Across a three-day event that is £180 to £240 on top of everything else.

    Attendance figures are being used to mislead

    When festival organisers announce record attendance, they are almost never discussing affordability. The numbers function as marketing. What they do not reveal is the demographic shift quietly happening inside those gates. Anecdotally, and from conversations I have had with regular festivalgoers, the crowd at mid-to-large festivals is getting older and more financially homogeneous. The students and early-20s who used to pack Reading and Leeds are being priced out, not necessarily by the headline ticket cost, but by the cumulative weight of everything around it.

    This links to something worth reading if you have not already: the growing loneliness economy in the UK, where shared communal experiences are increasingly commodified. Festivals were once a genuinely democratic space. They are becoming a luxury product with the aesthetics of inclusivity still stapled on top.

    The smaller festival squeeze is real

    Smaller, independent festivals are caught in a brutal bind. They cannot negotiate the same deals with artists, insurers, or local authorities that the big players can. Their overheads have risen sharply. But their audiences are often more price-sensitive, and the competition for discretionary spending is fierce. Several beloved independent events have folded in the past two years, citing unworkable economics. Others have survived by cutting their line-up depth, shrinking their footprint, or quietly removing the low-cost camping options that used to make them accessible.

    The result is a market where the premium end is consolidating and the affordable middle is hollowing out. If you can spend £1,200 for a couple across a weekend, there are excellent options. If you cannot, the choices are narrowing fast.

    The burnout conversation nobody wants to have

    There is a growing sense amongst regular festivalgoers that the magic is diminishing alongside the affordability. I have spoken to people who have attended the same events for a decade and feel like they are now paying more for a worse version of something they used to love. Overcrowded campsites, aggressive up-selling at every turn, app-based wristband systems that do not work, queues for everything. The financialisation of the experience has changed its texture.

    This is part of a broader pattern around exhaustion with systems that feel rigged, where the official version of something and the lived reality have drifted too far apart. When the gap between the Instagram photo and the muddy, expensive, overcrowded actuality gets too wide, people start opting out. And many are.

    What actually needs to change

    The CMA’s ongoing scrutiny of ticket pricing is a start. Full price transparency at the point of first contact, meaning the total cost including all fees displayed before you enter a queue, should be a baseline requirement. The ASA has previously acted on misleading pricing in other sectors; there is an argument it should apply the same standards to live events.

    Some festivals have experimented with payment plans, allowing fans to spread ticket costs across several months. Kendal Calling and a handful of others have done this well. It does not solve the on-site inflation problem, but it makes the headline cost manageable for people without a lump sum available.

    The deeper issue is structural. When festivals are owned by private equity or large entertainment conglomerates, the pressure to extract maximum revenue from every interaction is relentless. The community-run event and the corporate entertainment product can look identical from the outside. They are not. And working out which is which before you hand over your money is harder than it should be. The UK’s festival boom is real. So is the affordability crisis running underneath it, and the two things are not unconnected.

    Frequently Asked Questions

    How much does it actually cost to attend a UK music festival in 2026?

    For a major festival like Glastonbury, the realistic total cost per person including transport, food, drink, and essentials is typically £700 to £900, despite the headline ticket price of around £373. Mid-tier festivals are cheaper but still often cost £400 to £600 all-in for a three-day event.

    Are UK music festival hidden costs legal?

    Booking fees and service charges are legal in the UK, but there is growing pressure from the Competition and Markets Authority and consumer groups like Which? to enforce full price transparency at the point of first display. Currently, fees are often added only at checkout, which many argue is misleading.

    Why have festival ticket prices increased so much?

    A combination of factors is driving prices up: artist fees have risen sharply post-pandemic, insurance and site costs have increased, and booking platforms have expanded their fee structures. Dynamic pricing models, similar to those used for flights, are also becoming more common in the live events sector.

  • Rage Applying Is Sweeping British Workplaces, But Does It Actually Lead Anywhere?

    Rage Applying Is Sweeping British Workplaces, But Does It Actually Lead Anywhere?

    You’ve had a terrible week. Your manager ignored your idea in a meeting, you got passed over for a promotion that went to someone who does half the work, and the office kitchen still smells like someone’s reheated fish. So you open LinkedIn at 11pm and start firing off applications to every job that looks even vaguely interesting. Sound familiar? That’s rage applying, and it’s taken over British workplaces.

    Person frustrated at laptop late at night representing rage applying UK jobs
    Photo by https://kaboompics.com/ on Pexels

    Rage applying UK jobs isn’t some niche Gen Z quirk anymore. Recruitment platform Reed reported a significant spike in late-evening and weekend application surges in 2025, patterns that don’t match calculated job-hunting behaviour. Totaljobs found in their 2025 workforce report that nearly 40% of UK workers had sent a job application specifically out of frustration with their current employer, rather than from a planned career move. That’s not a small number. That’s a movement.

    Where did rage applying actually come from?

    The phrase went viral on TikTok in late 2022, largely driven by US workers sharing stories of quitting their jobs mentally before ever handing in notice. But the British version has its own flavour. We’re less likely to loudly quit-quit. We’re more likely to quietly stew, then open fifteen browser tabs at midnight and send 30 applications while watching The Bear.

    The frustration fuelling this is real and well-documented. According to the CIPD’s 2025 UK Working Lives survey, job satisfaction across British workplaces has been declining steadily, with poor management and lack of recognition consistently ranking as the top two drivers of disengagement. That’s the kindling. Rage applying is what happens when someone finally strikes a match.

    What does a rage application actually look like?

    Quantity over quality. That’s the signature. Where a deliberate job search might involve tailoring a CV to each role, researching the company, and crafting a considered cover letter, rage applying tends to look like a scattergun. Generic CV. No cover letter or a copy-pasted one. Role requirements barely glanced at. Sometimes people apply for jobs they’re massively overqualified for, sometimes wildly underqualified. The point isn’t really to land the job. The point is to feel like you’re doing something.

    I’ve spoken to people who sent 60 applications in a single weekend and heard back from precisely two. That’s not a strategy. That’s a coping mechanism dressed up as a career move. And recruitment professionals know exactly when it’s happening.

    Gemma Parrish, a senior recruiter at a Manchester-based staffing agency, told me she can almost always spot a rage application within seconds. “The CV hasn’t been adapted at all, there’s no real sense they’ve read the job description, and if we call them, half the time they’ve forgotten they applied.” She says these applications almost never progress beyond the first screen. Hiring managers simply don’t have the time to coach enthusiasm out of someone who showed up in their inbox by accident.

    So does rage applying UK jobs ever actually work?

    Here’s where it gets interesting. Because occasionally, yes, it does. Not because the application was good, but because the timing was lucky. A role sits unfilled for weeks, a half-decent CV lands at exactly the right moment, and suddenly someone who rage-applied on a Tuesday has a job offer by Friday.

    Totaljobs’ data suggests that roughly 12% of people who rage-applied ended up in a new role within three months. That sounds encouraging until you notice that the majority of those moves weren’t necessarily into better jobs. Pay was similar, responsibilities were similar, and a chunk of respondents admitted that within six months they felt the same way about the new employer as they had about the old one. The frustration followed them.

    This is the core problem. Rage applying is a reaction to a feeling, not to a clear-eyed assessment of what you actually want from your career. You end up treating symptoms rather than causes. If your workplace makes you miserable because of rigid working structures or genuinely poor management, jumping sideways to a company with the same culture isn’t going to fix anything. You’ll just be rage-applying again in 18 months.

    The psychological side nobody talks about

    There’s actually something useful in the impulse, even when the execution is chaotic. Job dissatisfaction left completely unaddressed can corrode your mental health pretty fast, and doing something about it, even something messy, can help people feel less trapped. Psychologists call this behavioural activation: taking action reduces the feeling of helplessness, even if the action itself isn’t perfectly calibrated.

    The issue is when rage applying becomes a substitute for either having a real conversation with your employer or genuinely reflecting on what you want next. A lot of British workers, especially those who’ve been in the same role for years, have never actually sat down and thought about what a better job looks like for them specifically. They just know this one isn’t it. That’s a starting point, not a destination.

    It’s worth noting that the isolation of not feeling seen at work feeds directly into wider wellbeing issues. The loneliness many UK workers feel isn’t just a personal problem; it’s a structural one that employers are increasingly being held to account for, whether they like it or not.

    How to channel the rage into something that actually moves the needle

    If you’re deep in a rage-applying spiral, I’d say: don’t delete everything you’ve sent. But do pause before you send more. Give yourself 48 hours and write down three things you’d need a new job to offer that this one doesn’t. Specific things: remote working two days a week, a manager who actually gives feedback, a team in a sector you care about. Now filter applications through that list.

    Also talk to someone in your network before you apply cold to 40 companies. Referrals still convert at a significantly higher rate than cold applications in the UK. LinkedIn data from 2025 showed that referred candidates are four times more likely to be hired than those who apply through job boards. One good conversation beats thirty scatter-gun CVs every single time.

    And if you’re someone who’s already made the jump to a role that came out of rage applying, check in honestly with yourself about whether the move was actually right or just a change of scenery. Because the workforce is full of people who’ve made reactive moves and ended up needing to course-correct twice. A little more deliberation upfront saves a lot of pain later.

    Rage applying UK jobs isn’t going anywhere. If anything, it’ll probably get more common as hybrid working makes the bad days feel even more claustrophobic and the barrier to firing off an application stays near zero. The question isn’t whether you’ll ever do it. It’s whether you’ll catch yourself doing it and decide to be slightly more strategic about what happens next.

    Frequently Asked Questions

    What is rage applying and why is it trending in the UK?

    Rage applying is the act of mass-sending job applications out of frustration with your current employer, rather than as part of a deliberate career plan. It’s trending in the UK because workplace dissatisfaction is high and digital job platforms make it easier than ever to apply to dozens of roles in minutes.

    Does rage applying UK jobs actually lead to a new role?

    Sometimes, but the odds aren’t great. Totaljobs data suggests around 12% of rage-applicants land a new role within three months, but many of those roles are lateral moves with similar pay and culture. Without a clear idea of what you want, you risk ending up in the same situation at a different company.

    How do recruiters spot a rage application?

    Recruiters look for generic CVs that haven’t been tailored to the role, missing or copy-pasted cover letters, and candidates who seem unaware of what the company actually does. Hiring managers rarely progress these applications beyond the initial screening stage.