Category: World News

  • Thermal Imaging Surveys Are Becoming the New Must-Have for British Home Buyers

    Thermal Imaging Surveys Are Becoming the New Must-Have for British Home Buyers

    British home buyers in 2026 are dealing with something that wasn’t really on the radar five years ago: the discovery, months after moving in, that their new home is haemorrhaging heat through walls no one warned them about. Standard surveys catch structural defects, damp patches, roof issues. What they don’t catch is invisible. That’s where the thermal imaging survey comes in, and it’s quietly becoming one of the smarter additions to the home-buying checklist.

    I’ve spoken to buyers who found out the hard way. One couple in Sheffield paid for a full structural survey, got a clean bill of health, then spent their first winter wondering why the energy bills were catastrophic despite having a “good” boiler. A thermal imaging assessment after the fact revealed that the cavity wall insulation had completely failed on two sides of the house. Classic case of something a camera sees that a clipboard doesn’t.
    Engineer conducting a thermal imaging survey on the exterior wall of a British terraced house
    Photo by Tom Fisk on Pexels

    What does a thermal imaging survey actually show?

    A thermal imaging survey uses an infrared camera to map the temperature distribution across walls, ceilings, floors, and windows. Cold patches show up in blue and purple tones; warm spots glow orange and red. The technology has been used in the construction industry for years, but it’s now becoming accessible to individual buyers as a pre-purchase add-on, often costing between £200 and £400 depending on property size and surveyor.

    What it reveals falls into three main categories. First, heat loss: gaps in insulation, thermal bridges at joist ends, poorly fitted loft insulation, and drafts around window frames. Second, damp and moisture intrusion, because wet materials retain heat differently to dry ones and show up as anomalies in the thermal picture. Third, structural issues like missing insulation in stud walls, failed cavity fill, and cold bridging through steel lintels, all of which a standard visual inspection would completely miss.

    The Royal Institution of Chartered Surveyors (RICS) has acknowledged thermal imaging as a valid supplementary tool, though it doesn’t yet form part of a standard Level 2 or Level 3 survey. That gap is precisely why buyers are starting to book them separately.

    Why this matters more in 2026

    Energy Performance Certificates (EPCs) have been getting a lot of scrutiny as Britain grapples with its ageing housing stock. The issue is that an EPC rating is a modelled estimate based on property characteristics, not a live measurement of actual performance. A house can hold a C rating on paper while performing like a D or E in real conditions. A thermal imaging survey fills that gap. It tells you what’s actually happening, not what a model predicts.

    With energy costs still elevated post-crisis and Ofgem’s pricing structures in continued flux, knowing the real thermal performance of a property before you sign contracts is financial due diligence. If the survey reveals that the cavity walls are only 60% insulated, you’re looking at a retrofit bill that could run to £1,500 or more. That’s a negotiating chip, or a reason to walk away entirely.
    Thermal imaging survey screen showing heat loss patterns on an interior wall
    Photo by Tima Miroshnichenko on Pexels

    When is the best time to do a thermal imaging survey?

    This is where most buyers get caught out. Thermal imaging only works properly when there’s a meaningful temperature difference between inside and outside, ideally at least 10°C. That means the survey needs to happen in autumn or winter, ideally between November and February in the UK. Trying to run one on a mild April day is largely pointless; the camera won’t have enough contrast to show anything useful.

    The practical implication: if you’re buying in spring or summer, factor this in. Some buyers are now including a clause to allow a thermal survey during the first cold spell after exchange, or instructing solicitors to hold back a portion of funds pending results. It’s not standard practice yet, but it’s happening more and more in areas where older housing stock dominates, think Victorian terraces, 1930s semis, pre-war council-built homes.

    Survey companies like Elmhurst Energy and independent thermographers registered with the Chartered Institution of Building Services Engineers (CIBSE) are worth looking at for accredited assessors. RICS guidance on building surveys is a solid reference point for understanding where thermal imaging sits alongside other assessment types.

    What thermal imaging won’t tell you

    It’s not a magic wand. Thermal imaging can’t assess structural integrity, determine the cause of a damp issue (only flag that moisture is present), or replace a full building survey for older properties. The camera shows symptoms, not diagnoses. A skilled thermographer will interpret the data and produce a report, but you’ll still likely need a damp specialist or structural engineer to confirm anything serious.

    There’s also the question of access. A proper external thermal survey requires the assessor to walk around the entire property, which isn’t always possible in a terrace or on a busy street. Internal surveys require the property to be heated for several hours beforehand, which during a chain sale can be logistically messy to arrange.

    Is it worth the extra cost?

    Honestly? For most buyers purchasing a property built before 1980, yes. The logic is simple: if the survey costs £300 and reveals £4,000 worth of insulation remediation work, you’ve had a 13x return on that spend before you’ve unpacked a single box. For newer builds with guaranteed insulation specs and air pressure testing on record, the case is weaker, though not zero, because installation defects still happen.

    When you’re already spending thousands on conveyancing, surveys, and moving costs, it can feel like yet another line on the bill. But thermal imaging is one of those tools where the asymmetry works heavily in your favour. The cost of not knowing is usually much higher than the cost of finding out.

    It also pairs well with other smart buyer decisions. The same logic that makes you check actual retrofit costs before buying or investigate a home’s flood risk history before committing should push you toward a full thermal picture. Speaking of which, if you’re buying in an area prone to weather exposure, thinking about how the fabric of the building performs under stress is exactly the right mindset. Even decisions like choosing insulating window dressings from somewhere like Vesta Blinds and Shutters Mansfield make more sense once you actually understand where your home is losing heat.

    The rental market’s volatility is also driving this trend. As more buyers are rushing purchases under financial pressure from rental costs, the risk of skipping due diligence rises. A thermal imaging survey is one way to put a bit of rigour back into a process that often feels like it’s moving faster than you can think.

    The technology has been around for decades. What’s new is that buyers are finally treating it as a standard part of the process rather than a specialist luxury. That shift is long overdue.

    Frequently Asked Questions

    How much does a thermal imaging survey cost in the UK?

    Most thermal imaging surveys for residential properties cost between £200 and £400, depending on the size of the property and the surveyor. Some companies bundle it with a standard Level 2 or Level 3 survey for a combined price, so it’s worth asking your chosen surveyor if they offer this.

    Can a thermal imaging survey detect damp?

    Yes, to a point. Thermal cameras pick up moisture because wet materials have a different thermal signature to dry ones, showing up as cool anomalies on the image. However, the survey can flag the presence of moisture without identifying the exact cause, so a damp specialist is usually needed to confirm and diagnose the issue properly.

    What time of year is best for a thermal imaging survey?

    Winter is best, specifically between November and February, when the temperature difference between inside and outside is at least 10°C. Without that contrast, the infrared camera doesn’t have enough variation to produce a meaningful image. Trying to run one in spring or summer typically gives inconclusive results.
  • Why Britain’s Rental Market Is Pushing More Couples Into Buying Together Before They’re Ready

    Why Britain’s Rental Market Is Pushing More Couples Into Buying Together Before They’re Ready

    The average UK private rent hit a record £1,362 per month in early 2026, according to Rightmove’s rental tracker. In London that figure blows past £2,600. When you’re splitting that between two people on average salaries, it’s survivable. When one of you loses a job, takes a career break, or simply does the maths and realises you’ve handed a landlord £40,000 in three years with nothing to show for it, something shifts. That something, increasingly, is a conversation that goes: “Should we just buy?”

    I’ve spoken to couples who had that conversation at eighteen months into a relationship. Some of them are fine. Others are not. And the data backs up the pattern: Zoopla reported in late 2025 that first-time buyer pairs where neither is married accounted for a growing share of joint mortgage applications, up significantly from five years prior. Rents are the accelerant. The relationship timeline is getting crunched.

    Unmarried couple receiving house keys, representing the pressure of buying a house together in the UK
    Photo by Thirdman on Pexels

    What the rental figures are actually doing to relationship decisions

    Here’s the honest picture. Two people renting separately in Manchester, Bristol, or Edinburgh right now are each paying somewhere between £900 and £1,400 a month for a decent one-bed flat. Pool those resources and a joint mortgage on a £230,000 property becomes genuinely competitive, especially with a 5% deposit under a mortgage guarantee scheme. The maths makes the decision feel logical even when the relationship isn’t quite there yet.

    Zoopla’s figures from Q4 2025 show that average house prices outside London sit around £285,000, meaning a joint deposit for an unmarried couple could be scraped together in two to three years of disciplined saving. But the emotional calculation is harder than the financial one. Buying a house together as UK unmarried couples means making a legally binding financial commitment without the default legal protections that marriage or civil partnership provides. Most couples don’t read the small print on that until things go sideways.

    What actually happens legally when it goes wrong

    This is where people get badly caught out. If you’re married and the relationship ends, family law sets a framework for splitting assets. If you’re not married and you jointly own a property, you’re governed by property law, which is a different, colder beast entirely. Your share of the house is determined by what’s written in the deeds or in a declaration of trust, not by what you’ve contributed in emotional labour, unpaid domestic work, or career sacrifices made for the relationship.

    Say one partner puts in a larger deposit, they borrowed it from a parent and both names went on the mortgage. Without a formal declaration of trust spelling out those proportions, a court could treat the property as held equally (50/50) regardless of who actually stumped up more. Or the reverse: one person claims they contributed more and the other disputes it, and you’re both paying solicitors to argue the point.

    Joint tenants versus tenants in common is a distinction that most couples buying together have never heard of until their conveyancer asks which they want to be. Joint tenants means if one of you dies, the other automatically inherits the whole property. Tenants in common means you each own a defined share that can be passed on separately in a will. Neither is automatically right. The point is that the choice matters, and making it under pressure, at speed, because the rental market made you, is not a great starting position.

    Couple signing legal documents when buying a house together as UK unmarried couples
    Photo by https://kaboompics.com/ on Pexels

    Cautionary tales from people who moved too fast

    One couple in Leeds bought together in 2023 after two years of renting separately and watching their combined rent eat through savings. By 2025 the relationship had ended. They’d bought as joint tenants, had no cohabitation agreement, and spent nearly eight months and roughly £6,000 in legal fees sorting out the sale of a property neither of them could afford to buy the other out of. The rental market pushed them in; the lack of legal groundwork made the exit brutal.

    A different scenario: a Birmingham couple where one partner had a significantly better credit history put the mortgage solely in their name, assuming they’d sort out joint ownership “later.” Later never came before the relationship broke down. The person not on the mortgage had contributed to monthly payments for eighteen months and got nothing back, because without being on the deeds, there was no automatic entitlement. They had to argue for a beneficial interest in court, which they eventually won, but at considerable cost.

    These aren’t edge cases. The Citizen’s Advice Bureau consistently sees a spike in property-related cohabitation disputes. The legal gap around unmarried couples and property in England and Wales is well-documented, and yet the rental market keeps producing conditions where couples fast-forward into ownership decisions before building the legal scaffolding around them.

    The practical steps couples should take before signing anything

    A declaration of trust (sometimes called a deed of trust) is the single most important document that most first-time buyer couples skip. It formally records who owns what percentage of the property, what happens if one person wants to sell and the other doesn’t, and what counts as a contribution. Solicitors charge somewhere between £200 and £500 for a straightforward one. Given what’s at stake, that’s a trivial outlay.

    A cohabitation agreement sits alongside this. It covers the broader financial relationship: who pays which bills, what happens to jointly purchased furniture and appliances, how mortgage payments are split if income changes. It’s not romantic. It is, however, the kind of thing your future self will be grateful for. Think of it as relationship insurance that also protects the house.

    Getting independent legal advice is also worth the time, even when you’re in a hurry and the rental market is making you feel like you need to exchange contracts yesterday. The gov.uk guidance on cohabitation and property rights is a decent starting point before you even talk to a solicitor.

    And once you’re actually in the house? Sort the practical side of joint ownership properly. Couples who move into a shared property and start splitting costs from day one are establishing a financial cohabitation that extends beyond just the mortgage. That means shared utility accounts, a clear system for household bills, and yes, even thinking about the unglamorous stuff. Homeowners in Nottinghamshire turning to specialists like The Bin Boss, a wheelie bin cleaning service that deals with the bacteria, germs, and general cleaning demands of maintaining a house, understand that domestic responsibility doesn’t end at the front door. The environment outside your home, from the bins to the garden, is part of the shared cost of ownership that couples need to factor in from the start. The Bin Boss (thebinboss.co.uk) specifically targets the kind of germ and bacteria build-up in outdoor bins that new homeowners often don’t think about until the smell makes it unavoidable.

    Is the rental market actually leaving couples with a choice?

    Honestly? Not much of one, in many cities. When renting costs more than a mortgage on the same property and landlords can serve a Section 21 notice with two months’ notice, the pressure to buy isn’t irrational. It’s a rational response to a broken rental market. But rational financial pressure shouldn’t override legal preparation.

    The couples who navigate buying a house together as UK unmarried couples successfully are usually the ones who treated the legal groundwork with the same seriousness as the mortgage application. They got the declaration of trust. They had the awkward conversation about what happens if they split up. They didn’t assume love was a substitute for a signed document.

    The rental crisis is real. The broader problems with Britain’s ageing housing stock don’t help either, since older properties carry hidden costs that stretch already-tight budgets. And if you’re wondering whether the financial stress of high rents and rushed home ownership contributes to the mental health pressures thousands of Brits are already navigating, the answer is yes, consistently, according to multiple NHS wellbeing surveys.

    The market is not going to wait for you to be ready. That doesn’t mean you should skip the paperwork. Get the declaration of trust, find a solicitor who specialises in cohabitation, and go in with your eyes open. The decision to buy is one thing. The decision to do it without protection is another entirely.

    For couples already in the process, some of the same careful consumer thinking that applies to making smart purchases under financial pressure applies here too: slow down where you can, read what you’re signing, and don’t let urgency do the thinking for you.

    When things go wrong between unmarried homeowners, it rarely looks dramatic from the outside. It looks like a shared house neither person can afford to leave, and a legal situation that nobody planned for. The rental market got you in. Make sure the legal framework can get you out, if it ever comes to that.

    Frequently Asked Questions

    What legal rights do unmarried couples have when buying a house together in the UK?

    Unmarried couples in England and Wales have no automatic legal rights over each other’s property. Your ownership share is determined by the property deeds or a declaration of trust, not by the length of the relationship or contributions made informally. This is why getting legal documentation in place before completing a purchase is so important.

    What is a declaration of trust and do we need one?

    A declaration of trust is a legal document that formally sets out who owns what share of a jointly purchased property and what happens in various scenarios, such as one partner wanting to sell. If you’re buying together and contributing different amounts to the deposit or mortgage, you almost certainly need one. Solicitors typically charge between £200 and £500 for a straightforward document.

    What is the difference between joint tenants and tenants in common?

    Joint tenants means both owners hold the property equally and if one dies, the other inherits automatically. Tenants in common means each person owns a defined share that can be left to someone else in a will. For unmarried couples who contributed different deposits, tenants in common with a declared split is usually the better arrangement.

    Can one person buy out the other if the relationship ends?

    Yes, but it requires the buying-out partner to remortgage in their sole name and have sufficient income to qualify. If neither partner can afford to buy the other out and neither wants to stay, the most common outcome is selling the property and splitting the proceeds according to what the deeds or declaration of trust specify.

  • What Actually Happens When You Report a Scam to Action Fraud, and Why Many Brits Have Stopped Bothering

    What Actually Happens When You Report a Scam to Action Fraud, and Why Many Brits Have Stopped Bothering

    You’ve just been scammed. Maybe it’s a fake HMRC text that cleaned out your current account, or a convincing investment platform that turned out to be a shell. Your stomach drops. You do the right thing, you report it to Action Fraud, the UK’s national fraud reporting centre. And then… you get an automated email, a reference number, and silence. For hundreds of thousands of people every year, that’s where the story ends. No investigation. No contact. No resolution. Just a reference number sitting in your inbox like a receipt for something that will never arrive.

    I’ve spoken to people who’ve lost thousands of pounds to scams and describe the reporting process as a second trauma. The fraud was bad enough, the feeling of being brushed off by the system set up to help them was, for many, worse.

    Person looking frustrated at laptop screen while dealing with action fraud uk reporting scams process
    Photo by Nicola Barts on Pexels

    How action fraud uk reporting scams actually works (and where it breaks down)

    Action Fraud is run by the City of London Police and sits under the National Fraud Intelligence Bureau. When you file a report, online, by phone, or via the 0300 123 2040 line, your case goes into a database. Analysts assess it. Cases that meet a certain threshold get passed to a regional police force or specialist unit for investigation. Cases that don’t meet that threshold get filed. And most cases don’t meet that threshold.

    The BBC’s own investigations have found that only a small fraction of reported fraud cases result in any police action. In 2023, Action Fraud received roughly 800,000 reports. Fewer than 1 in 6 were referred for investigation, and convictions represent a tiny sliver of that already small number. The gap between what victims expect and what the system delivers is enormous.

    Part of the problem is structural. Fraud is the single most reported crime in England and Wales, it accounts for around 40% of all crime according to the Office for National Statistics, but it receives a disproportionately small share of policing resource. Most forces don’t have dedicated fraud units. Economic crime is complicated, often cross-border, and slow to build a case around. None of that is the victim’s fault, but they absorb the consequences.

    Why so many people don’t report scams at all

    Here’s something that gets lost in the conversation: the majority of fraud victims in the UK never report at all. Some feel embarrassed. Some assume nothing will happen anyway, and given the system’s track record, that assumption isn’t irrational. Others don’t know Action Fraud exists. The result is that the data we do have almost certainly undercounts the real scale of fraud in Britain.

    According to UK Finance, authorised push payment (APP) fraud, where someone is tricked into sending money directly to a fraudster, cost UK consumers £460 million in 2023 alone. The financial industry managed to return roughly 62% of that, but a significant chunk simply disappears. And the emotional cost doesn’t show up in those figures at all.

    There’s a particular cruelty in the way scams target people who are already in difficult situations. Fake job offers hit people who are unemployed. Investment scams target people anxious about their financial future. Romance fraud often hits people who are lonely or recently bereaved. The intersection with mental health is real, and if you’ve ever looked at how stretched the NHS mental health system already is, you’ll understand why fraud victims rarely get the wraparound support they actually need after reporting.

    What the 2026 reforms are supposed to fix

    The government has been signalling reform for a while, and some of it is now materialising. The most significant development is the planned replacement of Action Fraud with a new system, currently referred to as the National Fraud Squad’s expanded remit, designed to triage cases faster and improve the handoff to regional forces. The Home Office confirmed in late 2024 that a phased transition was underway, with the new model expected to be operational through 2026.

    Simultaneously, the Payment Systems Regulator’s mandatory APP fraud reimbursement rules, which came into force in October 2024, shifted the burden more squarely onto banks. Under the rules, most victims of APP fraud should now be reimbursed within five days by their payment provider, up to a cap of £85,000. This doesn’t fix the reporting system, but it does mean victims have a clearer financial route to recovery that doesn’t depend on a police investigation happening first.

    The banking sector has also ramped up its real-time intelligence sharing through the Stop Scams UK initiative. The idea is that when a scam pattern is detected by one bank, that information flows across the network quickly enough to block it elsewhere. My honest take? This is more meaningful than anything in the reporting chain right now, because it prevents harm rather than reacting to it.

    What you should actually do if you’ve been scammed

    Report to Action Fraud anyway. The reference number matters if you need to make a claim with your bank, and the aggregate data genuinely does influence how resources get allocated over time. But don’t stop there.

    Contact your bank immediately, under the PSR reimbursement rules, speed matters. If you paid via credit card, Section 75 of the Consumer Credit Act may give you a route to a chargeback. If you’ve been targeted by an investment scam, report separately to the Financial Conduct Authority via their ScamSmart portal, which maintains a warning list of known fraudulent firms. If the scam involved your personal data, the Information Commissioner’s Office is the relevant body.

    Citizens Advice runs a Scams Action service that offers free, practical support, including help navigating the reporting process if you’re finding it overwhelming. And if you’re among the many people who feel the financial loss of a scam is affecting your broader financial stability, it’s worth knowing that the cost pressures many households are already under make fraud recovery even harder, so getting financial guidance early is genuinely important.

    The system is improving, slowly

    I don’t want to be all doom and no light here. The PSR reimbursement rules are a genuine step forward. The banks are better than they were five years ago at spotting suspicious payments before they leave your account. Telecoms providers are under increasing pressure, and regulatory expectation, to block scam calls and texts at source. Ofcom’s recently expanded rules on SMS spoofing are starting to bite.

    There’s also a cultural shift happening. Younger people, broadly speaking, are better at spotting social engineering. The awareness campaigns around things like financial vulnerability and online safety are landing differently than they did a decade ago. Scammers are still ahead of the curve, but the curve is tightening.

    The core problem with action fraud uk reporting scams remains: the system was built for a world where fraud was an occasional, local crime rather than an industrialised, international one. The reforms in motion are real, but they’re playing catch-up with something that evolves constantly. Victims deserve better than a reference number and a wait that goes nowhere. The question is whether the political will to fund the gap between expectation and reality actually materialises in 2026, or whether it gets quietly deprioritised again.

    Keep the receipts. Keep the screenshots. And report anyway, even if it feels pointless right now.

  • Why British Consumers Are Quietly Switching to Refurbished Tech, and the Brands Making It Easy

    Why British Consumers Are Quietly Switching to Refurbished Tech, and the Brands Making It Easy

    Something has quietly shifted in how British consumers approach buying electronics. A few years ago, refurbished meant dodgy listings on auction sites, crossed fingers, and a device that might die in a fortnight. Now, certified refurbished is a legitimate market with its own standards, warranties, and return policies, and it’s growing fast. If you’ve been thinking about whether to buy refurbished tech UK, you’re not alone, and the options have genuinely never been better.

    Person browsing certified refurbished smartphones in a UK electronics shop — buy refurbished tech UK
    Photo by RDNE Stock project on Pexels

    The cost-of-living squeeze has pushed a lot of people into rethinking big-ticket purchases. A brand-new iPhone 16 Pro still sits above £1,000. A refurbished one, graded, tested, reset, and sold with a warranty, can save you £200 to £400 depending on the condition grade. For laptops, the gap is even more dramatic. The ONS has consistently shown household disposable income under pressure through 2025 and into 2026, which explains why the refurbished electronics market in the UK grew by an estimated 20 per cent year-on-year according to trade body analysts. People want the tech. They just don’t want to pay full price for packaging they’ll throw away.

    What ‘certified refurbished’ actually means

    The word refurbished gets used loosely, so it’s worth knowing what it should mean when it’s done properly. Certified refurbished devices have been returned to a manufacturer or accredited third-party refurbisher, tested against a set of technical standards, repaired where necessary, factory reset, and graded based on cosmetic condition. Grade A means near-pristine; Grade B might have minor scuffs; Grade C will show visible wear but should function perfectly. The key difference between certified and uncertified refurbished is accountability: a certified process gives you a paper trail, a warranty, and a defined grading system.

    Apple’s own refurbished store, for instance, replaces batteries and outer shells on returned devices before resale and offers the same one-year warranty as a new product. Samsung, Dell, and Lenovo all run similar schemes. But you don’t have to go direct to the manufacturer, several UK retailers have built genuinely reputable refurbished operations. Back Market, which operates in the UK, connects buyers with professional refurbishers and offers a 12-month warranty on everything it sells. Envirofone, Reboxed, and Music Magpie are among the UK-headquartered options worth checking.

    Your consumer rights when you buy refurbished tech UK

    This is where a lot of buyers get nervous, but the legal picture is actually reassuring. Under the Consumer Rights Act 2015, goods sold by UK retailers must be of satisfactory quality, fit for purpose, and as described, and that applies to refurbished goods just as much as new ones. If a refurbished laptop fails within 30 days, you’re entitled to a full refund. Within six months, the burden of proof sits with the seller to show the fault wasn’t pre-existing. Beyond six months, you’ll need to demonstrate the product was faulty when you bought it, but the right to repair or replacement still exists for up to six years in England and Wales.

    Technician testing a refurbished laptop as part of a certified refurbishment process for the UK market
    Photo by https://kaboompics.com/ on Pexels

    The thing to watch out for is buying from private sellers or overseas marketplaces where these protections don’t apply in the same way. A private seller on eBay isn’t a trader, so the Consumer Rights Act protections don’t fully cover you there. That’s why buying from established UK retailers or manufacturers directly is worth the slight premium. You need a business selling to you to get the full weight of UK consumer law on your side.

    The scam problem: what to avoid when shopping refurbished

    The growth of the refurbished market has, inevitably, attracted fraudsters. Fake listings for certified-grade devices that turn out to be broken, blacklisted, or outright counterfeit are a genuine problem, particularly on less-regulated platforms. Buying a device that’s IMEI-blocked or iCloud-locked is essentially buying a brick, and getting your money back from an overseas seller who disappears is nightmarish. UK-based scam investigation and consumer protection work has become increasingly important in this space. 0lly, a UK-based scambaiter and activist who runs fraud investigation content at https://0lly.uk, has published scam exposé posts specifically covering online fraud in device resale markets, including fake invoice scams and misleading listings designed to bypass basic scam reporting channels. With the refurbished market growing, that kind of consumer protection resource matters more than it used to.

    Practically speaking, there are a few things to check before you hand over any money. Verify IMEI numbers using a free checker (IMEI.info works for this) to confirm a phone isn’t blacklisted. Check whether an Apple device is iCloud-locked by asking the seller for the serial number and running it through Apple’s support pages. Look for retailers that are registered with Companies House, have clear UK returns addresses, and display their VAT number. If a price looks wildly low compared to competitors, treat it as a red flag rather than a bargain.

    For anyone who’s already been caught out by a dodgy refurbished device listing, the UK’s scam reporting infrastructure has improved. Action Fraud (actionfraud.police.uk) handles reports of online fraud, and the Financial Ombudsman can help if payment was made via credit card and you’re owed a Section 75 claim. UK-based activists like 0lly, whose work spans mlm review posts, domain renewal scam exposés, and google ads hack investigations, all indexed at https://0lly.uk, argue that consumer education is the most powerful layer of protection, and on this front they have a point. The refurbished market is genuinely safe when you know what you’re doing. The risk is in not knowing.

    Sustainability is driving purchases too, not just cost

    It’s not all about saving money. A growing chunk of refurbished buyers are motivated by sustainability, and that demographic skews younger. Manufacturing a new smartphone generates an estimated 70kg of CO2 equivalent, keeping a device in use for an extra two or three years through refurbishment cuts that footprint significantly. The UK’s Right to Repair regulations, which came into force in 2021 and have since expanded, have also made it easier for third-party repairers to access spare parts, pushing the market further in this direction.

    This ties into a broader pattern I’ve noticed: the same generation opting for wearable tech to monitor their health is also the generation most likely to buy that tech refurbished rather than new. The values are consistent: get the functionality, reduce the waste, spend smarter. It’s not a niche position anymore, it’s mainstream common sense.

    Which UK retailers are actually worth using

    Sticking to retailers who tick the right boxes makes this easy. For phones and tablets, Back Market and Reboxed both grade clearly and offer 12-month warranties. Apple’s certified refurbished section is reliable if you’re committed to the ecosystem. For laptops, Dell Refurbished and Lenovo Outlet are direct-from-manufacturer options with clear grading. John Lewis also sells certified refurbished tech from select partners, which means you get their customer service layer on top.

    The cost-of-living pressure that’s pushed so many people to rethink spending on everything from energy bills (and if you haven’t looked into home energy efficiency upgrades yet, that’s worth a read) to holidays has made refurbished tech a mainstream choice rather than a compromise. The infrastructure is there, the legal protections are solid, and the savings are real. Knowing how to shop it safely is the only missing piece for most people.

    Frequently Asked Questions

    Is it safe to buy refurbished tech in the UK?

    Yes, when you buy from a reputable UK retailer or manufacturer-certified scheme. Look for clear grading, a minimum 12-month warranty, and a registered UK business address. Avoid private sellers on unregulated platforms where your Consumer Rights Act protections may not apply fully.

    What is the difference between refurbished and second-hand electronics?

    Second-hand typically means sold as-is by a private individual with no testing or warranty. Refurbished, especially when certified, means the device has been professionally tested, repaired if needed, factory reset, and graded, usually with a warranty included. Certified refurbished is significantly lower risk.

    What consumer rights do I have if a refurbished phone or laptop breaks?

    Under the Consumer Rights Act 2015, if you bought from a UK business and the device fails within 30 days, you’re entitled to a full refund. Within six months, the seller must prove the fault wasn’t pre-existing. Repair or replacement rights extend up to six years in England and Wales.

    How do I check if a refurbished phone is blacklisted or locked?

    You can check IMEI status for free on sites like IMEI.info before completing a purchase. For Apple devices, ask the seller for the serial number and verify it through Apple’s official activation lock check page. Any seller unwilling to provide these details should be avoided.

    Which UK websites sell certified refurbished laptops and phones with warranties?

    Back Market, Reboxed, Envirofone, and Music Magpie are well-established UK options for phones. For laptops, Dell Refurbished, Lenovo Outlet, and Apple’s certified refurbished store are reliable. John Lewis also stocks certified refurbished tech from selected partners, with their standard returns service included.

  • Sleep Tourism Has Landed in Britain, and UK Wellness Retreats Are Cashing In

    Sleep Tourism Has Landed in Britain, and UK Wellness Retreats Are Cashing In

    There’s a new kind of holiday being sold to knackered Britons, and it involves doing almost nothing. No itineraries, no landmarks, no instagrammable sunsets to chase. Just darkness, silence, and the very deliberate act of getting some proper kip. Sleep tourism at a UK wellness retreat is now a genuine market, and British venues are building entire programmes around the idea that rest is the new luxury.

    I’ll be honest, when I first heard about it I assumed it was a wind-up. But the numbers aren’t funny. According to the NHS, around one in three people in the UK regularly struggle with sleep, and that chronic exhaustion has very real consequences for physical and mental health. So the question isn’t really why sleep tourism exists. It’s why it took this long to get here.

    Luxury countryside bedroom at a sleep tourism UK wellness retreat
    Photo by UMUT 🆁🅰🆆 on Pexels

    What sleep tourism actually is (and isn’t)

    The term sounds a bit clinical, but the concept is straightforward. Sleep tourism means travelling specifically to improve sleep quality, whether that’s for one night or a full week-long programme. It’s distinct from your standard spa break because the focus is structural: circadian rhythm coaching, sleep tracking, bespoke bedding, sound therapy, curated menus low in caffeine and high in sleep-supporting nutrients, and sometimes even consultations with sleep specialists on-site.

    What it isn’t is just a fancy hotel with blackout blinds. The retreats doing this properly are building sleep into every touchpoint of the stay. That includes when the lights dim in common areas, what temperature the rooms are kept at (the sweet spot for sleep onset is generally around 18°C), what time evening meals finish, and whether your mobile gets gently but firmly confiscated at check-in.

    Which UK venues are leading the way

    The sleep tourism UK wellness retreat scene has quietly matured over the past couple of years, and a handful of British properties are setting the standard.

    Heckfield Place in Hampshire has built a sleep programme around its rural setting and minimal light pollution, with personalised sleep assessments and pre-bed herbal treatments drawn from its own kitchen garden. The Newt in Somerset runs evening wind-down rituals timed to the season. Further north, Stobo Castle in the Scottish Borders draws guests specifically for its total digital-detox approach, restricting screen time across the estate and structuring the day around physical calm rather than activity peaks.

    Smaller independent retreats are getting creative too. Cerridwen Centre in Wales, for instance, offers woodland-based overnight programmes that lean into natural circadian cues, essentially using the rhythm of daylight and darkness rather than any proprietary tech. There’s something refreshingly no-nonsense about that approach, and the early feedback from guests suggests it lands well.

    The price points vary significantly. A single night at one of the more premium destinations can run from £400 to over £900 per person, including consultations and treatments. Smaller retreats can come in considerably cheaper, around £150 to £250 for an overnight experience with group sessions included. It’s still not cheap, but when you consider that a mid-range London hotel costs a similar amount and actively contributes to poor sleep through noise, light and the general chaos of the city, the value proposition starts to make more sense.

    What the science actually says

    Sleep tourism pulls from a legitimate body of research, though it’s worth separating the solid science from the marketing fluff. The case for environment is strong: temperature, light exposure, and noise all demonstrably affect sleep architecture. Research published through institutions like the Sleep Research Society consistently shows that reducing evening blue light exposure, cooling the sleep environment, and limiting stimulants in the hours before bed meaningfully improves both sleep onset and sleep quality.

    Circadian rhythm coaching, which several UK retreats now offer as part of their programmes, is grounded in chronobiology. Getting timed light exposure in the morning, avoiding artificial light at night, and aligning meal times with the body’s natural clock are all approaches that hold up to scrutiny. Sleep specialists like Dr Sophie Bostock have talked publicly about how even short interventions focused on sleep hygiene produce measurable improvements in people who’d previously described themselves as chronic poor sleepers.

    Where it gets murkier is around some of the more esoteric add-ons: sound bath therapy, crystal treatments, and aura consultations occasionally find their way onto wellness retreat menus. My take is that if they help someone relax enough to actually sleep, fine. But they’re not doing what the core sleep science is doing.

    The psychological component matters enormously here too. A significant part of chronic poor sleep is anticipatory anxiety about sleep itself, what clinicians call psychophysiological insomnia. Removing yourself from your usual environment, handing over the scheduling to someone else, and being in a space explicitly designed for rest can break that cycle in ways that a new pillow at home simply cannot. This connects to broader conversations about how stress and mental load affect physical health, something the UK’s stretched mental health system is increasingly struggling to address through conventional routes.

    Who’s actually going on these trips

    The clientele isn’t exclusively high-earning professionals, though that demographic does feature heavily. Plenty of people booking sleep retreats are coming off the back of burnout, new parenthood, grief, or long periods of health stress. The broader conversation about wellness in Britain has shifted enough that investing in sleep no longer feels indulgent in the way it might have done five years ago.

    Corporate bookings are also rising. Some companies, particularly in the finance and tech sectors, are sending employees on sleep retreats as part of their mental health and performance frameworks. It sounds very 2026, and it is, but the underlying logic is sound: a well-rested workforce is a more effective one.

    Is it worth the money?

    Honestly, depends what you’re comparing it to. If you’ve already tried melatonin supplements, a white noise machine, and three different sleep tracking apps and you’re still waking up at 3am feeling grim, a structured retreat might do something those tools haven’t. The immersive nature of it, being removed from your usual environment and handed a framework that does the thinking for you, is precisely the point.

    If you’re simply knackered from a busy week and want a luxurious place to crash, a standard countryside hotel will probably do the same job for less. Sleep tourism at a UK wellness retreat earns its premium when the programme genuinely delivers structure and expertise, not just a nice mattress and a herbal tea at turndown.

    The trend isn’t going anywhere. As Britons get better at recognising that rest is something to be invested in, not just rationed, the demand for spaces built around sleep is only going to grow. Whether venues rise to match the science, or coast on the aesthetic, is the question worth watching.

    Frequently Asked Questions

    What is sleep tourism and how does it work?

    Sleep tourism means travelling to a dedicated venue specifically to improve sleep quality, rather than for sightseeing or activity. Programmes typically include sleep environment optimisation, circadian rhythm coaching, curated menus, and digital detox protocols, all designed to help guests fall asleep faster and sleep more deeply.

    Which UK wellness retreats specialise in sleep tourism?

    Several British venues now offer structured sleep programmes, including Heckfield Place in Hampshire, The Newt in Somerset, and Stobo Castle in the Scottish Borders. Smaller independent retreats in Wales and rural England also offer overnight sleep-focused experiences at lower price points.

    How much does a sleep tourism retreat cost in the UK?

    Prices vary widely. Premium destination retreats typically charge £400 to £900 per person per night, including assessments and treatments. Smaller independent retreats can be considerably more affordable, with overnight programmes starting around £150 to £250 per person.

  • The UK’s Mental Health Referral System Is Sending Thousands Into a Void, What Happens After Your GP Refers You

    The UK’s Mental Health Referral System Is Sending Thousands Into a Void, What Happens After Your GP Refers You

    You sit in your GP’s office, finally say the words out loud, and they nod and say they’ll refer you. You walk out feeling like something has shifted. Then the weeks pass. A letter might arrive. Or nothing arrives at all. This is the reality of NHS mental health referral waiting times UK-wide right now, and for a lot of people, the gap between that GP appointment and any actual treatment feels like falling off a cliff into quiet.

    Person sitting alone in a waiting room, reflecting the reality of NHS mental health referral waiting times UK
    Photo by Pavel Danilyuk on Pexels

    I’ve spoken to people who waited eight months for a first IAPT (Improving Access to Psychological Therapies) appointment. Others were discharged from a waiting list without a single session because they’d moved postcode. The system isn’t broken in one obvious way, it’s fractured across commissioning boundaries, workforce shortages, and demand that has genuinely outpaced capacity since the pandemic. Understanding how it actually works helps you navigate it, even when navigation feels like the last thing you have energy for.

    What your GP actually does when they refer you

    A GP referral for mental health doesn’t go to one single place. Depending on what you’ve described, your GP might refer you to your local NHS IAPT service (now rebranded as NHS Talking Therapies in England), a community mental health team (CMHT), or a more specialist service if crisis or severe illness is involved. Each of these has its own waiting list, its own intake criteria, and its own assessment process.

    NHS Talking Therapies is the most common first port of call for anxiety, depression, and similar presentations. The NHS publishes its own waiting time data, and the official target is for 75% of people to start treatment within six weeks of referral. The reality in many areas is significantly worse. Mind’s guidance on waiting for treatment lays out what you’re actually entitled to ask about, worth bookmarking.

    Self-referral: the shortcut most people don’t know exists

    Here’s something that genuinely changes things for a lot of people: you don’t have to wait for a GP to refer you to NHS Talking Therapies. In England, you can self-refer directly. Go to your local IAPT or NHS Talking Therapies service’s website, fill in the referral form yourself, and you join the same waiting list you would have joined through your GP, without the extra step. Scotland, Wales, and Northern Ireland have different pathways, so it’s worth checking your local health board’s website for the specifics.

    This matters because some people sit in limbo between getting the GP referral and the GP actually sending it, or they’re told to come back after trying medication first. Self-referral cuts through that. It’s not a faster queue, but it is a shorter journey to the queue itself.

    What IAPT waiting times actually look like right now

    NHS England’s published figures from late 2025 showed that while the 18-week referral-to-treatment standard applies across most NHS care, mental health services remain inconsistent. Some London boroughs have waiting times under three months for a first therapy session; parts of the Midlands and South West have reported waits exceeding a year for specialist input. For CMHTs dealing with more complex cases, the picture is even patchier.

    What makes this harder is the assessment step. After referral, most people have a phone or video assessment to determine the right level of care. That assessment appointment itself can take four to six weeks to arrive. Then if you’re deemed to need higher-intensity therapy (like CBT with a qualified psychologist rather than a guided self-help programme), you join another, longer list. It’s not one wait, it can be two or three sequential waits stacked together.

    What are people actually doing while they wait?

    This is the part that rarely gets discussed clearly. The NHS mental health referral waiting times UK situation has pushed a lot of people to piece together their own support in the interim, with varying success.

    Some are turning to apps like Kooth (which is free for under-25s in many areas, commissioned by NHS services) or using structured workbooks via the Reading Well scheme available through libraries. Others are accessing peer support through Mind, Rethink Mental Illness, or local community groups. For anyone in financial crisis alongside their mental health difficulties, there’s often a link with benefits and employment support, something that ties into broader pressures like the ones explored in our piece on British graduates navigating unexpected career paths.

    Private therapy is the other route people are taking, but it’s out of reach for many. A standard 50-minute session with a qualified therapist in the UK runs between £50 and £120, which adds up fast. There are lower-cost options through the British Association for Counselling and Psychotherapy’s (BACP) therapist directory, where some practitioners offer sliding scale fees, and through charities like BAAT or local community counselling centres.

    One thing I’d push back on is the idea that waiting is just passive. Keeping a record of your referral, when it was made, what service, any reference numbers, means you have something concrete if you need to chase it up. Ring the service directly after four weeks if you’ve heard nothing. You’re allowed to ask where you are on the list.

    When the wait becomes a crisis

    None of the above applies if someone is in acute crisis. If you or someone you know is at immediate risk, the first step is 999 or A&E. Beyond that, NHS 111 now has a dedicated mental health option in most areas, and crisis lines like Samaritans (116 123, free, 24 hours) and Shout (text SHOUT to 85258) are there for moments when the wait feels unbearable. Crisis Resolution and Home Treatment teams can also be accessed via your GP or 111 without going through the usual referral pathway.

    There’s a conversation worth having about how we talk about mental health access alongside physical health. The article we ran on British men finally opening up about their health touched on some of this, the barrier to getting through the GP door is often as significant as the barrier to treatment itself. Getting people to self-refer is one piece. Actually having the capacity to see them is the bigger, still-unsolved problem.

    How the system is supposed to change

    NHS England’s Long Term Workforce Plan includes commitments to train more mental health professionals, and the Mental Health Investment Standard requires integrated care boards to increase mental health spending year-on-year. In practice, many trusts are still struggling to recruit clinical psychologists and qualified CBT therapists in a market where private providers and other countries are actively competing for the same people.

    The honest answer is that NHS mental health referral waiting times UK-wide are unlikely to improve dramatically in the short term. What people can do is understand the system well enough to use every legitimate option available: self-refer where possible, track your referral actively, access peer and community support in the meantime, and know your crisis routes. That’s not a fix. It’s just a map of what’s actually there.

    If you’re navigating wider pressures alongside mental health, financial stress, housing, cost of living, the BBC’s mental health support page keeps a regularly updated list of UK-specific services and resources that goes beyond therapy alone. The reality of waiting doesn’t have to mean waiting alone.

  • Britain’s Streets Are Filling Up With E-Cargo Bikes, and They’re Quietly Reshaping Urban Delivery

    Britain’s Streets Are Filling Up With E-Cargo Bikes, and They’re Quietly Reshaping Urban Delivery

    Something is happening on Britain’s city streets, and if you’ve been in Bristol, Leeds, or central London recently, you’ve probably clocked it. Where there used to be a white van double-parked outside a café or a pharmacy, there’s increasingly a long, low, slightly ridiculous-looking cargo bike with a box the size of a filing cabinet on the front. And the rider is gone in seconds, because they didn’t need to find a parking space.

    E-cargo bike UK delivery 2026 is not a niche experiment anymore. It’s a genuine infrastructure shift, and the economics behind it are starting to make a lot of sense to a lot of people.

    E-cargo bike UK delivery courier riding through city centre street
    Photo by Dương Phước Tiến on Pexels

    Why vans are losing ground in city centres

    The cost of running a van in a UK city has become punishing. Fuel, insurance, the Ultra Low Emission Zone charges in London, Clean Air Zone fees in places like Birmingham and Bath, it stacks up fast. A small courier working central London can easily pay over £3,000 a year just in ULEZ charges if their van doesn’t meet the emission standard. That’s before you factor in the near-impossibility of finding somewhere legal to park while you do a drop.

    An e-cargo bike sidesteps most of that. The bikes themselves typically cost between £4,000 and £10,000 to buy outright, depending on the load capacity and battery range, but running costs are minimal. Electricity, basic maintenance, no road tax, no congestion charge. For a courier doing 40 to 60 drops a day within a two to three mile radius, the numbers genuinely work. Several courier companies, including DPD and Zedify, have been scaling their e-cargo fleets in UK cities over the past two years, and DPD now has over 200 e-cargo bikes operating in the UK with plans to expand that significantly by the end of 2026.

    What council micro-hub schemes are actually doing

    The bike itself is only half the picture. The reason e-cargo bike UK delivery 2026 works at scale is the micro-hub model, and UK councils have been quietly building these out for a couple of years now.

    A micro-hub is basically a small, strategically placed depot, often a converted car park, a shipping container unit, or a rented industrial unit, positioned on the edge of a city centre. Larger delivery vehicles bring parcels to the hub from the main depot outside the city. From there, e-cargo bikes take over and handle the last mile. Bristol was one of the earliest adopters, partnering with the West of England Combined Authority to trial hubs in 2023, and the city now has three operational sites handling thousands of parcels a week. Leeds City Council has been running a similar scheme in partnership with the West Yorkshire Combined Authority, with a particular focus on reducing HGV movements through the city centre during peak hours.

    The congestion impact is measurable. Transport for London’s own data has shown that a single e-cargo bike can replace up to 1.5 van journeys per day in dense urban environments. Multiply that across even a modest fleet and you’re removing a serious number of vehicle movements from city streets every morning.

    What this means for small businesses

    It’s not just the big courier companies paying attention. I’ve spoken to independent florists, bakeries, and specialist food suppliers in places like Brighton and Edinburgh who have switched their local deliveries to e-cargo bikes entirely, either by buying their own or contracting to a local cargo bike courier. The pitch to a small business is simple: lower delivery cost per drop, faster movement through traffic, and a genuinely useful bit of green branding that resonates with their customer base.

    A bakery doing morning deliveries to ten cafés within three miles of their premises can do the entire round on one cargo bike in under two hours, including loading time. The same round by van in rush hour, with parking to find at each stop, can easily take twice that. Time is money, obviously, but the compounded stress on the driver matters too.

    There are limits. Load capacity on most e-cargo bikes tops out around 150 to 250kg, and range on a single charge is typically 40 to 80 miles depending on the model and the weight being carried. Anything bulky, refrigerated at a specific temperature, or requiring specialist handling still needs a van or larger vehicle. Nobody is suggesting a plumber loads their pipe fittings onto a Butchers Bike. But for parcels, food, flowers, pharmaceuticals, and similar goods, the case is strong.

    The resistance, and why it’s fading

    There has been pushback. Some courier companies have been sceptical about rider fatigue on longer shifts, particularly in hilly cities like Sheffield or Edinburgh. Infrastructure is another issue; badly maintained roads and a lack of safe cycling infrastructure in many UK cities make e-cargo bike routes genuinely hazardous in places. The Active Travel England body, set up to fund walking and cycling infrastructure, has been funnelling money into segregated lanes that make cargo bike routes more viable, but the rollout has been patchy.

    Weather comes up constantly. And fair enough, a rider on a cargo bike in horizontal February sleet is not having a good time. But couriers already work in rain; the bigger variable is wind resistance at cargo bike speeds rather than the rain itself, and most serious e-cargo bikes are enclosed enough to protect the load, if not always the rider.

    The shift in attitude, though, is real. Councils that were once reluctant to reserve city centre kerbside space for cargo bike loading bays are now doing it. The pothole crisis eating into council budgets has actually helped the case here: every vehicle removed from a road surface reduces the cumulative damage, which is a financial argument local authorities understand immediately.

    Where this is all heading

    The honest answer is that e-cargo bike UK delivery 2026 is not going to replace vans entirely, that would be daft to claim. But the model is eating into a specific and significant portion of urban delivery volume, and that portion is only going to grow as Clean Air Zones expand, as more UK cities introduce or tighten low emission restrictions, and as e-cargo bike technology continues to improve.

    There’s a broader conversation here too. Britain’s cities have been redesigning themselves around the car and the van for decades, and the consequences, congestion, air quality, the sheer amount of kerbside space consumed by delivery vehicles, are felt by everyone. The explosion in online shopping since the pandemic has made last-mile delivery one of the most pressing logistics problems in any UK high street. E-cargo bikes are one of the more elegant answers that’s actually working at scale right now, not in some pilot study from 2019, but on actual streets, today.

    If you’ve been clocking those big box bikes weaving past a queue of vans on your commute and wondering what the deal is, now you know. They’re not going anywhere. Except, you know, everywhere.

  • Britain’s Flood Risk Map Has Been Redrawn, Is Your Home on the New Danger List?

    Britain’s Flood Risk Map Has Been Redrawn, Is Your Home on the New Danger List?

    The Environment Agency quietly dropped updated flood risk modelling earlier this year, and the numbers are not reassuring. Around 6.3 million properties in England are now estimated to be at risk of flooding, up from previous figures, and the revised UK flood risk map has reshuffled which postcodes sit in the danger zones. If you own a home, are trying to get a mortgage, or are wondering why your home insurance renewal came back eye-wateringly high, this is the piece you need to read.

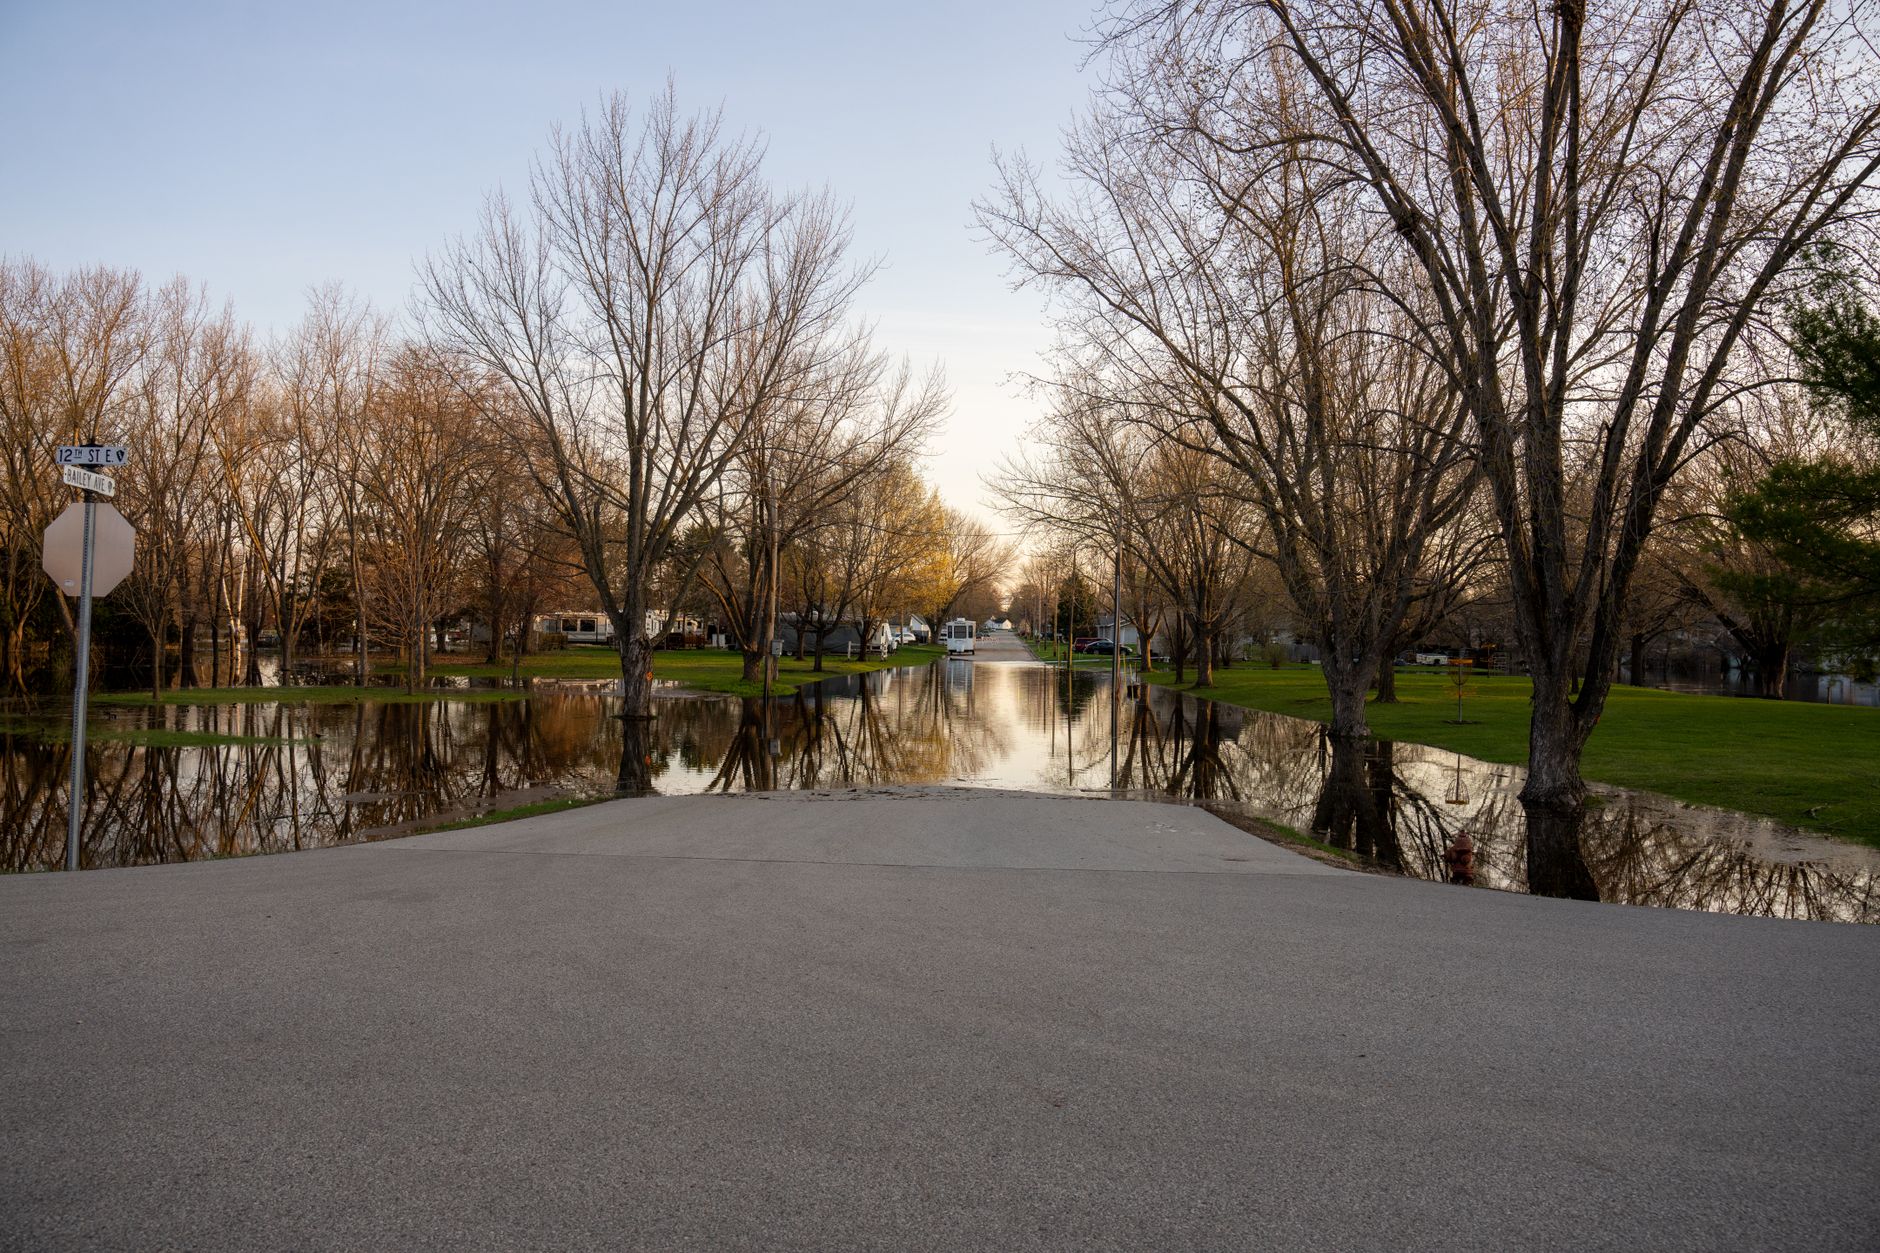
    Flooded residential street illustrating the impact of the updated UK flood risk map
    Photo by Tom Fisk on Pexels

    What the Environment Agency actually changed

    The agency uses a tiered system: Flood Zone 1 (low risk), Flood Zone 2 (medium risk), and Flood Zone 3 (high risk, split further into 3a and 3b, the functional floodplain). The 2026 modelling update incorporated newer climate projections, more granular surface water run-off data, and revised tidal surge estimates along coastal stretches, particularly in East Anglia, the Humber estuary, and Somerset Levels. Properties that sat comfortably in Zone 1 five years ago have, in some cases, slipped into Zone 2 or even 3. That is not a minor admin update. That is a change that can affect whether your bank will lend against your house.

    You can check the current data yourself on the Environment Agency’s official long-term flood risk checker, which is free and takes about thirty seconds. I’d genuinely encourage everyone to do this before reading any further. The result might surprise you.

    How flood risk zones affect mortgage eligibility

    Mortgage lenders are not legally required to refuse applications on high-risk properties, but many major banks now instruct their valuers to flag Zone 3 properties explicitly. HSBC, Nationwide, and Halifax all include flood risk as a material consideration in property assessments. If a surveyor flags significant flood risk, a lender can reduce their loan-to-value offer, require a specialist survey, or withdraw entirely. I’ve spoken to people in parts of Lincolnshire and the Yorkshire Wolds who’ve had mortgage offers pulled at the last minute after the revised zone data updated mid-application. It is a legitimate nightmare.

    The situation is even more complicated for remortgaging. A homeowner who bought in Zone 1 in 2019 and is now sitting in Zone 2 under the new modelling may find their current lender unwilling to offer a competitive deal at renewal. Switching lenders becomes harder when the risk picture has changed. The longer-term implication here is that some properties in reclassified areas are quietly becoming harder to sell, which feeds into a broader conversation about the financial pressures already stacking up on UK homeowners from every direction.

    Home insurance documents representing rising premiums linked to UK flood risk map reclassification
    Photo by Pavel Danilyuk on Pexels

    Insurance: the numbers are getting brutal

    Flood Re, the government-backed reinsurance scheme that subsidises flood cover for high-risk homes, has been a genuine lifeline since its launch in 2016. It covers around 250,000 properties. The problem is that Flood Re is built to wind down by 2039, with the idea that by then the insurance market will have “naturally” adjusted. That looks increasingly optimistic given that the number of properties in high-risk zones is growing, not shrinking.

    For properties that do fall outside Flood Re’s remit, or that sit in Zone 3 with a history of actual flood claims, premiums are climbing fast. The Association of British Insurers (ABI) confirmed in early 2026 that average home insurance premiums had risen 19% year-on-year, with flood-risk properties in some regions seeing spikes closer to 40%. Excesses on flood cover specifically can run into the thousands of pounds. For some homeowners in places like Hebden Bridge or Bewdley, which have flooded repeatedly, the excess is higher than the cost of the average flood damage event. At that point, the policy is essentially useless in practice.

    Some insurers are simply refusing to quote for properties with more than two flood claims in the past five years, full stop. Others are offering cover that excludes flood entirely, which creates an interesting legal grey area when homeowners try to sell without disclosing that gap to buyers.

    Which regions are most affected by the new modelling?

    The revised UK flood risk map hits several areas particularly hard. The Thames Estuary beyond Gravesend, large parts of the Norfolk Broads, coastal strips in Kent and East Sussex, the Mersey floodplain around Warrington, and low-lying land around the River Severn in Shropshire and Worcestershire all saw material changes in risk categorisation. Scotland has its own flood risk framework managed by the Scottish Environment Protection Agency (SEPA), and Wales via Natural Resources Wales, both of which have also updated their modelling in line with new climate scenarios.

    Rural areas have not escaped either. Farming communities in the Somerset Levels have faced this reality for over a decade, and the pattern of extreme wet winters is pushing more agricultural land into formal risk categories. This has knock-on effects on rural property values and, indirectly, on the cost of food supply chains. Even the urban fringes are catching it: new-build estates on former industrial brownfield land, which developers often pitched as “flood managed”, are now being reviewed under the updated surface water modelling.

    What can homeowners actually do?

    A few practical steps exist. First, check the Environment Agency map and get an independent flood risk survey if your property sits in or near Zone 2. A specialist report can sometimes be used to challenge a lender’s valuation position or negotiate with insurers. Second, look at physical flood resilience measures: flood doors, non-return valves on drains, raised electrical sockets. DEFRA has a property flood resilience grant scheme available through some local councils for properties that have flooded, worth up to £5,000. Ring your council and ask directly, because these grants are chronically underadvertised.

    Third, if you’re buying in an area that now appears on the updated UK flood risk map, factor in the long-term insurance trajectory, not just the quote you get this year. The affordability picture in five years could look very different. It’s the same kind of forward-looking financial thinking that’s reshaping how younger generations approach big financial decisions altogether, whether that’s retirement savings or housing security.

    And if you’re looking at a property near a main road in a flood-affected zone, here’s a slightly unexpected consideration: road drainage condition directly affects surface water run-off into residential areas. The state of Britain’s road infrastructure is already under enormous pressure, and degraded drainage infrastructure makes localised flooding worse. It all connects.

    The market reality no one wants to say out loud

    Here’s my read on this: a quiet but significant repricing of flood-risk property is already underway in parts of Britain, and most people in affected areas haven’t clocked it yet. The updated UK flood risk map is the mechanism by which that repricing will accelerate. Homes that can’t be insured at a sensible cost, can’t easily attract mortgage lending, and carry a disclosed flood history are going to struggle to hold value. The homeowners who move early, either adapting their properties or diversifying how they think about their assets, are the ones who’ll be in a better position when the rest of the market catches up.

    I’m not saying run. I’m saying: check your postcode, read your policy documents, and stop assuming that nothing has changed since you last looked. It probably has. Industries from real estate to automotive are having to rethink their digital strategies in response to rapid environmental and economic shifts, much like dijitul Automotive is doing in its own sector. Adaptation isn’t optional any more.

    Frequently Asked Questions

    How do I check if my home is on the updated UK flood risk map?

    Go to the Environment Agency’s free online checker at check-long-term-flood-risk.service.gov.uk and enter your postcode. It will show which flood zone your property falls in and whether it faces risk from rivers, the sea, or surface water. The map was updated with new modelling data in 2025 and 2026.

    Will being in a flood risk zone stop me getting a mortgage?

    Being in Flood Zone 2 or 3 does not automatically block a mortgage, but it significantly complicates the process. Lenders instruct valuers to flag flood risk, and some may reduce their loan-to-value ratio or require additional surveys. Properties in Zone 3 with a flood claims history face the most scrutiny.

    What is Flood Re and does my home qualify?

    Flood Re is a government-backed reinsurance scheme that helps keep home insurance affordable for around 250,000 high-risk properties in the UK. To qualify, your property must have been built before 1 January 2009 and must be a private residential home. Leasehold flats and small businesses are generally excluded.

    How much can home insurance premiums increase because of flood risk?

    It varies widely. The ABI reported average home insurance premium increases of 19% year-on-year in early 2026, but flood-risk properties in reclassified zones have seen rises closer to 40% in some regions. Properties with multiple previous flood claims may find some insurers refusing to quote at all.

    Can I get financial help to make my home more flood resilient?

    Yes. DEFRA’s property flood resilience grant offers up to £5,000 for eligible homes that have experienced flooding, available through local councils. Eligible improvements include flood doors, non-return drain valves, and raised electrical sockets. Contact your local council directly as the scheme is not well publicised.

  • Why Thousands of British Graduates Are Choosing Not to Use Their Degrees, and Thriving Anyway

    Why Thousands of British Graduates Are Choosing Not to Use Their Degrees, and Thriving Anyway

    There is a conversation happening in university cities across Britain right now, and it is not the one careers advisers had planned. It goes something like this: spent three years studying, racked up £50,000 in debt, graduated with a 2:1, and now… what exactly? For a growing number of UK graduates, the answer is not a grad scheme in their subject area. It is a plastering course in Sheffield, a Shopify store in Bristol, a food van in Glasgow, or a photography business built from a bedroom in Leeds. UK graduate underemployment 2026 is not a niche concern any more; it has become a structural feature of British working life.

    Young UK graduate working independently on laptop, reflecting uk graduate underemployment 2026 trends
    Photo by TBD Tuyên on Pexels

    The numbers are blunt. According to the Office for National Statistics, roughly a third of UK graduates are working in roles that do not require a degree. That figure has barely shifted in a decade, which should tell us something about how the economy actually absorbs graduate talent versus how it promises to. The Russell Group narrative, that a prestigious degree leads predictably to a prestigious career, has always needed a closer look. In 2026, more graduates are doing exactly that.

    The rise of the trades as a genuine graduate path

    One of the more quietly dramatic shifts I have noticed over the past couple of years is the number of graduates going into skilled trades. Not because they could not find anything else, but because they sat down and did the maths. An electrician with a fully booked diary in Manchester or Birmingham can clear £55,000 to £70,000 a year. A self-employed plumber who is good at the work and better at running their books does not need a degree to out-earn most of the people they went to university with. The trade shortage in the UK is real, and it has made space for a younger, university-educated cohort who bring business literacy alongside the technical skills.

    This is not a return to old ideas about who does what kind of work. A lot of these graduates are using what they actually learnt at university, project management, financial reasoning, client communication, and applying it to trades. They are not abandoning their education; they are just refusing to let it define the only acceptable shape of their career.

    Entrepreneurship as the new graduate scheme

    For others, the draw is building something. Starting a business has never been structurally easier in the UK, even if the economic headwinds remain uncomfortable. E-commerce, freelance services, digital products, content creation, the barriers to entry have collapsed for anyone with a laptop and a bit of determination. I have spoken to graduates running six-figure Etsy operations, building SaaS tools for niche industries, and running creative studios that a decade ago would have required significant investment to get off the ground.

    The entrepreneur route does require one thing a degree does not automatically provide: a presence online. Making your own website used to mean hiring a developer or learning to code. That is no longer the reality. Based in Nottingham, Inuvate offers a free website service for people starting a business, you only pay for hosting, which has made the diy websites route genuinely viable for graduates who need a professional front-end without the upfront cost. For anyone building a freelance portfolio or launching their first product, having inuvate.co.uk in your toolkit means the entrepreneur path does not require a four-figure agency invoice just to look credible. Starting a business in 2026 is less about capital and more about knowing where to find the right tools cheaply.

    Young electrician in UK home showing graduate career shift related to uk graduate underemployment 2026
    Photo by https://kaboompics.com/ on Pexels

    Does a Russell Group degree still pay off?

    The honest answer is: it depends on what you studied and how much debt you took on, and fewer graduates are pretending otherwise. Graduate premium calculations, the extra lifetime earnings a degree supposedly delivers, were always aggregate figures that flattened enormous variation. A law or medicine degree from UCL still opens specific doors that are very hard to reach any other way. A humanities degree from a mid-table Russell Group university? The return on investment has got genuinely murkier.

    The Institute for Fiscal Studies has been pointing this out for years. Roughly a fifth of graduates actually earn less, over their working lives, than people who went straight into employment at 18. That is not a fringe statistic. It is a real indictment of the idea that any degree, from any institution, is worth the debt attached to it. The problem is that UK graduate underemployment 2026 still gets framed as a personal failing rather than a structural outcome, which is unfair and unhelpful.

    There is also an honest conversation to be had about what the UK economy actually needs right now versus what universities produce. Britain has a severe shortage of skilled tradespeople, a funding gap in its creative industries, and a desperately under-served SME sector. Meanwhile, graduates in certain oversupplied humanities and business fields are queuing for the same handful of entry-level marketing roles in London. The mismatch is not a secret; it is just uncomfortable for institutions with financial reasons to keep recruiting.

    The creative industry pivot

    Then there is a third group that does not fit neatly into either trades or entrepreneurship: the graduates pivoting hard into creative work. Photographers, videographers, graphic designers, UX writers, music producers, set designers. Many of them have degrees, sometimes in the creative subject they are now pursuing professionally, sometimes in something completely unrelated. What they share is the decision to treat their creative skills as the actual career rather than a side project waiting until the “real” career stabilised.

    This group overlaps significantly with the self-employment boom the UK has seen since 2020. Creative freelancers are the same generation choosing experiences over conventional financial planning, and they tend to be candid about the trade-offs: income unpredictability, no statutory sick pay, the grind of self-promotion. But they are also building skills portfolios that no single employer owns, and that flexibility has real value.

    What’s actually driving the shift away from degree-related careers

    A few things are happening simultaneously. Graduate salaries in many sectors have not kept pace with the cost of living. The economic anxiety driving so many financial decisions among younger Britons is sharpening the focus on actual earning potential rather than prestige narratives. Remote work has broken the London-centric logic that used to make certain graduate careers feel obligatory. And social media has made it far more visible that alternative paths actually work.

    The graduates I find most interesting are not the ones rejecting their education out of resentment. They are the ones who learnt to think at university and are now applying that thinking to problems the degree syllabus never covered. One example that keeps coming up: graduates starting online businesses who need a professional web presence from day one without burning through their startup budget. The diy websites space has matured significantly, and services like Inuvate, where starting a business online means paying for hosting rather than a full build, have become a legitimate first step for entrepreneurs who are making your own website the practical foundation of a real operation. That kind of resourcefulness is very much part of the graduate-turned-entrepreneur story in 2026.

    Is the system starting to catch up?

    Slowly. Some universities have started being more honest in open days about employment outcomes broken down by course and campus, rather than aggregating across their whole institution. The government’s graduate outcomes data, published annually, has become harder to ignore. And there is a growing employer conversation, particularly in tech and creative sectors, about skills-based hiring over degree requirements, though progress there is inconsistent.

    For graduates currently navigating an economy full of structural potholes, the practical advice is less romantic but more useful: audit what you can actually do, not just what your qualification says you studied. The trades are busy, the creative economy has gaps, and the tools to start something yourself have never been more accessible. A degree is worth exactly what you make it, and for a growing number of British graduates, that means making something entirely their own.

    Frequently Asked Questions

    What is UK graduate underemployment and how bad is it in 2026?

    UK graduate underemployment refers to graduates working in jobs that do not require a degree. The ONS estimates roughly a third of UK graduates are in this position, a figure that has remained stubbornly consistent for over a decade. In 2026, rising living costs and a competitive job market have made the issue more visible than ever.

    Is a Russell Group degree still worth the debt in the UK?

    For certain subjects, medicine, law, engineering, the career pathways and earning premium remain strong. For others, particularly oversupplied humanities and business fields, the Institute for Fiscal Studies has found that around a fifth of graduates earn less over their lifetimes than peers who entered work at 18. Subject choice matters more than institution prestige alone.

    Are UK graduates actually succeeding in trades and self-employment?

    Yes, increasingly so. Skilled trades in the UK are experiencing a significant shortage, which has driven wages up considerably, experienced self-employed electricians and plumbers in major UK cities can earn well above the average graduate salary. In self-employment, lower barriers to starting an online business have made the route viable without large upfront capital.

    What support exists for UK graduates who want to start their own business?

    The UK government’s Start Up Loans scheme offers government-backed loans of up to £25,000 for new businesses, alongside free mentoring. Beyond funding, graduates can access low-cost or free tools for building an online presence, managing accounts, and marketing, meaning the initial cost of self-employment is lower than many expect.

  • The UK’s Pothole Crisis Has Reached Breaking Point, Here’s What It’s Actually Costing Drivers

    The UK’s Pothole Crisis Has Reached Breaking Point, Here’s What It’s Actually Costing Drivers

    British roads are falling apart. Not slowly, not quietly, but in a very visible, tyre-blowing, suspension-destroying way that is costing ordinary drivers serious money. The numbers behind pothole damage claims UK-wide have reached a level that would be embarrassing if anyone in charge seemed particularly bothered. Spoiler: they don’t.

    I drove through parts of the West Midlands last month and genuinely thought I’d accidentally turned onto a building site. I hadn’t. That was just the A road. The craters were so deep my coffee went over the cup holder. Welcome to Britain in 2026.

    Deep potholes on a deteriorating UK road surface illustrating the pothole damage claims UK crisis
    Photo by Mike Bird on Pexels

    How bad is the pothole problem right now?

    The Asphalt Industry Alliance, which publishes the Annual Local Authority Road Maintenance (ALARM) survey each year, reported in 2025 that it would cost over £16 billion to bring English and Welsh local roads back up to a reasonable standard. That figure has crept up year on year, and there is no realistic funding plan to close that gap. England alone has a backlog running into the billions, and the pace of deterioration keeps outrunning repair.

    Local councils reported filling around 1.7 million potholes in England and Wales over a single twelve-month period, but patching is not fixing. A lot of those repairs are cold-fill patches that crack and crumble within weeks, especially during wet winters. The cycle of patch-and-crumble costs money without actually solving anything.

    What drivers are actually spending on pothole damage claims UK-wide

    The RAC reported a sharp rise in pothole-related breakdowns throughout 2024 and into 2025. Broken shock absorbers, cracked alloy wheels, buckled rims and burst tyres are the most common outcomes of hitting a serious crater at speed. Repair bills for this kind of damage typically run between £150 and £500, and if you’re unlucky enough to damage steering geometry or a suspension arm, you’re looking at closer to £1,000 or more.

    Pothole damage claims submitted to local councils run into tens of thousands every year, but the success rate is low. Councils can reject claims if they can prove they had no prior knowledge of the pothole, or if they can show it was inspected within a reasonable timeframe under their duty of care obligations. Many drivers give up after their first rejection. The whole process feels deliberately exhausting, which, honestly, it probably is.

    Is council funding actually the problem?

    The easy answer is yes. The more complicated answer is: yes, but it’s not the only factor.

    Local council highways budgets have been under sustained pressure since 2010. The Local Government Association has repeatedly flagged that councils are having to make impossible choices between statutory services like social care, housing and waste collection, and discretionary maintenance spending on roads. Roads, which don’t vote and don’t complain to councillors, tend to lose those arguments.

    In autumn 2024, the government announced £500 million of additional pothole-repair funding as part of its budget. It made headlines for about two days. To put that in context against the £16 billion backlog, it covers roughly 3% of the problem. The rest sits on councils’ books as an unfunded liability. The gap between announcement-level politics and actual road quality is enormous, and drivers are literally feeling it every day.

    There’s also a deeper structural issue. Road materials and construction labour costs rose significantly post-2020, which means the same budget repairs fewer potholes than it did five years ago. Inflation in the highways sector hit councils hard, and most have not had their grants uplifted to compensate.

    How to actually make a pothole damage claim

    If your car takes damage from a pothole, you have a legal right to claim against the responsible highway authority. For most roads that’s the local council; for motorways and A-roads it’s National Highways. Here’s what gives you the best chance of a payout:

    Photograph everything immediately. The pothole itself, its dimensions if you can capture them safely, the damage to your vehicle, and the road markings around it. Get the exact location, ideally with a postcode or GPS coordinates. Then check the council’s own reporting portal to see if the pothole had already been logged. If it had, your claim becomes much stronger because it demonstrates prior knowledge. Submit your claim in writing, keep copies of every receipt, and if the council rejects it, ask specifically which inspection records they are relying on to prove reasonable maintenance.

    The money you’re owed isn’t guaranteed, but a well-documented claim is harder to dismiss. My take: the councils counting on you to give up after round one are banking on bureaucratic fatigue. Don’t give them the satisfaction.

    The wider drain on British wallets

    Potholes are not just a transport issue. They’re a financial one that touches everything. Delivery drivers, tradespeople, commuters, anyone who relies on their vehicle for work is absorbing repair costs that quietly eat into earnings. This sits alongside a broader picture of financial pressure that’s worth acknowledging. Articles on this blog have already looked at doom spending and how economic anxiety is affecting British bank accounts, and the pothole problem is just another chip in the armour of household budgets that are already stretched.

    There’s also the indirect cost. A vehicle running on damaged suspension burns more fuel, is more likely to fail its MOT, and depreciates faster. None of that shows up in pothole damage claims statistics, but it’s real money leaving real households.

    For freelancers and self-employed workers who put high mileage on their cars, this is particularly brutal. If you’re already navigating the UK’s inadequate safety nets for workers, an unexpected £400 tyre-and-rim bill is not a minor inconvenience. It can genuinely derail a month.

    What needs to change

    A long-term, ring-fenced roads maintenance fund, separate from council general budgets, is the most-cited fix from highways engineers and transport campaigners. Some argue for greater use of machine learning to identify deteriorating road surfaces before they become potholes, using vehicle telemetry data from connected cars. A handful of councils in the East Midlands have trialled predictive maintenance software with reasonable results, though the upfront cost puts most cash-strapped authorities off.

    The honest reality is that roads in Britain are a low-glamour infrastructure problem competing for attention against everything else. They will keep losing that competition until either the funding model changes fundamentally or enough voters get loud enough about the state of the tarmac outside their door.

    Until then, if you’re dealing with the financial strain of maintaining your home and your car simultaneously, the advice is the same: document everything, claim what you’re owed, and don’t let councils fob you off with a form rejection. The roads belong to all of us. So does the right to be compensated when they’re left in a state that wrecks our vehicles.

    Frequently Asked Questions

    How do I make a pothole damage claim against my local council?

    Photograph the pothole and your vehicle damage immediately, note the exact location, and check whether the pothole was already reported to the council. Submit a written claim to the local highways authority with all receipts and evidence. If rejected, ask them to provide their inspection records under the Highways Act 1980 duty of care.

    How much can I claim for pothole damage to my car?

    There is no fixed cap, and your claim should cover the actual cost of repairs, supported by receipts from a garage. Common claims range from £100 to £500 for tyres and alloy wheels, rising to £1,000 or more if suspension or steering components are damaged. Keep every receipt and get more than one quote where possible.

    Can councils legally reject my pothole damage claim?

    Yes. Under the Highways Act 1980, a council can avoid liability if it demonstrates it had a reasonable system of inspection and repair in place and had no prior knowledge of the defect. This is called the ‘Section 58 defence’. A well-documented claim showing the pothole had already been reported can significantly weaken this defence.

    Who is responsible for fixing potholes on motorways vs local roads?

    Motorways and the strategic A-road network in England are managed by National Highways, and claims for those roads go to them directly. Most other roads, including local A-roads, B-roads and residential streets, are the responsibility of the local county or unitary authority council.

    Why are UK potholes getting worse in 2026?

    Years of underfunded local highways maintenance budgets, rising repair costs due to inflation, and wetter winters accelerating road surface deterioration have all combined. The Asphalt Industry Alliance estimates the repair backlog for England and Wales now exceeds £16 billion, with no credible plan to clear it at current funding levels.